



 Chat with AI
Exam 9: Deductions: Employee and Self-Employed-Related Expenses

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


The tax law specifically provides that a taxpayer cannot be temporarily away from home for any period of employment that exceeds one year.
(True/False)
4.9/5  (84)
(84) A moving expense deduction is allowed even if at the time of the move the taxpayer did not have a job at the new location.
(True/False)
4.9/5 (85)
(85) Elaine, the regional sales director for a manufacturer of exercise equipment, pays $2,500 to rent a skybox for a visiting performance of the Harlem Globetrotters.The skybox holds 10 seats, and Elaine invites 7 clients to the event.Nonluxury seats range in price from $80 to $120.The refreshments provided during the event cost $600.If Elaine meets all of the requirements for deductibility (i.e., business discussion, substantiation), she may deduct:
(Multiple Choice)
4.7/5 (80)
(80) Dove Corporation pays for a trip to Jamaica for its two top salespersons.This expense is not subject to the cutback adjustment.
(True/False)
4.8/5 (72)
(72) Jake performs services for Maude. If Jake provides his own helper and tools, this is indicative of independent contractor (rather than employee) status.
(True/False)
4.9/5 (67)
(67) The IRS will not issue advanced rulings as to whether a worker's status is that of an employee or an independent contractor.
(True/False)
4.9/5 (90)
(90) As Christmas presents, Lily sends gift certificates (each valued at $25) to Caden (a key client) and to each of his two minor children.Lily can deduct $75 (3 ´ $25) as to these gifts.
(True/False)
4.8/5 (77)
(77) Qualified moving expenses of an employee that are not reimbursed are a deduction for AGI.
(True/False)
4.8/5 (80)
(80) By itself, credit card receipts will constitute adequate substantiation for travel expenses.
(True/False)
4.7/5 (76)
(76) Aaron is a self-employed practical nurse who works out of his home.He provides nursing care for disabled persons living in their residences.During the day he drives his car as follows. 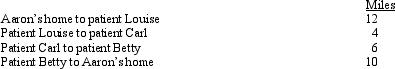 Aaron's deductible mileage for each workday is:
 (Multiple Choice)
4.7/5 (84)
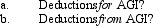
(84) Arnold is employed as an assistant manager in the furniture division of a national chain of department stores.He is a recent college graduate with a degree in marketing.During 2012, he enrolls in the evening MBA program of a local university and incurs the following expenses: tuition, $4,200; books and computer supplies, $800; transportation expense to and from the university, $450; and meals while on campus, $400.Arnold is single and his annual AGI is $66,000.As to these expenses, what are Arnold's:
(Essay)
4.7/5 (71)
(71) Jackson gives his supervisor a $30 box of chocolates on her birthday.Jackson may claim only $25 as a deduction.
(True/False)
4.8/5 (73)
(73) Alfredo, a self-employed patent attorney, flew from his home in Chicago to Miami, had lunch alone at the airport, conducted business in the afternoon, and returned to Chicago in the evening.His expenses were as follows:
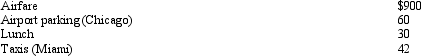 What is Alfredo's deductible expense for the trip?
 (Essay)
5.0/5 (74)
(74) Which, if any, of the following expenses is subject to the 2%-of-AGI floor?
(Multiple Choice)
4.8/5 (80)
(80) As to meeting the time test for purposes of deducting moving expenses, which of the following statements is correct?
(Multiple Choice)
4.8/5 (79)
(79) If a business retains someone to provide services, that person may either be an employee or be self-employed (i.e., independent contractor).
(Essay)
4.8/5 (88)
(88) Debby is a self-employed accountant with a qualified defined benefit plan (a Keogh plan).She has the following income items for the year:
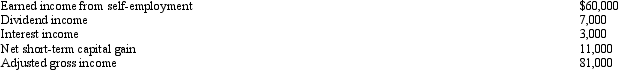 What is the maximum amount Debby can deduct as a contribution to her retirement plan in 2012, assuming the self-employment tax rate is 15.3%?
 (Multiple Choice)
4.9/5 (74)
(74) After she finishes working at her main job, Ann returns home, has dinner, then drives to her second job.Ann may deduct the mileage between her home and second job.
(True/False)
4.8/5 (77)
(77) The portion of the office in the home deduction that exceeds the income from the business can be carried over to future years.
(True/False)
4.9/5 (72)
(72) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)