



 Chat with AI
Exam 14: Taxes on the Financial Statements

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations109 Questions
Exam 4: Corporations: Organization and Capital Structure92 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions130 Questions
Exam 6: Corporations: Redemptions and Liquidations115 Questions
Exam 7: Corporations: Reorganizations140 Questions
Exam 8: Consolidated Tax Returns175 Questions
Exam 9: Taxation of International Transactions177 Questions
Exam 10: Partnerships: Formation, Operation, and Basis135 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations144 Questions
Exam 12: S: Corporations158 Questions
Exam 13: Comparative Forms of Doing Business170 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities185 Questions
Exam 16: Multistate Corporate Taxation187 Questions
Exam 17: Tax Practice and Ethics174 Questions
Exam 18: The Federal Gift and Estate Taxes222 Questions
Exam 19: Family Tax Planning188 Questions
Exam 20: Income Taxation of Trusts and Estates183 Questions
Select questions type


Qute, Inc., earns book net income before tax of $500,000. In computing its book income, Qute deducts $50,000 more in warranty expense for book purposes than is allowed for tax purposes. Qute records no other temporary or permanent book-tax differences. Assuming that the U.S. tax rate is 35% and no valuation allowance is required, what is Qute's total income tax expense reported on its GAAP financial statements?
(Multiple Choice)
4.9/5  (79)
(79) Giant uses the "equity method" to account for the operations of its 40% owned subsidiary Little. A portion of Little's profits for the year are included in Giant's GAAP book income.
(True/False)
5.0/5 (86)
(86) Amelia, Inc., is a domestic corporation with the following balance sheet for book and tax purposes at the end of the year. Assume a 34% corporate tax rate and no valuation allowance.
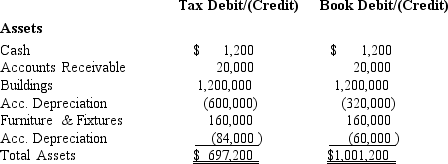
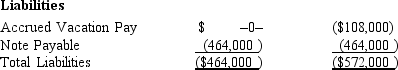
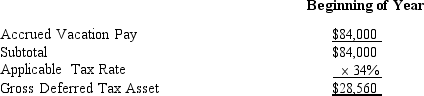
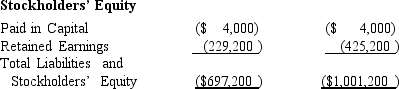 Amelia, Inc.'s, gross deferred tax assets and liabilities at the beginning of Amelia's year are listed below.
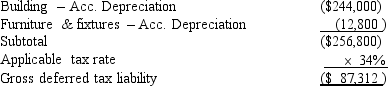 Amelia, Inc.'s, book income before tax is $25,200. Amelia records two permanent booktax differences. It earned $1,000 in tax-exempt municipal bond interest and $1,840 in nondeductible meals and entertainment expense. Provide the journal entry to record Amelia's current tax expense.
Amelia, Inc.'s, gross deferred tax assets and liabilities at the beginning of Amelia's year are listed below.
Amelia, Inc.'s, book income before tax is $25,200. Amelia records two permanent booktax differences. It earned $1,000 in tax-exempt municipal bond interest and $1,840 in nondeductible meals and entertainment expense. Provide the journal entry to record Amelia's current tax expense. (Essay)
4.7/5 (89)
(89) Jogg, Inc., earns book net income before tax of $600,000. Jogg puts into service a depreciable asset this year, and first year tax depreciation exceeds book depreciation by $120,000. Jogg has recorded no other temporary or permanent booktax differences. Assuming that the U.S. tax rate is 35%, and that this is Jogg's first year of operations, what is Jogg's balance in its deferred tax asset and deferred tax liability accounts at year end?
(Multiple Choice)
4.8/5 (95)
(95) An example of a deferred tax asset is the excess of accelerated MACRS depreciation over GAAP straight-line depreciation.
(True/False)
4.8/5 (77)
(77) Gravel, Inc., earns book net income before tax of $600,000. Gravel puts into service a depreciable asset this year, and first year tax depreciation exceeds book depreciation by $120,000. Gravel has recorded no other temporary or permanent booktax differences. Assuming that the U.S. tax rate is 35%, what is Gravel's current income tax expense reported on its GAAP financial statements?
(Multiple Choice)
4.9/5 (77)
(77) A corporation's taxable income almost never is the same as its GAAP financial accounting income. Explain why this occurs. Use the terms permanent and temporary book-tax differences in you answer. Give at least two examples of each type of book-tax difference.
(Essay)
4.8/5 (66)
(66) Hot, Inc.'s primary competitor is Cold, Inc. When comparing relative deferred tax asset and liability accounts with Cold, which of the following benchmarking activities should Hot undertake?
(Multiple Choice)
4.9/5 (78)
(78) Beach, Inc., a domestic corporation, owns 100% of Mountain, Ltd., a manufacturing facility in Ireland. Mountain has no operations or activities in the United States. The U.S. tax rate is 35% and the Irish tax rate is 10%. For the current year, Beach earns $500,000 in taxable income. Mountain earns $300,000 in taxable income from its operations, pays $30,000 in taxes to Ireland, and makes no distributions to Beach. What is Beach's effective tax rate for GAAP book purposes, assuming that Beach makes the permanent reinvestment assumption of ASC 740-30 (APB 23)?
(Multiple Choice)
4.9/5 (77)
(77) Healy, Inc., reports an effective tax rate in its income tax footnote of 14%. The only reconciling item with regard to the hypothetical tax at 35% is a valuation allowance reversal of negative 21%. Which of the following statements is true concerning comparing Healy, Inc.'s effective tax rate with its competitors, all of whom have an effective tax rate between 32 and 36%?
(Multiple Choice)
4.8/5 (82)
(82) Book-tax differences can be explained in part by examining the objectives underlying financial accounting and taxable income computations. Evaluate this statement.
(Essay)
4.9/5 (75)
(75) The current tax expense reported on the GAAP financial statements generally represents the taxes actually payable to domestic or foreign governmental authorities.
(True/False)
4.9/5 (63)
(63) PaintCo Inc., a domestic corporation, owns 100% of BrushCo Ltd., an Irish corporation. Assume that the U.S. corporate tax rate is 35% and the Irish rate is 15%. PaintCo is permanently reinvesting BrushCo's earnings outside the United States under ASC 74030 (APB 23). The corporations' book income, permanent and temporary booktax differences, and current tax expense are reported as follows. Provide the GAAP income tax footnote rate reconciliation for PaintCo using both dollar amounts and percentages.
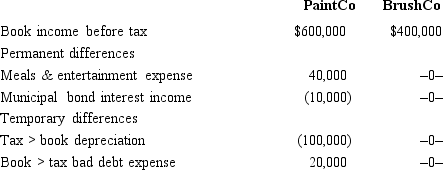
(Essay)
4.8/5 (84)
(84) PaintCo Inc., a domestic corporation, owns 100% of BrushCo Ltd., an Irish corporation. Assume that the U.S. corporate tax rate is 35% and the Irish rate is 15%. PaintCo is permanently reinvesting BrushCo's earnings outside the United States under ASC 74030 (APB 23). The corporations' book income, permanent and temporary booktax differences, and current tax expense are reported as follows. Determine PaintCo's total tax expense reported on its GAAP financial statements, its current tax expense (benefit), and its deferred tax expense (benefit).
PaintCo BrushCo
Book income before tax $600,000 $400,000
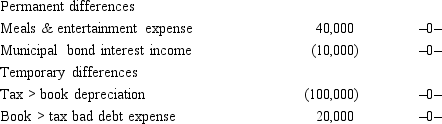
(Essay)
4.9/5 (83)
(83) Repatriating prior year earnings from a foreign subsidiary located in a low-tax country where ASC 740-30 (APB 23) benefits were previously adopted will decrease a corporation's current year effective tax rate.
(True/False)
4.8/5 (85)
(85) Only U.S. corporations are included in a combined GAAP financial statement.
(True/False)
4.7/5 (71)
(71) Kooler, Inc., is a domestic corporation. It owns 100% of Texas, Inc., a domestic corporation, 100% of Paris, a foreign corporation, and 45% of Iowa, Inc., a domestic corporation.
a. Which entities' incomes are included in Kooler's combined GAAP financial statements?
b. How would your answer change if Kooler instead owned 15% of Iowa?
(Essay)
4.8/5 (65)
(65) If a corporation has no operations outside the U.S., its GAAP book and taxable income are identical.
(True/False)
4.8/5 (83)
(83) Amelia, Inc., is a domestic corporation with the following balance sheet for book and tax purposes at the end of the year. Assume a 34% corporate tax rate and no valuation allowance.
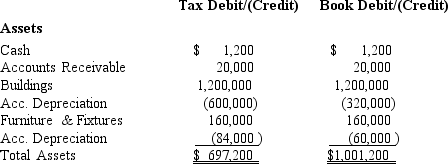
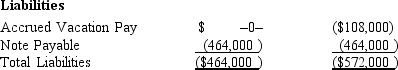
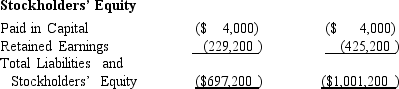 Amelia, Inc.'s, gross deferred tax assets and liabilities at the beginning of Amelia's year are listed below.
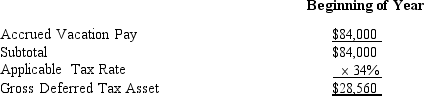
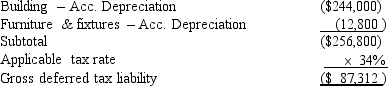 Amelia, Inc.'s, book income before tax is $25,200. Amelia records two permanent book-tax differences. It earned $1,000 in tax-exempt municipal bond interest and $1,840 in nondeductible meals and entertainment expense. Provide the income tax footnote rate reconciliation for Amelia.
Amelia, Inc.'s, gross deferred tax assets and liabilities at the beginning of Amelia's year are listed below.
Amelia, Inc.'s, book income before tax is $25,200. Amelia records two permanent book-tax differences. It earned $1,000 in tax-exempt municipal bond interest and $1,840 in nondeductible meals and entertainment expense. Provide the income tax footnote rate reconciliation for Amelia. (Essay)
4.9/5 (60)
(60) Schedule UTP of the Form 1120 reconciles financial statement net income after tax with a large corporation's taxable income.
(True/False)
4.7/5 (68)
(68) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)