



 Chat with AI
Exam 15: Exempt Entities

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations109 Questions
Exam 4: Corporations: Organization and Capital Structure92 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions130 Questions
Exam 6: Corporations: Redemptions and Liquidations115 Questions
Exam 7: Corporations: Reorganizations140 Questions
Exam 8: Consolidated Tax Returns175 Questions
Exam 9: Taxation of International Transactions177 Questions
Exam 10: Partnerships: Formation, Operation, and Basis135 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations144 Questions
Exam 12: S: Corporations158 Questions
Exam 13: Comparative Forms of Doing Business170 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities185 Questions
Exam 16: Multistate Corporate Taxation187 Questions
Exam 17: Tax Practice and Ethics174 Questions
Exam 18: The Federal Gift and Estate Taxes222 Questions
Exam 19: Family Tax Planning188 Questions
Exam 20: Income Taxation of Trusts and Estates183 Questions
Select questions type


Give an example of the indicated types of exempt organizations.
-§ 501(c)(4) civic league
(Multiple Choice)
4.9/5  (67)
(67) Which of the following activities is not subject to the feeder organization rules?
(Multiple Choice)
4.9/5 (84)
(84) Faith Church, a § 501(c)(3) organization, operates a bingo game two times each week to raise money to support the youth activities of the church. For the current year, net proceeds from the bingo game are $900,000.
a. Determine the tax consequences for Faith Church if the bingo game is conducted in a state where for-profit bingo games are illegal, and where the bingo game is legal for exempt entities.
b. Determine the tax consequences for Faith Church if the bingo game is conducted in a state and locality where bingo games are legal for both for-profit and exempt entities.
(Essay)
4.8/5 (91)
(91) For an activity to be considered as regularly carried on for purposes of the unrelated business income tax, the activity must be conducted during the work week (i.e., activities performed on the weekend are not considered in determining if the activity is regularly carried on).
(True/False)
4.8/5 (78)
(78) Which of the following excise taxes are imposed on private foundations?
(Multiple Choice)
4.8/5 (77)
(77) The trade or business of selling merchandise where substantially all of the merchandise has been received as contributions or gifts is not subject to the unrelated business income tax, but is subject to the tax on feeder organizations.
(True/False)
4.8/5 (91)
(91) Which of the following statements regarding the unrelated business income tax is correct?
(Multiple Choice)
4.8/5 (71)
(71) First Americans, Inc., a § 501(c)(3) organization, operates a museum which depicts the lives of a tribe of Native Americans. It charges an admission fee, but also finances its operations through endowment income, contributions, and gift shop sales. The gift shop is operated by 50 volunteers and the museum is operated by 15 employees. Revenue by source is:
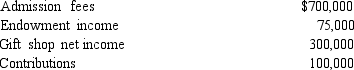 a. Determine the amount of First Americans' unrelated business income.
b. Determine the amount of First American's unrelated business income tax (UBIT).
a. Determine the amount of First Americans' unrelated business income.
b. Determine the amount of First American's unrelated business income tax (UBIT). (Essay)
4.9/5 (78)
(78) Unrelated debt-financed income, net of the unrelated debt-financed deductions, is subject to the unrelated business income tax only if the exempt organization is a private foundation.
(True/False)
4.8/5 (87)
(87) Hope, Inc., an exempt organization, owns a factory building that it leases to a taxable corporation for $100,000 per year. Related expenses for Hope are $30,000. Hope's average acquisition indebtedness on the building is $400,000 and the average adjusted basis is $600,000. Calculate Hope's unrelated debtfinanced income and expenses. Then indicate the effect of these items on unrelated business taxable income.
(Essay)
5.0/5 (89)
(89) An educational organization such as the College of William and Mary that is exempt under § 501(c)(3) cannot be classified as a private foundation if its only sources of revenue are from tuition and alumni contributions.
(True/False)
4.8/5 (82)
(82) Discuss any negative tax consequences that result from an exempt organization being classified as a private foundation.
(Essay)
4.8/5 (63)
(63) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)