



 Chat with AI
Exam 15: Alternative Minimum Tax

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: A: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


Eula owns a mineral property that had a basis of $23,000 at the beginning of the year.Cost depletion is $19,000.The property qualifies for a 15% depletion rate.Gross income from the property was $200,000 and net income before the percentage depletion deduction was $50,000.What is Eula's tax preference for excess depletion?
(Multiple Choice)
5.0/5  (77)
(77) The deduction for charitable contributions in calculating the regular income tax can differ from that in calculating the AMT because the percentage limitations (20%, 30%, and 50%) may be applied to a different base amount.
(True/False)
4.9/5 (78)
(78) Prior to the effect of tax credits, Eunice's regular income tax liability is $325,000 and her tentative AMT is $312,000.Eunice has general business credits available of $20,000.Calculate Eunice's tax liability after tax credits.
(Multiple Choice)
4.9/5 (84)
(84) The AMT exemption for a C corporation is $40,000 reduced by 35% of the amount by which AMTI exceeds $150,000.
(True/False)
4.9/5 (71)
(71) When qualified residence interest exceeds qualified housing interest, the positive adjustment required in calculating AMT is a timing adjustment.That is, in the future, there will be an offsetting negative adjustment.Comment on the validity of this statement.
(Essay)
4.9/5 (74)
(74) Luke's itemized deductions in calculating taxable income are as follows:
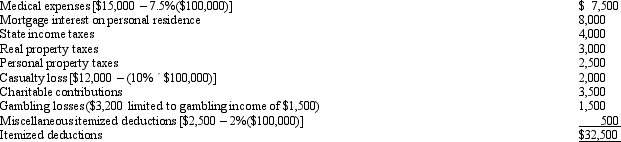
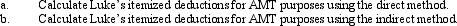
(Essay)
4.8/5 (86)
(86) Danica owned a car that she used exclusively for business.The car was purchased in 2010 and sold in 2012 for a recognized gain of $9,000.However, the sale resulted in no AMT.Why?
(Essay)
4.7/5 (72)
(72) Ashlyn is subject to the AMT in 2012.She calculates her AMT base to be $200,000.What are the AMT rates that apply for Ashlyn?
(Essay)
4.9/5 (66)
(66) All of a C corporation's AMT is available for carryover as a minimum tax credit regardless of whether the adjustments and preferences originate from timing differences or AMT exclusions.
(True/False)
4.8/5 (83)
(83) Tad and Audria, who are married filing a joint return, have AMTI of $256,000 for 2012. Calculate their AMT exemption.
(Essay)
4.8/5 (89)
(89) Evan is a contractor who constructs both commercial and residential buildings. Even though some of the contracts could qualify for the use of the completed contract method, Evan decides to use the percentage of the completion method for all of his contracts. Therefore, no AMT adjustment is required.
(True/False)
4.9/5 (72)
(72) What is the purpose of the AMT exemption amount? What is the maximum amount for each filing status for an individual taxpayer and for a corporate taxpayer?
(Essay)
4.7/5 (71)
(71) Tammy expensed mining exploration and development costs of $100,000 incurred in 2012.She will be required to make negative AMT adjustments for each of the next nine years and a positive AMT adjustment in the current tax year.
(True/False)
4.8/5 (68)
(68) Andrea, who is single, has a personal exemption deduction in calculating her 2012 taxable income.She has no dependency deductions.What is the amount of the AMT adjustment in calculating AMTI?
(Essay)
4.9/5 (86)
(86) The C corporation AMT rate can be higher than the individual AMT rates.
(True/False)
4.9/5 (77)
(77) Meg, who is single and age 36, provides you with the following information from her financial records.  Calculate her AMT exemption for 2012.
 (Multiple Choice)
4.8/5 (70)
(70) AGI is used as the base for application of percentage limitations (i.e., 20%, 30%, 50%) that apply to the charitable contribution deduction for regular income tax purposes. Modified AGI is used as the base for application of percentage limitations that apply to the charitable contribution deduction for AMT purposes.
(True/False)
4.9/5 (73)
(73) For individual taxpayers, the AMT credit is applicable for the AMT that results from timing differences, but it is not available for the AMT that results from the adjustment for itemized deductions or exclusion preferences.
(True/False)
4.8/5 (88)
(88) The required adjustment for AMT purposes for pollution control facilities placed in service in 2012 is equal to the difference between the amortization deduction allowed for regular income tax purposes and the depreciation deduction computed under ADS.
(True/False)
5.0/5 (86)
(86) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)