



 Chat with AI
Exam 15: Alternative Minimum Tax

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: A: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


If circulation expenditures are amortized over a ten-year period for regular income tax purposes, there will be no AMT adjustment.

Free
(True/False)
4.8/5  (84)
(84) Correct Answer: Verified
False
The amount of the deduction for medical expenses under the regular income tax may be different than for AMT purposes.
Free
(True/False)
4.9/5 (83)
(83) Correct Answer:Verified
VerifiedTrue
In deciding to enact the alternative minimum tax, Congress was concerned about the inequity that resulted when taxpayers with substantial economic incomes could avoid paying regular income tax.
Free
(True/False)
4.8/5 (72)
(72) Correct Answer:Verified
VerifiedTrue
Tad is a vice-president of Ruby Corporation. In 2012, he acquired 800 shares of Ruby Corporation stock under the corporation's incentive stock option (ISO) plan for an option price of $33 per share. At the date of exercise in 2012, the fair market value of the stock was $43 per share. The stock became freely transferable in 2013. Tad sold the 800 shares for $50 per share in 2014. Which of the following statements is incorrect?
(Multiple Choice)
4.9/5 (77)
(77) Sand Corporation, a calendar year taxpayer, has alternative minimum taxable income [before adjustment for adjusted current earnings (ACE)] of $750,000 for 2012.If Sand's (ACE) is $975,000, its tentative minimum tax for 2012 is:
(Multiple Choice)
4.8/5 (82)
(82) Are the AMT rates for the individual taxpayer the same as those for a corporate taxpayer?
(Essay)
4.8/5 (74)
(74) Omar acquires used 7-year personal property for $100,000 to use in his business in February 2012.Omar does not elect § 179 expensing, but does take the maximum regular cost recovery deduction.He elects not to take additional first-year depreciation.As a result, Omar will have a positive AMT adjustment in 2012 of what amount?
(Multiple Choice)
4.8/5 (75)
(75) In 2012, Sean incurs $90,000 of mining exploration expenditures, and deducts the entire amount for regular income tax purposes.Which of the following statements is correct?
(Multiple Choice)
4.9/5 (87)
(87) Ashly is able to reduce her regular income tax liability from $47,000 to $43,500 as the result of the alternative tax on net capital gain.Ashly's tentative AMT is $51,000.
(Multiple Choice)
4.9/5 (82)
(82) If the taxpayer elects to capitalize intangible drilling costs and to amortize them over a 10-year period for regular income tax purposes, there is no adjustment or preference for AMT purposes.
(True/False)
4.8/5 (78)
(78) For regular income tax purposes, Yolanda, who is single, is in the 35% tax bracket.Her AMT base is $220,000.Her tentative AMT is:
(Multiple Choice)
4.7/5 (90)
(90) How can interest on a private activity bond issued in 2008 result in both an AMT adjustment that decreases AMTI and an AMT preference that increases AMTI?
(Essay)
4.9/5 (81)
(81) Altrice incurs circulation expenditures of $180,000 in 2012.No additional circulation expenditures are incurred in 2013 or 2014.The cumulative adjustment for circulation expenditures for 2012, 2013, and 2014 is $180,000.
(True/False)
4.7/5 (92)
(92) The sale of business property might result in an AMT adjustment.
(True/False)
4.7/5 (78)
(78) Smoke, Inc., provides you with the following information:
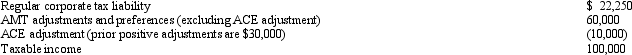 Calculate Smoke's AMT for 2012.
 (Essay)
4.9/5 (78)
(78) Identify an AMT adjustment that applies for the individual taxpayer that does not apply for the corporate taxpayer and identify an AMT adjustment that applies for the corporate taxpayer that does not apply for the individual taxpayer.
(Essay)
4.8/5 (76)
(76) In calculating her taxable income, Rhonda deducts the following itemized deductions.
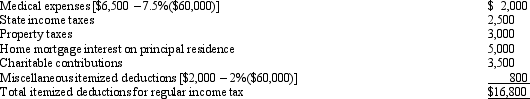 Calculate Rhonda's AMT adjustment for itemized deductions.
 (Essay)
4.8/5 (83)
(83) Vinny's AGI is $220,000.He contributed $130,000 in cash to the Boy Scouts, a public charity.What is Vinny's charitable contribution deduction for AMT purposes?
(Multiple Choice)
4.9/5 (83)
(83) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)