



 Chat with AI
Exam 15: Alternative Minimum Tax

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: A: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


In 2012, Ben exercised an incentive stock option (ISO), acquiring stock with a fair market value of $190,000 for $170,000.His AMT basis for the stock is $170,000, his regular income tax basis for the stock is $170,000, and his AMT adjustment is $0 ($170,000 - $170,000).
(True/False)
4.9/5  (76)
(76) The phaseout of the AMT exemption amount for a taxpayer filing as a head of household both begins and ends at a higher income level than it does for a single taxpayer.
(True/False)
4.7/5 (92)
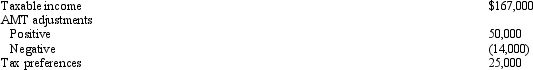
(92) Robin, who is a head of household and age 42, provides you with the following information from his financial records for 2012.  Calculate his AMT for 2012.
 (Multiple Choice)
4.8/5 (68)
(68) In 2012, Amber had a $100,000 loss on a passive activity.None of the loss is attributable to AMT adjustments or preferences.She has no other passive activities.Which of the following statements is correct?
(Multiple Choice)
4.8/5 (82)
(82) Since most tax preferences are merely timing differences, they eventually will reverse and net to zero.
(True/False)
4.8/5 (67)
(67) Mauve, Inc., has the following for 2011, 2012, and 2013 and no prior ACE adjustments. 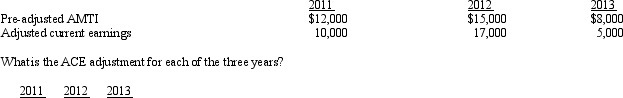
(Multiple Choice)
4.8/5 (77)
(77) Nell has a personal casualty loss deduction of $14,500 for regular income tax purposes. The deduction would have been $26,600, but it had to be reduced by $100 and by $12,000 (10% ´ $120,000 AGI). For AMT purposes, the casualty loss deduction is $26,600.
(True/False)
4.8/5 (93)
(93) How can the positive AMT adjustment for research and experimental expenditures be avoided?
(Essay)
4.8/5 (82)
(82) Is it possible that no AMT adjustment is necessary for medical expenses in calculating AMTI even though the floor limitation is different (7.5% of AGI for regular income tax compared to 10% for AMT purposes)?
(Essay)
4.7/5 (78)
(78) Miriam, who is a head of household and age 36, provides you with the following information from her financial records for 2012.  Calculate her AMTI for 2012.
 (Multiple Choice)
4.9/5 (85)
(85) The deduction for personal and dependency exemptions is allowed for regular income tax purposes, but is disallowed for AMT purposes. This results in a positive AMT adjustment.
(True/False)
4.9/5 (88)
(88) In 2012, Louise incurs circulation expenses of $330,000 which she deducts in calculating taxable income.
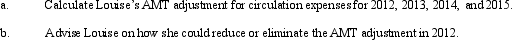
(Essay)
4.8/5 (74)
(74) Prior to the effect of the tax credits, Justin's regular income tax liability is $200,000 and his tentative AMT is $195,000.Justin has the following credits:  Calculate Justin's tax liability after credits.
 (Multiple Choice)
4.9/5 (78)
(78) On January 3, 1998, Parrot Corporation acquired an office building for $300,000 and computed depreciation under ADS (Alternative Depreciation System) for regular income tax purposes. The ADS rate for the first year is 2.396% and for the fifteenth year is 2.50% (MACRS rates would have been 2.461% and 2.564% respectively). What is Parrot's AMT adjustment (or preference) for depreciation with respect to the office building for 1998 and for 2012?
(Multiple Choice)
4.9/5 (76)
(76) 
For the ACE adjustment, discuss the relationship between ACE and unadjusted AMTI.
(Essay)
4.8/5 (84)
(84) Why is there a need for a second tax system called the alternative minimum tax?
(Essay)
4.9/5 (75)
(75) Kaya is in the 33% marginal tax bracket.She has a net capital gain of $90,000 on the sale of land which is eligible for the alternative tax on net capital gain in calculating the regular income tax.Discuss the tax rate that applies to the $90,000 net capital gain in calculating the tentative AMT for Kaya.
(Essay)
4.9/5 (75)
(75) What itemized deductions are allowed for both regular income tax purposes and for AMT purposes?
(Essay)
4.9/5 (83)
(83) If Abby's alternative minimum taxable income exceeds her regular taxable income, she will have an alternative minimum tax.
(True/False)
4.8/5 (90)
(90) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)