



 Chat with AI
Exam 15: Alternative Minimum Tax

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: A: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


Jackson sells qualifying small business stock for $125,000 (adjusted basis of $105,000) in 2012. In calculating gross income for regular income tax purposes, he excludes all of his realized gain of $20,000.The $20,000 exclusion is a tax preference in calculating Jackson's AMTI.
(True/False)
4.8/5  (80)
(80) Tricia sold land that originally cost $105,000 for $112,000.There is a positive AMT adjustment of $7,000 associated with the sale of the land.
(True/False)
4.8/5 (82)
(82) Mitch, who is single and has no dependents, had AGI of $100,000 in 2012.His potential itemized deductions were as follows:  What is the amount of Mitch's AMT adjustment for itemized deductions for 2012?
 (Multiple Choice)
4.9/5 (79)
(79) Celia and Amos, who are married filing jointly, have one dependent and do not itemize deductions. They have taxable income of $82,000 and tax preferences of $53,000 in 2012. What is their AMT base for 2012?
(Multiple Choice)
4.9/5 (80)
(80) The AMT adjustment for mining exploration and development costs can be avoided if the taxpayer elects to write off the expenditures in the year incurred for regular income tax purposes, rather than writing off the expenditures over a 10-year period for regular income tax purposes.
(True/False)
4.9/5 (70)
(70) Julia's tentative AMT is $94,000. Her regular income tax liability is $72,000. Julia's AMT is $22,000.
(True/False)
4.9/5 (74)
(74) Vicki owns and operates a news agency (as a sole proprietorship). During 2012, she incurred expenses of $24,000 to increase circulation of newspapers and magazines that her agency distributes. For regular income tax purposes, she elected to expense the $24,000 in 2012. In addition, Vicki incurred $15,000 in circulation expenditures in 2013 and again elected expense treatment.What AMT adjustments will be required in 2012 and 2013 as a result of the circulation expenditures?
(Multiple Choice)
4.8/5 (70)
(70) If Jessica exercises an ISO and disposes of the option in the same tax year, are any AMT adjustments required?
(Essay)
4.9/5 (63)
(63) Lavender, Inc., incurs research and experimental expenditures of $210,000 in 2012.Determine the amount of the AMT adjustment for 2012 and for 2013 if for regular income tax purposes:
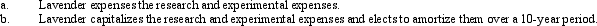
(Essay)
4.7/5 (78)
(78) Factors that can cause the adjusted basis for AMT purposes to be different from the adjusted basis for regular income tax purposes include the following:
(Multiple Choice)
4.8/5 (80)
(80) Because passive losses are not deductible in computing either taxable income or AMTI, no adjustment for passive losses is required for AMT purposes.
(True/False)
5.0/5 (92)
(92) Certain adjustments apply in calculating the corporate AMT that do not apply in calculating the noncorporate AMT and certain adjustments apply in calculating the noncorporate AMT that do not apply in calculating the corporate AMT.
(True/False)
4.8/5 (83)
(83) Discuss the tax year in which an AMT adjustment is first required for an ISO.
(Essay)
4.8/5 (79)
(79) Which of the following normally produces positive AMT adjustments?
(Multiple Choice)
4.7/5 (83)
(83) 
A tax preference can increase or decrease alternative minimum taxable income while an adjustment can only increase alternative minimum taxable income.
(True/False)
4.9/5 (85)
(85) Which of the following itemized deductions definitely will be the same amount for the regular income tax and the AMT and thus result in no AMT adjustment in 2012?
(Multiple Choice)
4.7/5 (95)
(95) The net capital gain included in an individual taxpayer's AMT base is eligible for the alternative tax rate on net capital gain. This favorable alternative rate applies both in calculating the regular income tax and the AMT.
(True/False)
4.8/5 (90)
(90) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)