



 Chat with AI
Exam 21: Partnerships

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: A: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


If the partnership properly makes an election for treatment of a specific tax item, the partner is bound by that treatment.

Free
(True/False)
4.8/5  (89)
(89) Correct Answer: Verified
True
Which of the following statements is always true regarding accounting methods available to a partnership?
Free
(Multiple Choice)
4.7/5 (72)
(72) Correct Answer:Verified
VerifiedB
Dan receives a proportionate nonliquidating distribution when the basis of his partnership interest is $30,000.The distribution consists of $10,000 in cash and property with an adjusted basis to the partnership of $24,000 and a fair market value of $26,500.Dan's basis in the noncash property is:
Free
(Multiple Choice)
4.8/5 (88)
(88) Correct Answer:Verified
VerifiedC
Tim, Al, and Pat contributed assets to form the equal TAP Partnership.Tim contributed cash of $40,000 and land with a basis of $80,000 (fair market value of $60,000).Al contributed cash of $60,000 and land with a basis of $50,000 (fair market value of $40,000).Pat contributed cash of $60,000 and a fully depreciated property ($0 basis) valued at $40,000.Which of the following tax treatments is not correct?
(Multiple Choice)
4.8/5 (78)
(78) Tyler's basis in his partnership interest is $110,000, including his share of partnership debt.Sarah buys Tyler's partnership interest for $60,000 cash and she assumes Tyler's $90,000 share of the partnership's debt.If the partnership owns no hot assets, Tyler will recognize a capital loss of $50,000.
(True/False)
5.0/5 (73)
(73) Ashley purchased her partnership interest from Lindsey on the first day of the current year for $40,000 cash.She received a $10,000 cash distribution from the partnership during the year, and her share of partnership income is $15,000.If her share of partnership liabilities on the last day of the partnership year is $20,000, her outside basis for her partnership interest at the end of the year is $65,000.
(True/False)
4.9/5 (88)
(88) During the current tax year, Jordan and Whitney each contributed $50,000 to form the J&W LLC.Each member has a 50% interest in LLC capital, profits, and losses, except that depreciation expense is allocated 40% to Jordan and 60% to Whitney.During the first year, the LLC reported income (before depreciation expense) of $20,000 and had depreciation expense of $10,000.The LLC incurred recourse debt (that was personally guaranteed by both of the LLC members) of $60,000.Partnership assets are $170,000 at the end of the year.Under the constructive liquidation scenario, how is the recourse debt allocated to Jordan and Whitney?
(Multiple Choice)
4.9/5 (75)
(75) Mack has a basis in a partnership interest of $200,000, including his share of partnership debt. At the end of the current year, the partnership distributed to Mack, in a proportionate nonliquidating distribution, cash of $20,000, inventory (basis to the partnership of $30,000 and fair market value of $40,000), and land (basis to the partnership of $40,000 and fair market value of $42,000).In addition, Mack's share of partnership debt decreased by $12,000 during the year. What basis does Mack take in the inventory and land and in the partnership interest (including debt share) following the distribution?
(Multiple Choice)
4.8/5 (77)
(77) Andrew receives a proportionate nonliquidating distribution from the AEF Partnership. The distribution consists of $50,000 cash and property (adjusted basis to the partnership of $34,000 and fair market value of $42,000).Immediately before the distribution, Andrew's adjusted basis in the partnership interest was $40,000.His basis in the noncash property received is:
(Multiple Choice)
5.0/5 (73)
(73) Match each of the following statements with the terms below that provide the best definition.
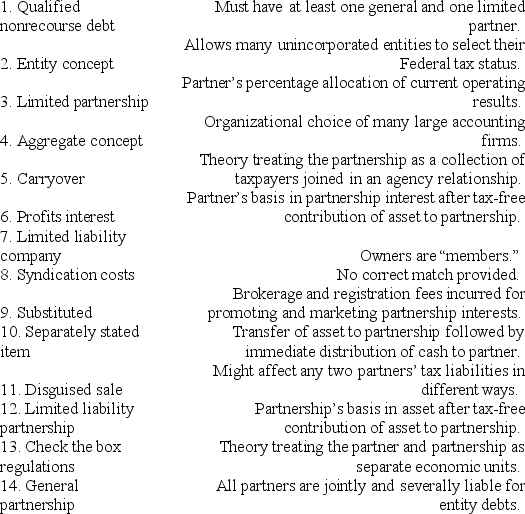
(Essay)
4.8/5 (70)
(70) Aaron owns a 30% interest in a continuing partnership.The partnership distributes a $35,000 year-end cash payment to all the partners.In a proportionate nonliquidating distribution, the partnership also distributed property (basis of $15,000, fair market value of $20,000) to Aaron.Immediately before the distribution, Aaron's basis in the partnership interest was $50,000.As a result of the distribution, Aaron recognizes:
(Multiple Choice)
4.8/5 (82)
(82) Palmer contributes property with a fair market value of $4,000,000 and an adjusted basis of $3,000,000 to AP Partnership.Palmer shares in $1,000,000 of partnership debt under the liability sharing rules, giving him an initial adjusted basis for his partnership interest of $4,000,000.One month after the contribution, Palmer receives a cash distribution from the partnership of $2,000,000.Palmer would not have contributed the property if the partnership had not contractually obligated itself to make the distribution.Assume Palmer's share of partnership liabilities will not change as a result of this distribution.
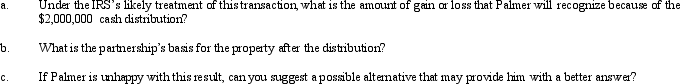
(Essay)
5.0/5 (85)
(85) PaulCo, DavidCo, and Sean form a partnership with cash contributions of $80,000, $50,000 and $30,000, respectively, and agree to share profits and losses in the ratio of their original cash contributions.PaulCo uses a January 31 fiscal year-end, while DavidCo and Sean use a November 30 and December 31 year-end, respectively.The partnership must use the least aggregate deferral method to determine its year end.
(True/False)
4.7/5 (84)
(84) Generally, gain is recognized on a proportionate current or liquidating distribution if the fair market value of property distributed exceeds the partner's basis in the partnership interest.
(True/False)
4.9/5 (77)
(77) Rebecca is a limited partner in the RST Partnership, which is not publicly traded.Her allocable share of RST's passive ordinary losses from a nonrealty activity for the current year is ($60,000).Rebecca has a $40,000 adjusted basis (outside basis) for her interest in RST (before deduction of any of the passive losses).Her amount "at risk" under § 465 is $30,000 (before deduction of any of the passive losses).She also has $25,000 of passive income from other sources.How much of her ($60,000) allocable loss can Rebecca deduct on her current year's tax return?
(Multiple Choice)
5.0/5 (82)
(82) When property is contributed to a partnership for a capital and profits interest, the holding period of the contributing partner's interest:
(Multiple Choice)
4.8/5 (67)
(67) Beth sells her 25% partnership interest to Katie for $50,000 cash on July 1 of the current tax year.Katie also assumed Beth's share of the partnership's liabilities.Beth's basis in her partnership interest at the beginning of the year was $40,000, including a $15,000 share of partnership liabilities.The partnership's income for the entire year was $100,000, and Beth's share of partnership debt was $10,000 as of the date she sold the partnership interest.Assume the partnership has no hot assets and that its income is earned evenly throughout the year.Beth recognizes a gain of $12,500 on the sale.
(True/False)
4.8/5 (78)
(78) Sharon and Sue are equal partners in the S&S Partnership.On January 1 of the current year, each partner's adjusted basis in S&S was $80,000 (including each partner's $20,000 share of the partnership's $40,000 of liabilities).During the current year, S&S repaid $30,000 of the debt and borrowed $20,000 for which Sharon and Sue are equally liable.In the current year ended December 31, S&S also sustained a net operating loss of $40,000 and earned $10,000 of interest income from investments.If liabilities are shared equally by the partners, on January 1 of the next year how much is each partner's basis in her interest in S&S?
(Essay)
4.9/5 (69)
(69) Zach's partnership interest basis is $80,000.Zach receives a proportionate, liquidating distribution from a liquidating partnership of $60,000 cash and inventory having a basis of $30,000 to the partnership and a fair market value of $26,000.Zach assigns a basis of $20,000 to the inventory and recognizes no gain or loss.
(True/False)
4.8/5 (69)
(69) At the beginning of the year, Elsie's basis in the E&G Partnership interest is $90,000.She receives a proportionate nonliquidating distribution from the partnership consisting of $10,000 of cash, unrealized accounts receivable (basis of $0, fair market value $40,000), and land (basis of $30,000, fair market value of $50,000).After the distribution, Elsie's bases in the accounts receivable, land, and partnership interest are:
(Multiple Choice)
4.9/5 (79)
(79) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)