



 Chat with AI
Exam 21: Partnerships

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: A: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


An examination of the RB Partnership's tax books provides the following information for the current year:
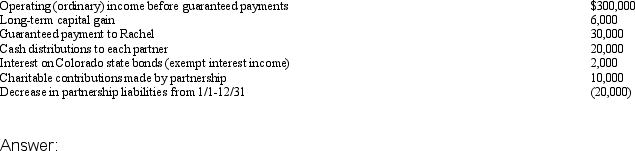 Rachel is a 30% partner in partnership capital, profits, and losses.Assume the adjusted basis of her partnership interest is $60,000 at the beginning of the year, and she shares in 30% of the partnership's liabilities for basis purposes.
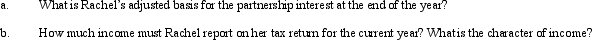
Rachel is a 30% partner in partnership capital, profits, and losses.Assume the adjusted basis of her partnership interest is $60,000 at the beginning of the year, and she shares in 30% of the partnership's liabilities for basis purposes.
(Essay)
4.8/5  (75)
(75) Meagan is a 40% general partner in the calendar year, cash basis MKK Partnership.The partnership received $100,000 income from services and paid the following other amounts:
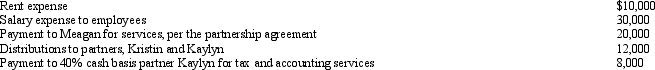 How much will Meagan's adjusted gross income increase as a result of the above items?
 (Essay)
4.8/5 (81)
(81) JLK Partnership incurred $15,000 of organizational costs and $75,000 of startup costs in 2012.JKL may deduct $5,000 each of organizational and startup costs, and the remaining costs ($10,000 of organizational costs and $70,000 of startup costs) may be amortized over 180 months.
(True/False)
4.9/5 (75)
(75) Marcie is a 40% member of the M&A LLC.Her basis is $10,000 immediately before the LLC distributes to her $30,000 of cash and land (basis to the LLC of $20,000 and fair market value of $25,000).As a result of the proportionate, nonliquidating distribution, Marcie recognizes a gain of $20,000 and her basis in the land is $0.
(True/False)
4.7/5 (74)
(74) The MOG Partnership reports ordinary income of $60,000, long-term capital gain of $12,000, and tax-exempt income of $12,000.The partnership agreement provides that Molly will receive all long-term capital gains and George will receive all tax-exempt interest income.Their allocation of ordinary income will be reduced accordingly, and Olivia will be allocated a proportionately greater share of ordinary income.(In other words, each partner will receive allocations totaling 1/3 of the total $84,000 of partnership income.) This allocation was agreed upon because Molly and George are in a high marginal tax bracket and Olivia is in a low marginal tax bracket.

(Essay)
4.8/5 (77)
(77) Mark and Addison formed a partnership.Mark received a 25% interest in partnership capital and profits in exchange for land with a basis of $40,000 and a fair market value of $60,000.Addison received a 75% interest in partnership capital and profits in exchange for $180,000 of cash.Three years after the contribution date, the land contributed by Mark is sold by the partnership to a third party for $76,000.How much taxable gain will Mark recognize from the sale?
(Multiple Choice)
5.0/5 (79)
(79) A partnership will take a carryover basis in an asset it acquires when:
(Multiple Choice)
4.9/5 (76)
(76) ABC, LLC is equally-owned by three corporations.Two corporations have June 30 fiscal year ends, the third is a calendar-year taxpayer.ABC will use a June 30 year end under the majority partners' tax year rule because more than 50% of the partnership's capital and profits is owned by partners with the same taxable year.
(True/False)
4.9/5 (78)
(78) In which of the following independent situations would the transaction most likely be characterized as a disguised sale?
(Multiple Choice)
4.8/5 (62)
(62) Which of the following would be currently taxable as ordinary income to the service partner if received in exchange for services performed for the partnership? (In all cases, assume the interest is not sold within two years after the time it is granted to the service partner.)
(Multiple Choice)
4.8/5 (83)
(83) Jonathon owns a one-third interest in a liquidating partnership.Immediately before the liquidation, Jonathon's basis in the partnership interest is $60,000.The partnership distributes cash of $32,000 and two parcels of land (each with a fair market value of $10,000).Parcel A has a basis of $2,000 to the partnership and Parcel B has a basis of $6,000.Jonathon's basis in the two parcels of land is:
(Multiple Choice)
4.7/5 (74)
(74) A partnership cannot use the cash method of accounting if one of the partners is a C corporation.
(True/False)
4.8/5 (79)
(79) Hannah sells her 25% interest in the HIJK Partnership to Alyssa for $120,000 cash.At the end of the year prior to the sale, Hannah's basis in HIJK was $70,000.The partnership allocates $15,000 of income to Hannah for the portion of the year she was a partner.On the date of the sale, the partnership assets and the agreed fair market values were as follows.
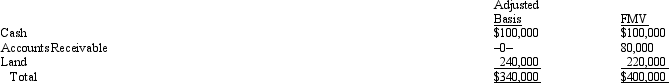 Determine the amount and character of any gain that Hannah recognizes on the sale.
 (Essay)
4.8/5 (64)
(64) Beth has an outside basis of $100,000 in the BBDE Partnership as of December 31 of the current year.On that date the partnership liquidates and distributes to Beth a proportionate distribution of $50,000 cash and inventory with an inside basis to the partnership of $10,000 and a fair market value of $16,000.In addition, Beth receives a computer (not inventory) which has an inside basis and fair market value of $0 and $3,000, respectively.None of the distribution is for partnership goodwill.How much gain or loss will Beth recognize on the distribution, and what basis will she take in the computer?
(Multiple Choice)
4.8/5 (89)
(89) Morgan and Kristen formed an equal partnership on August 1 of the current year.Morgan contributed $60,000 cash and land with a basis of $18,000 and a fair market value of $40,000.Kristen contributed equipment with a basis of $42,000 and a value of $100,000.Kristen and Morgan each have a basis of $100,000 in their partnership interests.
(True/False)
4.8/5 (89)
(89) Nicholas, a 1/3 partner with a basis in the interest of $80,000 at the beginning of the year, received a guaranteed payment in the current year of $50,000.Partnership income before consideration of the guaranteed payment was $20,000.Nicholas must report a $10,000 ordinary loss from partnership operations, and the $50,000 guaranteed payment as ordinary income.
(True/False)
4.7/5 (74)
(74) Carlos receives a proportionate liquidating distribution consisting of $8,000 cash and inventory with a basis to the partnership of $5,000 and a fair market value of $6,000.His basis in his partnership interest was $15,000 immediately before the distribution.Carlos assigns a basis of $5,000 to the inventory, and recognizes a $2,000 capital loss.
(True/False)
4.8/5 (70)
(70) One of the disadvantages of the partnership form is that the partner's share of the partnership's taxable income is taxed to the partner, regardless of whether or not distributed.
(True/False)
4.7/5 (82)
(82) TEC Partners was formed during the current tax year.It incurred $10,000 of organizational expenses, $80,000 of startup expenses, and $5,000 of transfer taxes to retitle property contributed by a partner.The property had been held as MACRS property for ten years by the contributing partner, and had an adjusted basis to the partner of $300,000 and fair market value of $400,000. Which of the following statements is correct regarding these items?
(Multiple Choice)
4.8/5 (81)
(81) Rick is a 30% partner in the ROC Partnership.At the beginning of the tax year, Rick's basis in the partnership interest was $60,000, including his share of partnership liabilities.During the current year, ROC reported net ordinary income of $40,000.In addition, ROC distributed $5,000 to each of the partners ($15,000 total).At the end of the year, Rick's share of partnership liabilities increased by $20,000.Rick's basis in the partnership interest at the end of the year is:
(Multiple Choice)
4.8/5 (76)
(76) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)