



 Chat with AI
Exam 21: Partnerships

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: A: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


The primary purpose of the partnership agreement is to document the various tax elections made by the partners regarding depreciation methods, treatment of research and experimental costs, calculation of the § 199 deduction, and the § 754 election.
(True/False)
4.9/5  (79)
(79) At the beginning of the tax year, Zach's basis for his partnership interest and his amount at risk in the partnership was $30,000. His share of partnership items for the year consisted of tax-exempt interest income of $2,000 and an ordinary loss of $44,000. He also received a distribution from the partnership of $20,000 cash during the year. For the tax year, Zach will report:
(Multiple Choice)
4.8/5 (85)
(85) In a proportionate nonliquidating distribution, cash is deemed to be distributed first, followed by unrealized receivables and inventory and, last, capital and other assets.
(True/False)
4.8/5 (74)
(74) Which of the following is an election or calculation made by the partner rather than the partnership?
(Multiple Choice)
4.9/5 (75)
(75) In a limited liability partnership, all partners are protected from all debts of the partnership.
(True/False)
5.0/5 (81)
(81) Randi owns a 40% interest in the capital and profits of the RAY Partnership.Immediately before she receives a proportionate nonliquidating distribution from RAY, the basis for her partnership interest is $60,000.The distribution consists of $45,000 in cash and land with a fair market value of $72,000.RAY's adjusted basis in the land immediately before the distribution is $36,000.As a result of the distribution, Randi recognizes a gain of $21,000.
(True/False)
4.9/5 (92)
(92) The "outside basis" is defined as a partner's basis in the partnership interest.
(True/False)
4.8/5 (76)
(76) Landon received $50,000 cash and a capital asset (basis of $70,000, fair market value of $80,000) in a proportionate liquidating distribution.His basis in his partnership interest was $100,000 prior to the distribution.How much gain or loss does Landon recognize and what is his basis in the asset received?
(Multiple Choice)
4.8/5 (82)
(82) Tara and Robert formed the TR Partnership four years ago.Because they decided the company needed some expertise in multimedia presentations, they offered Katie a 1/3 interest in partnership capital if she would come to work for the partnership.She will also receive a 25% interest in future partnership profits.On July 1 of the current year, the unrestricted partnership capital interest (fair market value of $25,000) was transferred to Katie.How should Katie treat the receipt of the partnership interest in the current year?
(Multiple Choice)
4.8/5 (72)
(72) Which of the following partnership owners is personally liable for the entity's debts to general creditors?
(Multiple Choice)
4.8/5 (72)
(72) Which of the following is a correct definition of a concept related to partnership taxation?
(Multiple Choice)
4.9/5 (83)
(83) If a partnership allocates losses to the partners, the partners must first apply the passive loss limitations, then the basis limitation, and finally the at-risk limitations.If all three hurdles are met, the partner may deduct the loss.
(True/False)
5.0/5 (75)
(75) Megan's basis was $100,000 in the MAR Partnership interest just before she received a proportionate nonliquidating distribution consisting of land held for investment (basis of $80,000, fair market value of $100,000) and inventory (basis of $60,000, fair market value of $50,000).After the distribution, Megan's bases in the land and inventory are, respectively:
(Multiple Choice)
4.9/5 (86)
(86) Jeordie and Kendis created the JK Partnership by contributing $100,000 each.The $200,000 cash was used by the partnership to acquire a depreciable asset.The partnership agreement provides that the partners' capital accounts will be maintained in accordance with Reg.§ 1.704-1(b) (the "economic effect" Regulations) and that any partner with a deficit capital account will be required to restore that capital account when the partner's interest is liquidated.The partnership agreement provides that MACRS will be allocated 20% to Jeordie and 80% to Kendis.All other items of partnership income, gain, loss, deduction, and credit will be allocated equally between the partners.In the first year, MACRS is $40,000 and no other operating transactions occur.The property is sold at the end of the year for $160,000 and the partnership is liquidated immediately thereafter.
To satisfy the economic effect test, how much of the $160,000 cash (from the sale) is allocated each to Jeordie and Kendis?
(Essay)
5.0/5 (92)
(92) The BLM LLC's balance sheet on August 31 of the current year is as follows. 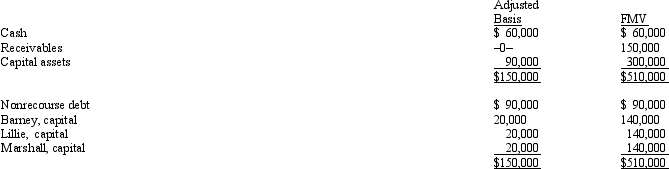 The nonrecourse debt is shared equally among the LLC members.On that date, Lillie sells her one-third interest to Robyn for $170,000, including cash and relief of Lillie's share of the nonrecourse debt.Lillie's outside basis for her interest in the LLC is $50,000, including her share of the LLC's debt.How much capital gain and/or ordinary income will Lillie recognize on the sale?
 (Multiple Choice)
4.9/5 (82)
(82) In the current year, Derek formed an equal partnership with Cody.Derek contributed land with an adjusted basis of $110,000 and a fair market value of $200,000.Derek also contributed $50,000 cash to the partnership.Cody contributed land with an adjusted basis of $80,000 and a fair market value of $230,000.The land contributed by Derek was encumbered by a $60,000 nonrecourse debt.The land contributed by Cody was encumbered by $40,000 of nonrecourse debt.Assume the partners share debt equally.Immediately after the formation, what is the basis of Cody's partnership interest?
(Essay)
4.9/5 (81)
(81) The MOP Partnership is involved in leasing heavy equipment under long-term leases of five years or more.Patricia has an adjusted basis for her partnership interest on January 1 of the current year of $600,000, consisting of the following:
 During the year, the partnership has an operating loss of $1.2 million and distributes $60,000 of cash to Patricia.Partnership liabilities were the same at the end of the tax year, and the nonrecourse debt is not "qualified nonrecourse debt." If she owns a 60% share of partnership profits, capital, and losses, and is a material participant in the partnership, how much of her share of the operating loss can Patricia deduct? What Code provisions could cause a suspension of the loss?
 (Essay)
4.8/5 (68)
(68) Martha receives a proportionate nonliquidating distribution when the basis of her partnership interest is $50,000.The distribution consists of $60,000 cash and noninventory property (adjusted basis to the partnership of $20,000, fair market value of $23,000).How much gain or loss does Martha recognize, and what is her basis in the distributed property and in her partnership interest following the distribution?
(Multiple Choice)
4.8/5 (72)
(72) Section 721 provides that no gain or loss is recognized on a contribution of property to a partnership in exchange for an interest in the partnership.An exception might apply if the taxpayer receives a cash distribution from the partnership soon after the property contribution is made.
(True/False)
4.9/5 (70)
(70) The partnership reports each partner's share of income to the partner in a single amount on Form 1099.
(True/False)
4.9/5 (93)
(93) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)