



 Chat with AI
Exam 21: Partnerships

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: A: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


Allison and Taylor form a partnership by each making contributions of $90,000 cash to partnership capital.The partnership purchases an asset for $600,000, using the cash and financing the rest with a $420,000 recourse note.Allison is allocated 75% of partnership profits and losses until the date when the total partnership profits exceed total partnership losses.After that date, the profits and losses are shared equally between the two partners.The partners expect the partnership to have losses for the first three years of operations and profits thereafter.How will the recourse debt be shared between the partners for basis purposes immediately after the property is acquired?
The recourse debt will be allocated $360,000 to Allison and $60,000 to Taylor.According to the constructive liquidation scenario, the $600,000 partnership asset is deemed worthless.The asset is deemed to be sold for the $0 value and the loss is allocated $450,000 to Allison and $150,000 to Taylor.This reduces Allison's capital account to a deficit of ($360,000) and Taylor's to a deficit of ($60,000).Each partner is then deemed to contribute cash to the partnership to eliminate this capital account deficit (Allison contributes $360,000; Taylor contributes $60,000).The partnership is deemed to use these cash contributions to pay the $420,000 partnership liability.
(Essay)
4.8/5  (78)
(78) The sum of the partner's ending basis on Schedule K-1 equals the total of the partner's ending capital account on Schedule L.
(True/False)
4.8/5 (73)
(73) Which of the following statements is true regarding the sale of a partnership interest?
(Multiple Choice)
4.9/5 (70)
(70) In a proportionate liquidating distribution in which the partnership is liquidated, Marcus received cash of $60,000, inventory (basis of $10,000, fair market value of $12,000), and a capital asset (basis and fair market value of $22,000).Immediately before the distribution, Marcus's basis in the partnership interest was $100,000.
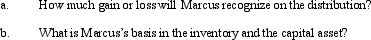
(Essay)
4.9/5 (79)
(79) Section 721 provides that, in general, no gain or loss is recognized by the partnership or the partner on contribution of appreciated or depreciated property to a partnership in exchange for an interest in the partnership.
(True/False)
4.8/5 (74)
(74) In a proportionate liquidating distribution in which the partnership is liquidated, Bill received cash of $120,000, inventory (basis of $6,000, fair market value of $8,000), and a capital asset (basis and fair market value of $16,000).Immediately before the distribution, Bill's basis in the partnership interest was $90,000.
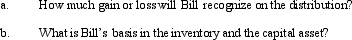
(Essay)
4.8/5 (75)
(75) Julie and Kate form an equal partnership during the current year.Julie contributes cash of $160,000, and Kate contributes property (adjusted basis of $90,000, fair market value of $260,000) subject to a nonrecourse liability of $100,000.As a result of these transactions, Kate has a basis in her partnership interest of $40,000.
(True/False)
4.8/5 (83)
(83) Fern, Inc., Ivy Inc., and Jason formed a general partnership.Fern owns a 50% interest and Ivy and Jason each own 25% interests.Fern, Inc.files its tax return on a July 1 - June 30 fiscal year; Ivy Inc.files on a September 1 - August 31 fiscal year; and Jason is a calendar year taxpayer.Which of the following statements is true regarding the taxable year the partnership can choose?
(Multiple Choice)
4.9/5 (83)
(83) Matt receives a proportionate nonliquidating distribution.At the beginning of the partnership year, the basis of his partnership interest is $60,000.During the year, he received a cash distribution of $25,000 and a property distribution (basis of $20,000, fair market value of $12,000).In addition, Matt's share of partnership liabilities was reduced by $20,000 during the year.How much gain or loss does Matt recognize; what is his basis in the property he received; and what is his remaining basis in the partnership interest?
(Multiple Choice)
4.9/5 (71)
(71) Katherine invested $80,000 this year to purchase a 30% interest in the KLM Partnership.The partnership reported $200,000 of net income from operations, a $2,000 short-term capital loss, and a $10,000 charitable contribution.In addition, the partnership distributed $20,000 to Katherine and $10,000 each to partners Lauren and Missy.Assuming the partnership has no beginning or ending liabilities, what is Katherine's basis in her partnership interest at the end of the year?
(Essay)
4.9/5 (70)
(70) Tom and William are equal partners in the TW Partnership.Just before TW liquidated, Tom's capital account balance was $50,000 and William's capital account balance was $30,000.To meet the substantial economic effect requirements, any liquidating cash distribution must be allocated equally between the partners.
(True/False)
4.9/5 (70)
(70) Which of the following statements correctly reflects the rules regarding proportionate liquidating distributions?
(Multiple Choice)
4.8/5 (84)
(84) Syndication costs arise when partnership interests are being marketed to investors.These costs are amortized over 180 months.
(True/False)
4.9/5 (85)
(85) Suzy owns a 30% interest in the JSD LLC.In liquidation of the entity, Suzy receives a proportionate distribution of $30,000 cash, inventory (basis of $16,000, fair market value of $18,000), and land (basis of $25,000, fair market value of $30,000).Suzy's basis in the entity immediately before the distribution was $80,000.As a result of the distribution, what is Suzy's basis in the inventory and land, and how much gain or loss does she recognize?
(Multiple Choice)
4.9/5 (74)
(74) Jared owns a 40% interest in the capital and profits of the JAJ Partnership.Immediately before he receives a proportionate nonliquidating distribution from JAJ, the basis of his partnership interest is $60,000.The distribution consists of $40,000 in cash and land with a fair market value of $25,000.JAJ's adjusted basis in the land immediately before the distribution is $30,000.As a result of the distribution, Jared recognizes no gain or loss and his basis in the land is $20,000.
(True/False)
4.8/5 (81)
(81) At the beginning of the year, Heather's "tax basis" capital account balance in the HEP Partnership was $60,000.During the tax year, Heather contributed property with a basis of $10,000 and a fair market value of $30,000.Her share of the partnership's ordinary income and separately stated income and deduction items was $26,000.At the end of the year, the partnership distributed $10,000 of cash to Heather.Also, the partnership allocated $15,000 of recourse debt and $25,000 of nonrecourse debt to Heather.What is Heather's ending capital account balance determined using the "tax basis" method?
(Multiple Choice)
4.8/5 (77)
(77) Nicholas is a 25% owner in the DDBN LLC (a calendar year entity).At the end of the last tax year, Nicholas's basis in his interest was $50,000, including his $20,000 share of LLC liabilities.On July 1 of the current tax year, Nicholas sells his LLC interest to Anna for $80,000 cash.In addition, Anna assumes Nicholas's share of LLC liabilities, which, at that date, was $15,000.During the current tax year, DDBN's taxable income is $120,000 (earned evenly during the year).Nicholas's share of the LLC's unrealized receivables is valued at $6,000 ($0 basis).At the sale date, what is Nicholas's basis in his LLC interest, how much gain or loss must he recognize, and what is the character of the gain or loss?
(Multiple Choice)
4.9/5 (76)
(76) Catherine's basis was $50,000 in the CAR Partnership just before she received a proportionate nonliquidating distribution consisting of land held for investment with a basis to CAR of $40,000 (value of $60,000), and inventory with a basis of $40,000 (value of $40,000).After the distribution, Catherine's bases in the land and inventory are:
(Multiple Choice)
4.9/5 (72)
(72) Which of the following is not a correct statement regarding the advantage of the partnership entity form over the subchapter C corporate form?
(Multiple Choice)
4.7/5 (86)
(86) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)