



 Chat with AI
Exam 6: Deductions and Losses: in General

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: A: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


Are there any exceptions to the rule that personal expenditures cannot be deducted?

Free
(Essay)
4.9/5  (73)
(73) Correct Answer: Verified
Generally personal expenditures cannot be deducted.However, the Code provides that for a personal expenditure to be deductible the taxpayer must be able to identify a particular section of the Code that permits the deduction (e.g., charitable contributions, medical expenses, certain taxes, certain interest).
Arnold and Beth file a joint return.Use the following data to calculate their deduction for AGI.
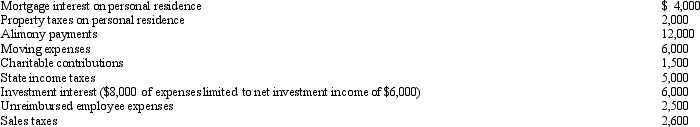
Free
(Essay)
4.8/5 (82)
(82) Correct Answer:Verified
VerifiedArnold and Beth's deduction for AGI is $18,000 and consists of the following items:
 All of the other items are itemized deductions.Note that the taxpayer must choose between the state income taxes and the sales taxes.
Larry, a calendar year cash basis taxpayer, has the following transactions: 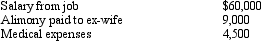 Based on this information, Larry has:
Free
(Multiple Choice)
4.9/5 (73)
(73) Correct Answer:Verified
VerifiedB
For purposes of the § 267 loss disallowance provision, a taxpayer's aunt is a related party.
(True/False)
4.9/5 (83)
(83) Salaries are considered an ordinary and necessary expense of a trade or business if they meet what other requirement? What are the tax consequences if this requirement is not met?
(Essay)
4.7/5 (93)
(93) Because it has only one owner, any sole proprietorship is permitted to elect the cash method of accounting.
(True/False)
4.7/5 (87)
(87) Generally, a closely-held family corporation is not permitted to take a deduction for a salary paid to a family member in calculating corporate taxable income.
(True/False)
4.8/5 (87)
(87) Janet is the CEO for Silver, Inc., a closely held corporation. Her total compensation for 2012 is $5 million. Of this amount, $2 million is a salary and $3 million is a bonus. The bonus was calculated as 5% of Silver's net income before the bonus and before taxes ($60 million X 5% = $3 million). The bonus provision has been in effect since Janet became CEO five years ago and is related to Silver's performance.It is approved annually by the entire board of directors (1 of the 5 directors is an outside director) of Silver. How much of Janet's compensation can Silver deduct for 2012?
(Essay)
5.0/5 (93)
(93) Priscella pursued a hobby of making bedspreads in her spare time.Her AGI before considering the hobby is $40,000.During the year she sold the bedspreads for $10,000.She incurred expenses as follows:  Assuming that the activity is deemed a hobby, how should she report these items on her tax return?
 (Multiple Choice)
4.8/5 (85)
(85) Which of the following can be claimed as a deduction for AGI?
(Multiple Choice)
4.8/5 (73)
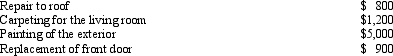
(73) 

In a related party transaction where realized loss is disallowed, when can the disallowed loss be used by the buyer on the subsequent sale of the property? In the case of a related party disallowed loss transaction, can the related party seller's disallowed loss be used by a taxpayer other than the related party buyer?
(Essay)
4.8/5 (88)
(88) If a vacation home is a personal/rental residence, no maintenance and utility expenses can be claimed as a deduction.
(True/False)
4.9/5 (79)
(79) Assuming an activity is deemed to be a hobby, discuss the order and limits in which expenses must be deducted.
(Essay)
4.9/5 (71)
(71) On January 2, 2012, Fran acquires a business from Chuck.Among the assets purchased are the following intangibles: patent with a 7-year remaining life, a covenant not to compete for 10 years, and goodwill. Of the purchase price, $140,000 was paid for the patent and $60,000 for the covenant.The amount of the excess of the purchase price over the identifiable assets was $100,000.What is the amount of the amortization deduction for 2012?
(Multiple Choice)
4.9/5 (82)
(82) Iris, a calendar year cash basis taxpayer, owns and operates several TV rental outlets in Florida, and wants to expand to other states.During 2012, she spends $14,000 to investigate TV rental stores in South Carolina and $9,000 to investigate TV rental stores in Georgia.She acquires the South Carolina operations, but not the outlets in Georgia.As to these expenses, Iris should:
(Multiple Choice)
4.7/5 (84)
(84) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)