



 Chat with AI
Exam 22: S: Corporations

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: A: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


On January 2, 2011, David loans his S corporation $10,000, and by the end of 2011 David's stock basis is zero and the basis in his note has been reduced to $8,000.During 2012, the company's operating income is $10,000.The company also makes distributions to David of $11,000.David reports a(n):
(Multiple Choice)
4.8/5  (81)
(81) Any losses that are suspended under the at-risk rules are carried forward and are available during an S corporation's post-termination period.
(True/False)
4.9/5 (96)
(96) A distribution of cash or other property by an S corporation to shareholders that does not exceed the balance of AAA during a one-year period following an S election termination receives special capital gain treatment.
(True/False)
4.8/5 (80)
(80) Outline the requirements that an entity must meet to elect S corporation status.
(Essay)
4.8/5 (79)
(79) Bidden, Inc., a calendar year S corporation, incurred the following items.
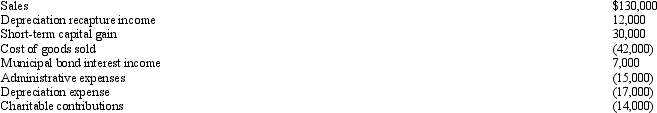 Calculate Bidden's nonseparately computed income.
 (Essay)
4.8/5 (76)
(76) Which transaction affects the Other Adjustments Account on an S corporation's Schedule M-2?
(Multiple Choice)
4.8/5 (71)
(71) For Federal income tax purposes, taxation of S corporations resembles that of partnerships.
(True/False)
4.8/5 (73)
(73) Pepper, Inc., an S corporation, reports sales revenues of $400,000, taxable interest of $380,000, operating expenses of $250,000, and deductions attributable to the interest income of $140,000.What is Pepper's passive income penalty tax payable, if any?
(Multiple Choice)
4.7/5 (83)
(83) As a general rule, where the S corporation provisions are silent, ____________________ rules apply.
(Short Answer)
4.8/5 (66)
(66) Rents always are considered to be passive investment income in S status.
(True/False)
4.8/5 (72)
(72) An S shareholder's stock basis is reduced by flow-through losses before accounting for distributions.
(True/False)
4.8/5 (70)
(70) Ryan is the sole shareholder of Sweetwater Apartments, an S corporation in Sour Lake, Texas.At a time when his stock basis is $10,000, the corporation distributes appreciated property worth $100,000 (basis of $10,000).There is no built-in gain.Ryan's taxable gain is:
(Multiple Choice)
4.8/5 (87)
(87) To make a valid S election, the entity must file a properly completed Form ____________________.
(Short Answer)
4.7/5 (92)
(92) An S corporation shareholder's basis includes his or her direct investments plus a ratable share of any corporate liabilities.
(True/False)
4.9/5 (90)
(90) Which, if any, of the following can be an eligible shareholder of an S corporation?
(Multiple Choice)
4.9/5 (83)
(83) Discuss the two methods of allocating tax-related items to S corporation shareholders.
(Essay)
4.8/5 (76)
(76) The LIFO recapture tax is a variation of the passive investment income penalty tax.
(True/False)
4.9/5 (76)
(76) Meeting the definition of a small business corporation is a ____________________ requirement for maintaining the S status.
(Short Answer)
5.0/5 (74)
(74) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)