



 Chat with AI
Exam 22: S: Corporations

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: A: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


An S shareholder's basis is not decreased by distributions treated as being paid from AAA.
(True/False)
4.7/5  (68)
(68) An S corporation does not recognize a loss when distributing assets that are worth less than their basis.
(True/False)
4.9/5 (78)
(78) There is no limit on the amount of passive investment income that an S corporation can earn during the year.
(True/False)
4.8/5 (76)
(76) Which of these tax provisions does not apply to an S corporation?
(Multiple Choice)
4.8/5 (78)
(78) It is not beneficial for an S corporation to issue § 1244 stock.
(True/False)
4.9/5 (72)
(72) If an S corporation shareholder's basis in a loan to the entity has been _________________, the shareholder recognizes gross income when the S corporation repays the shareholder.
(Short Answer)
4.8/5 (69)
(69) Estela, Inc., a calendar year S corporation, incurred the following items in 2012.
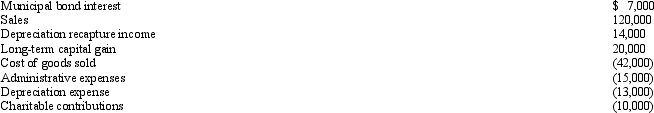 Calculate Estela's nonseparately computed income.
 (Essay)
4.8/5 (86)
(86) If an S corporation excludes cancellation of debt (COD) income from gross income, the excluded amount is applied to _________________ S corporation tax attributes.
(Short Answer)
4.7/5 (75)
(75) A per-day, per-share allocation of flow-through S corporation items must be used, unless the shareholder disposes of the entire interest in the entity.
(True/False)
4.8/5 (75)
(75) A calendar year C corporation reports a $41,000 NOL in 2011, but it elects S status for 2012 and generates an NOL of $30,000 in that year. At all times during 2012, the stock of the corporation was owned by the same 10 shareholders, each of whom owned 10% of the stock. Kris, one of the 10 shareholders, holds an S stock basis of $2,300 at the beginning of 2012. How much of the 2012 loss, if any, is deductible by Kris?
(Multiple Choice)
4.9/5 (80)
(80) Which statement is correct with respect to an S corporation?
(Multiple Choice)
4.8/5 (86)
(86) Passive investment income includes net capital gains from the sale of stocks and securities.
(True/False)
5.0/5 (88)
(88) If an S corporation has C corporate E & P and passive income in excess of ____________________ % of its gross receipts for ____________________ consecutive taxable years, the S election is terminated at the beginning of the ____________________ year.
or
or
(Short Answer)
4.7/5 (80)
(80) Four unrelated individuals acquire assets on behalf of Jump Corporation on May 21, 2012, purchased assets on June 5, 2012, and begin doing business on June 15, 2012.They subscribe to shares of stock, file articles of incorporation for Jump, and become shareholders on July 23, 2012.The S election must be filed no later than 2 1/2 months after:
(Multiple Choice)
4.8/5 (92)
(92) The passive loss limitations apply at the S corporation shareholder level.
(True/False)
4.7/5 (70)
(70) An S corporation that has total assets of at least $7.5 million on Schedule L at the end of the tax year must file a Schedule M-3.
(True/False)
4.8/5 (91)
(91) Samantha owned 1,000 shares in Evita, Inc., an S corporation, that uses the calendar year. On October 11, 2012, Samantha sells all of her Evita stock. Her basis at the beginning of 2012 was $60,000. Her share of the corporate income for 2012 was $22,000, and she receives a distribution of $35,000 between January 1 and October 11, 2012. Her stock basis at the time of the sale is:
(Multiple Choice)
4.9/5 (73)
(73) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)