



 Chat with AI
Exam 22: S: Corporations

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: A: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


Advise your client how income, expenses, gain, and losses are allocated to shareholders of an S corporation.
(Essay)
4.8/5  (85)
(85) An S corporation with substantial AEP has operating revenues of $410,000, taxable interest income of $390,000, operating expenses of $260,000, and deductions attributable to the interest of $150,000.The passive income penalty tax payable, if any, is:
(Multiple Choice)
4.9/5 (71)
(71) When loss assets are distributed by an S corporation, a shareholder's basis is equal to the asset's fair market value.
(True/False)
4.9/5 (85)
(85) You are given the following facts about a one-shareholder S corporation. Prepare the shareholder's ending stock basis. 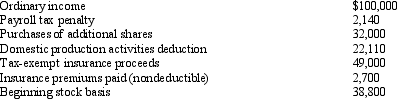
(Multiple Choice)
4.7/5 (71)
(71) Tax-exempt income is listed on Schedule ____________________ of Form 1120S.
(Short Answer)
4.9/5 (82)
(82) The Schedule M-3 is the same for a C corporation and an S corporation.
(True/False)
4.8/5 (80)
(80) Which equity arrangement cannot be used by an S corporation?
(Multiple Choice)
4.8/5 (73)
(73) In the case of a complete termination of an S corporation interest, a ____________________ tax year may occur.
(Short Answer)
4.8/5 (82)
(82) Yates Corporation elects S status, effective for calendar year 2012.Yates' only asset has a basis of $50,200 and a fair market value of $110,400 as of January 1, 2012.The asset is sold at the end of 2012 for $130,800.What amount must Mark Farris, a 60% owner and subject to a 15% income tax rate, pay, if any?
(Multiple Choice)
4.8/5 (64)
(64) The carryover period for the NOLs of a C corporation continues to run during S corporation years.
(True/False)
4.9/5 (80)
(80) An S corporation can take advantage of the dividends received deduction.
(True/False)
4.8/5 (83)
(83) Towne, Inc., a calendar year S corporation, has an AAA amount of $627,050 at the beginning of 2012. During the year, the following items occur.
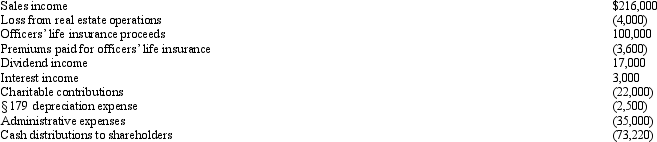 Calculate Towne's ending AAA balance.
 (Essay)
4.9/5 (85)
(85) Compensation for services rendered to an S corporation is subject to FICA taxes.
(True/False)
5.0/5 (72)
(72) Which transaction affects the Other Adjustments Account on an S corporation's Schedule M-2?
(Multiple Choice)
4.7/5 (72)
(72) An S corporation may not have a ____________________ alien shareholder.
(Short Answer)
5.0/5 (79)
(79) Realized gain is recognized by an S corporation on its distribution of ____________________ property.
(Short Answer)
4.9/5 (78)
(78) Compare the distribution of property rules for an S corporation with the corresponding partnership rules.
(Essay)
4.9/5 (79)
(79) S corporation status allows shareholders to realize tax benefits from corporate losses ____________________.
(Short Answer)
4.8/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)