



 Chat with AI
Exam 24: Multistate Corporate Taxation

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: A: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


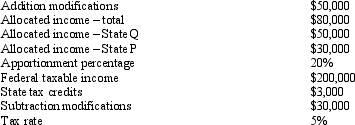

In most states, a limited liability company (LLC) is subject to the state income tax:
(Multiple Choice)
4.9/5  (89)
(89) Most of the U.S.states have adopted an alternative minimum tax, similar to the Federal system.
(True/False)
4.8/5 (99)
(99) Typically exempt from the sales/use tax base is the purchase of clothing from a neighbor's "garage sale."
(True/False)
4.9/5 (76)
(76) Under P.L.86-272, which of the following transactions by itself would create nexus with a state?
(Multiple Choice)
4.7/5 (84)
(84) Hopper Corporation's property holdings in State E are as follows. 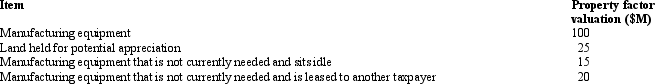 Compute the numerator of Hopper's E property factor.
 (Multiple Choice)
4.7/5 (79)
(79) Determine Bowl's sales factors for States K, M, and N.
Bowl Corporation's manufacturing facility, distribution center, and retail store are located in State K.Bowl sells its products to residents located in States K, M, and N.
Sales to residents of K are conducted through a retail store.Sales to residents of M are obtained by Bowl's sales representative, who has the authority to accept and approve sales orders.Residents of N can purchase Bowl's product only if they place an order online and arrange to take delivery of the product at Bowl's shipping dock.Bowl's sales were as follows.
 Bowl's activities within the three states are limited to those described above.All of the states have adopted a throwback provision and utilize a three-factor apportionment formula under which sales, property, and payroll are equally weighted.K sources dock sales to the destination state.
 (Essay)
4.8/5 (77)
(77) Typically exempt from the sales/use tax base is the purchase of prescription medicines by an individual.
(True/False)
4.9/5 (68)
(68) Provide the required information for Wren Corporation, whose Federal taxable income totals $100 million.Wren apportions 60% of its business income to State
C.Wren generates $10 million of nonbusiness income each year.Forty percent of that income is attributable to rentals of buildings located in
C.Wren's business income this year totals $60 million.
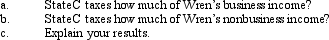
(Essay)
4.8/5 (82)
(82) P.L.86-272 ____________________ (does/does not) create nexus when the seller runs a booth with inventory samples, at a one-week trade show in the state.
(Short Answer)
4.9/5 (83)
(83) The sales/use tax that is employed by most U.S.states does not fall on all retail transactions. Identify at least five sales/use tax exemptions that states often allow, eliminating certain transactions from the tax base.
(Essay)
4.8/5 (90)
(90) A number of court cases in the last several decades have involved the application of a state's nexus rules concerning a business taxpayer. What is the significance of the term nexus when discussing state income taxation?
(Essay)
4.8/5 (70)
(70) Norman Corporation owns and operates two manufacturing facilities, one in State X and the other in State Y.Due to a temporary decline in the corporation's sales, Norman has rented 20% of its Y facility to an unaffiliated corporation.Norman generated $1,000,000 net rental income and $2,000,000 income from manufacturing. Norman is incorporated in Y. For X and Y purposes, rental income is classified as allocable nonbusiness income.By applying the statutes of each state, Norman determined that its apportionment factors are .65 for X and .35 for Y.
Norman's income attributed to X is:
(Multiple Choice)
4.8/5 (81)
(81) Condor Corporation generated $450,000 of state taxable income from selling its product in States A and
B.Both states utilize a three-factor apportionment formula that equally weights sales, property, and payroll.The rates of corporate income tax imposed in A and B are 5% and 3%, respectively.Determine Condor's state income tax liability.
B.For the taxable year, the corporation's activities within the two states were as follows.
 Condor has determined that it is subject to tax in both A and
 (Essay)
5.0/5 (80)
(80) The typical state sales/use tax falls on sales of both real and personal property.
(True/False)
4.9/5 (82)
(82) In the broadest application of the unitary theory, the U.S.unitary business files a combined tax return using factors and income amounts for all affiliates:
(Multiple Choice)
4.9/5 (77)
(77) Britta Corporation's entire operations are located in State A. Eighty percent ($800,000) of Britta's sales are made in A and the remaining sales ($200,000) are made in State B. B has not adopted a corporate income tax. If A has adopted a throwback rule, the numerator of Britta's A sales factor is:
(Multiple Choice)
4.9/5 (79)
(79) Milt Corporation owns and operates two facilities that manufacture paper products.One of the facilities is located in State D, and the other is located in State
E.E does not distinguish between business and nonbusiness property.D apportions business income.Milt's activities within the two states are outlined below.
 Both D and E utilize a three-factor apportionment formula, under which sales, property, and payroll are equally weighted.Determine the amount of Milt's income that is subject to income tax by each state.
E.Milt generated $1,200,000 of taxable income, comprised of $1,000,000 of income from its manufacturing facilities and a $200,000 gain from the sale of nonbusiness property located in
Both D and E utilize a three-factor apportionment formula, under which sales, property, and payroll are equally weighted.Determine the amount of Milt's income that is subject to income tax by each state.
E.Milt generated $1,200,000 of taxable income, comprised of $1,000,000 of income from its manufacturing facilities and a $200,000 gain from the sale of nonbusiness property located in (Essay)
4.9/5 (75)
(75) A service engineer spends 60% of her time maintaining the employer's productive business property and 40% maintaining the employer's nonbusiness rental properties.This year, her compensation totaled $90,000.The payroll factor assigns $54,000 to the state in which the employer is based.
(True/False)
4.9/5 (77)
(77) A state or local tax on a corporation's income might be called a franchise tax or a business privilege tax.
(True/False)
4.9/5 (63)
(63) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)