



 Chat with AI
Exam 24: Multistate Corporate Taxation

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: A: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


The sale of groceries to an individual probably is exempt from sales/use tax under the _________________________ rule.
(Short Answer)
4.7/5  (77)
(77) A unitary business applies a combined apportionment formula, including data from operations of all of the affiliates.
(True/False)
4.9/5 (87)
(87) The individual seller of a used auto should collect and remit sales tax to the state.
(True/False)
5.0/5 (91)
(91) Typically, a sales/use tax is applied to a retail sale of ____________________ property.
(Short Answer)
4.8/5 (76)
(76) In determining taxable income for state income tax purposes, the state NOL deduction typically constitutes a(n) ____________________ modification.
(Short Answer)
4.8/5 (71)
(71) A taxpayer wishing to reduce the negative tax effects of the application of the unitary theory might:
(Multiple Choice)
4.8/5 (99)
(99) A typical state taxable income addition modification is for the Federal income tax paid for the period.
(True/False)
4.7/5 (78)
(78) An assembly worker earns a $30,000 salary and receives a fringe benefit package worth $15,000.The payroll factor assigns $30,000 for this employee.
(True/False)
4.9/5 (76)
(76) Hermann Corporation is based in State A (corporate income tax rate 10%).It sells its goods to customers in both A and State B (corporate income tax rate 4%). Hermann's state taxable income for the year is $1 million, 30% of which relates to B customers. Hermann's level of activities in B is insufficient to create nexus there, but A has adopted a throwback rule as to multistate sales. Would Hermann reduce its total state income tax liability by creating nexus with B, say by allowing its sales force to make credit decisions? Elaborate.
(Essay)
5.0/5 (79)
(79) In conducting multistate tax planning, the taxpayer should:
(Multiple Choice)
4.9/5 (74)
(74) A(n) ____________________ business operates its separate companies as a whole.It cannot be segregated into independently operating divisions or branches.
(Short Answer)
4.8/5 (88)
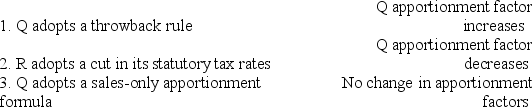
(88) Match each of the following events to its likely effect on WillCo's various apportionment factors. WillCo is based in Q and has customers in Q, R, and S. To this point, WillCo has not established nexus with S.More than one choice may be correct.
(Essay)
4.9/5 (81)
(81) In determining state taxable income, all of the following are adjustments to Federal income except:
(Multiple Choice)
4.9/5 (79)
(79) Almost all of the states assess some form of consumer-level sales/use tax.
(True/False)
4.9/5 (83)
(83) Typical indicators of nexus include the presence of employees based in the state, and the ownership or lease of realty there.
(True/False)
4.8/5 (87)
(87) Parent and Junior form a unitary group of corporations.Parent is located in a state with an effective tax rate of 3%, while Junior's effective tax rate is 9%.Acting in concert to reduce overall tax liabilities, the group should:
(Multiple Choice)
4.9/5 (75)
(75) The property factor includes business assets that the taxpayer owns, but also those merely used under a lease agreement.
(True/False)
4.8/5 (82)
(82) Almost all of the states allow ____________________ treatment to an LLC for income tax purposes.
or
or
(Short Answer)
4.8/5 (93)
(93) An LLC apportions and allocates its annual taxable income in the same manner used by any other business operating in the state.
(True/False)
4.9/5 (79)
(79) José Corporation realized $600,000 taxable income from the sales of its products in States X and Z.José's activities in both states establish nexus for income tax purposes.José's sales, payroll, and property among the states include the following.  X utilizes an equally weighted three-factor apportionment formula.How much of José's taxable income is apportioned to X?
 (Multiple Choice)
4.8/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)