



 Chat with AI
Exam 24: Multistate Corporate Taxation

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: A: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


For most taxpayers, which of the traditional apportionment factors yields the greatest opportunities for tax reduction?
(Multiple Choice)
5.0/5  (91)
(91) You are preparing to make a presentation to a client who has some familiarity with state income tax rules. At a general level, list for the client the principles of multistate tax planning.
(Essay)
4.8/5 (76)
(76) All of the U.S.states use an apportionment formula based on the sales, property, and payroll factors.
(True/False)
4.7/5 (70)
(70) In most states, Federal S corporations must make a separate state-level election of the flow-through status.
(True/False)
5.0/5 (81)
(81) Under the UDITPA's ____________________ concept, sales are assumed to take place at the point of delivery, as opposed to the location at which the shipment originates.
(Short Answer)
4.8/5 (87)
(87) Given the following transactions for the year, determine Comp Corporation's D payroll factor denominator.State D has adopted the principles of UDITPA. 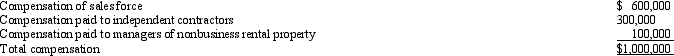
(Multiple Choice)
4.8/5 (83)
(83) Node Corporation is subject to tax only in State X.Node generated the following income and deductions.State income taxes are not deductible for X income tax purposes.
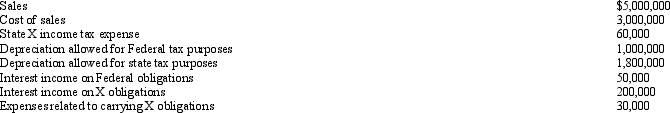
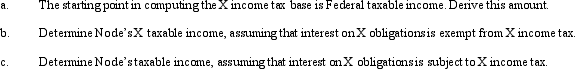
(Essay)
4.8/5 (86)
(86) In most states, medical services are exempt from the sales/use tax base.
(True/False)
4.8/5 (69)
(69) A state wants to increase its income tax collections, but politically it would be unwise to raise taxes on in-state individuals or businesses. Identify some changes to the income tax apportionment formula that would shift the scheduled income tax increases to out-of-state businesses.
(Essay)
4.8/5 (75)
(75) The typical local property tax falls on both an investor's real estate and her stock portfolio.
(True/False)
4.8/5 (81)
(81) Double weighting the sales factor effectively increases the tax burden on taxpayers based in the state, such as corporations with in-state headquarters.
(True/False)
4.9/5 (79)
(79) Although apportionment formulas vary among jurisdictions, most states use the same three factors in the formula.The factors are ____________________, ____________________, and ____________________.
or
or
(Essay)
4.8/5 (76)
(76) Judy, a regional sales manager, has her office in State X.Her region includes several states, as indicated in the sales report below.Determine how much of Judy's $200,000 compensation is assigned to the payroll factor of State X. 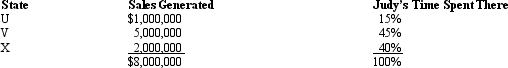
(Multiple Choice)
4.9/5 (79)
(79) In determining taxable income for state income tax purposes, the Federal NOL deduction typically constitutes a(n) ____________________ modification.
(Short Answer)
4.8/5 (72)
(72) Discuss how a multistate business divides up its corporate taxable income among the states in which it operates. Hint: use the terms allocation and apportionment in your comments.
(Essay)
4.8/5 (76)
(76) In some states, an S corporation must withhold Federal income tax for its shareholders who ____________________ (are/are not) state residents.
(Short Answer)
4.9/5 (86)
(86) Typically included in the sales/use tax base is the purchase of computer and cell phone equipment by a large consulting firm that is incorporated in the state.
(True/False)
4.8/5 (78)
(78) Valdez Corporation, a calendar-year taxpayer, owns property in States M and O.Both M and O require that the average value of assets be included in the property factor.M requires that the property be valued at its historical cost, and O requires that the property be included in the property factor at its net depreciated book value. 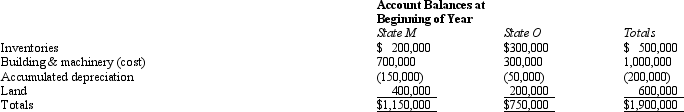
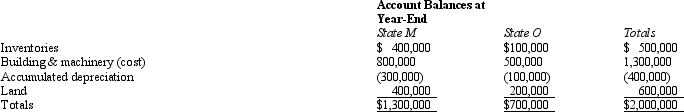 Valdez's O property factor is:
 (Multiple Choice)
4.8/5 (95)
(95) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)