



 Chat with AI
Exam 26: Tax Practice and Ethics

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: A: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


Jenny prepared Steve's income tax returns for no compensation for 2009 and 2010.Jenny is Steve's mother.In 2012, the IRS notifies Steve that it will audit his returns for 2008-2010.Jenny cannot represent Steve during the audit of the returns, as she is not a "registered tax return preparer."
(True/False)
4.9/5  (93)
(93) Loren Ltd., a calendar year taxpayer, had the following transactions, all of which were properly reported on a timely filed return.Presuming the absence of fraud, how much of an omission from gross income must occur for Loren before the six-year statute of limitations applies? Show your computations.
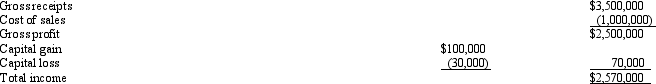
(Essay)
4.7/5 (66)
(66) Yang, a calendar year taxpayer, did not file a tax return for 2005 because she honestly believed that no additional tax was due.In 2012, Yang is audited by the IRS and the agent assesses a deficiency of $17,000 for 2005.Yang need not pay this deficiency, since the statute of limitations expired on April 15, 2009.
(True/False)
4.7/5 (81)
(81) The IRS employs about 100,000 personnel, making it one of the largest Federal agencies.
(True/False)
4.8/5 (80)
(80) The taxpayer can avoid a valuation penalty for overstating the value of the charitable contribution of an artwork by showing that the deduction claimed was based on a qualified ____________________.
(Short Answer)
4.7/5 (73)
(73) When the IRS issues a notice of tax due, the taxpayer has 90 days to either pay the tax or file a petition with the Tax Court.This is conveyed in the "ninety-day letter."
(True/False)
4.9/5 (90)
(90) The usual three-year statute of limitations on additional tax assessments applies in the following situation(s).
(Multiple Choice)
4.8/5 (81)
(81) For purposes of tax penalties, a VITA volunteer is not classified as a tax ____________________.
(Short Answer)
4.9/5 (69)
(69) Certain individuals are more likely than others to have the Form 1040 audited by the IRS. List at least five factors that may increase above the national norms one's chances of audit.
(Essay)
4.7/5 (83)
(83) A CPA, an attorney, and a(n) ____________________ can represent taxpayers before the IRS in an Appeals conference.
(Short Answer)
4.8/5 (81)
(81) The accuracy-related penalties typically relate to ____________________on the part of the taxpayer, or other understatements of tax.
(Short Answer)
4.7/5 (74)
(74) Compute the undervaluation penalty for each of the following independent cases involving the executor's reporting of the value of a closely held business in the decedent's gross estate.In each case, assume a marginal estate tax rate of 45%.
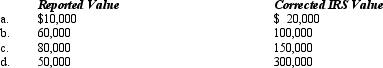
(Essay)
4.9/5 (85)
(85) The Statements on Standards for Tax Services apply to members of the AICPA, a state bar association, and all Enrolled Agents.
(True/False)
4.9/5 (80)
(80) Jake, an individual calendar year taxpayer, incurred the following transactions. 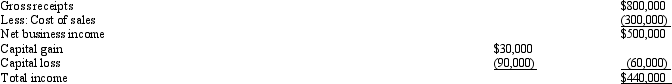 Assuming that any error in timely reporting these amounts was inadvertent, how much omission from gross income would be required before the six-year statute of limitations would apply?
 (Multiple Choice)
4.8/5 (91)
(91) If the taxpayer refuses to pay an assessed tax, the IRS can seize taxpayer property under the ____________________ process.
(Short Answer)
4.8/5 (86)
(86) With respect to the Small Cases Division of the Tax Court,
(Multiple Choice)
4.9/5 (69)
(69) The IRS is a subsidiary agency of the Department of the ____________________.
(Short Answer)
4.8/5 (75)
(75) The taxpayer must pay a significant fee to have a letter ruling issued by the IRS.
(True/False)
4.7/5 (83)
(83) A negligence penalty can be waived if the taxpayer discloses a tax return position that is contrary to a judicial precedent and there is a ____________________ for the taxpayer's position.
(Short Answer)
4.9/5 (79)
(79) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)