



 Chat with AI
Exam 26: Tax Practice and Ethics

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: A: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


Leo underpaid his taxes by $250,000.Portions of the underpayment were attributable to negligence ($90,000) and to civil fraud ($160,000).Compute the total penalties incurred.
(Essay)
4.9/5  (78)
(78) A negligence penalty is assessed when the taxpayer is found to have not made a reasonable attempt to apply with the tax law.
(True/False)
4.9/5 (85)
(85) The IRS can waive the penalty for understating a tax liability if the taxpayer shows ____________________ for the position taken on the tax return.
(Short Answer)
4.8/5 (85)
(85) Minnie, your tax client, has decided to dispute the Revenue Agent's Report.List and discuss at least four of your "next steps" as you prepare to represent Minnie concerning her tax issue within the IRS and in the courts.
(Essay)
4.8/5 (82)
(82) A ____________________% penalty may result when a taxpayer overstates by 150% or more the value of an asset contributed to a charity.
or
(Short Answer)
4.9/5 (81)
(81) Minnie, a calendar year taxpayer, filed a return correctly showing a zero Federal income tax liability for 2011, because her Form 1040 showed various deductions and credits.During 2012, Minnie's AGI is $120,000 and her tax liability is $20,000.To avoid a penalty for 2012, Minnie must make aggregate estimated tax payments of at least:
(Multiple Choice)
4.9/5 (79)
(79) During an audit, IRS personnel might request a(n) ____________________ from the IRS National Office, to clarify the application of tax law concerning a tax deduction.
(Short Answer)
4.9/5 (80)
(80) The AICPA's Statements on Standards for Tax Services must be followed by its members; they are more than merely advisory.
(True/False)
4.9/5 (58)
(58) Roger prepared for compensation a Federal income tax return for Mona.Mona's return included an aggressive interpretation of the rules concerning overnight business travel.Roger is not liable for a preparer penalty for taking an unreasonable tax return position if:
(Multiple Choice)
4.8/5 (77)
(77) Yin-Li is the preparer of the Form 1120 for Cloves Corporation.On the return, Cloves claimed a deduction that the IRS later disallowed on audit.Compute the tax preparer penalty that could be assessed against Yin-Li in each of the following independent situations.
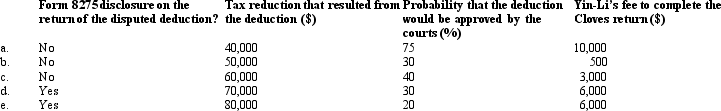
(Essay)
4.9/5 (78)
(78) Megan prepared for compensation a Federal income tax return for Joan.Joan's return included an aggressive interpretation of the rules concerning overnight business travel.Megan is not liable for a preparer penalty for taking an unreasonable tax return position if:
(Multiple Choice)
4.8/5 (86)
(86) If the taxpayer shows ____________________ for an underpayment of tax, the failure to pay penalty can be reduced or eliminated.
(Short Answer)
4.9/5 (73)
(73) A CPA can take a tax return position for a client that is contrary to current IRS interpretations of the law.
(True/False)
4.9/5 (72)
(72) Circular 230 prohibits a tax preparer from charging an unconscionable fee for his/her services.
(True/False)
5.0/5 (80)
(80) According to AICPA rules, the CPA cannot take an aggressive tax return position on the basis of the "audit ____________________."
(Short Answer)
4.8/5 (69)
(69) Which of the following statements correctly reflects the rules governing interest to be paid on an individual's Federal tax deficiency or claim for refund?
(Multiple Choice)
5.0/5 (70)
(70) Evaluate this statement: a taxpayer is liable not only for tax penalties as described in the tax Code and Regulations. Sanctions elsewhere in Federal law, such as in the criminal code, also apply in a tax dispute.
(Essay)
4.9/5 (78)
(78) Vera is audited by the IRS for three tax years.Her returns were prepared by the following parties, to each of whom Vera paid a professional fee. 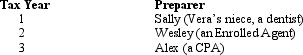 Vera wants help in appearing before the IRS Revenue Agent for the audit. Which of the following statements is correct?
 (Multiple Choice)
4.7/5 (86)
(86) A tax professional needs to know how the IRS is structured and how it works to carry out its mission. Evaluate this statement.
(Essay)
5.0/5 (90)
(90) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)