



 Chat with AI
Exam 26: Tax Practice and Ethics

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: A: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


Harold, a calendar year taxpayer subject to a 35% marginal income tax rate, claimed a Form 1040 charitable contribution deduction of $20,000 for a sculpture that the IRS later valued at $10,000.The applicable overvaluation penalty is:
(Multiple Choice)
4.8/5  (81)
(81) Quon filed an amended return, claiming a $100,000 refund. The IRS disallowed the refund, and it can assess a penalty if there was no reasonable basis of support for the refund claim, in the amount of ____________________% of the disallowed amount.
or
(Short Answer)
5.0/5 (72)
(72) An IRS letter ruling might determine that an employee's compensation is unreasonable in amount.
(True/False)
4.8/5 (71)
(71) IRS computers use document matching programs for both individuals and business taxpayers to keep the audit rate low.
(True/False)
4.9/5 (73)
(73) Does the tax preparer enjoy an "attorney-client privilege" of confidentiality with his or her clients?
(Essay)
5.0/5 (73)
(73) Quon filed his Federal income tax return on time, but he did not remit the full balance due.Compute Quon's failure to pay penalty in each of the following cases.The IRS has not yet issued a deficiency notice.
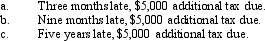
(Essay)
4.9/5 (67)
(67) Maria and Miguel Blanco are in the midst of negotiating a divorce. Because both parties are unwilling to share any current financial information, their joint Form 1040 for 2012 is not filed until October 31, 2013, when the respective divorce attorneys forced them to cooperate. The Blancos should not be subject to any Federal late-filing penalties, because of the reasonable cause exception.
(True/False)
4.7/5 (82)
(82) An "office audit" takes place at the headquarters office of the corporate taxpayer.
(True/False)
4.9/5 (94)
(94) The tax ____________________ workpapers are not privileged communications that can be kept confidential from an IRS subpoena.
(Short Answer)
4.7/5 (76)
(76) The penalty for substantial understatement of tax liability does not apply if:
(Multiple Choice)
4.9/5 (70)
(70) Circular 230 applies to all paid tax practitioners. This includes attorneys, CPAs, and enrolled agents, even though each of the groups has its own code of conduct.
(True/False)
4.8/5 (71)
(71) In connection with the taxpayer penalty for substantial understatement of tax liability, what defenses (if any) are available?
(Essay)
4.8/5 (80)
(80) The Statements on Standards for Tax Services are issued by the:
(Multiple Choice)
4.9/5 (82)
(82) Circular 230 requires that the tax practitioner use the "best practices" of the tax profession in carrying out a tax engagement. Specify what some of these best practices entail.
(Essay)
4.7/5 (84)
(84) Because he undervalued property that he transferred by gift, Dan owes additional gift taxes of $4,000.The penalty for undervaluation does not apply in this situation, because the tax understatement was too small.
(True/False)
4.9/5 (91)
(91) Ron, a calendar year taxpayer subject to a 35% marginal income tax rate, claimed a Form 1040 charitable contribution deduction of $250,000 for a sculpture that the IRS later valued at $150,000.The applicable overvaluation penalty is:
(Multiple Choice)
4.8/5 (83)
(83) Under Circular 230, tax preparer Winston cannot disclose to a mortgage banker the income level of her client Pickett, or other information acquired by preparing the return, without Pickett's permission.
(True/False)
4.9/5 (90)
(90) The IRS can require that the taxpayer produce its financial accounting records, to determine if taxable income is computed correctly.
(True/False)
4.9/5 (80)
(80) Currently, the IRS charges a ____________________% interest rate on taxes that the taxpayer underpays.
or
(Short Answer)
4.9/5 (76)
(76) When a tax issue is taken to court, the burden of proof is on the taxpayer to show that the items reported on the return are correct.
(True/False)
4.8/5 (68)
(68) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)