



 Chat with AI
Exam 15: Revenue Recognition Issues

Exam 1: An Overview of the Australian External Reporting Environment70 Questions
Exam 2: The Conceptual Framework of Accounting and Its Relevance to Financial Reporting72 Questions
Exam 3: Theories of Accounting76 Questions
Exam 4: An Overview of Accounting for Assets77 Questions
Exam 5: Depreciation of Property, plant and Equipment77 Questions
Exam 6: Revaluations and Impairment Testing of Non-Current Assets76 Questions
Exam 7: Inventory75 Questions
Exam 8: Accounting for Intangibles77 Questions
Exam 9: Accounting for Heritage Assets and Biological Assets76 Questions
Exam 10: An Overview of Accounting for Liabilities78 Questions
Exam 11: Accounting for Leases81 Questions
Exam 12: Accounting for Employee Benefits84 Questions
Exam 13: Share Capital and Reserves85 Questions
Exam 14: Accounting for Financial Instruments90 Questions
Exam 15: Revenue Recognition Issues79 Questions
Exam 16: The Statement of Comprehensive Income and Statement of Changes in Equity77 Questions
Exam 17: Accounting for Share-Based Payments77 Questions
Exam 18: Accounting for Income Taxes80 Questions
Exam 19: The Statement of Cash Flows77 Questions
Exam 20: Accounting for the Extractive Industries75 Questions
Exam 21: Accounting for General Insurance Contracts73 Questions
Exam 22: Accounting for Superannuation Plans77 Questions
Exam 23: Events Occurring After the End of the Reporting Period77 Questions
Exam 24: Segment Reporting77 Questions
Exam 25: Related Party Disclosures77 Questions
Exam 26: Earnings Per Share76 Questions
Exam 27: Accounting for Group Structures87 Questions
Exam 28: Further Consolidation Issues I: Accounting for Intragroup Transactions60 Questions
Exam 29: Further Consolidation Issues II: Accounting for Non-Controlling Interests44 Questions
Exam 30: Further Consolidation Issues IV: Accounting for Changes in the Degree of Ownership of a Subsidiary49 Questions
Exam 31: Accounting for Equity Investments,including Investments in Associates and Joint Arrangements70 Questions
Exam 32: Accounting for Foreign Currency Transactions78 Questions
Exam 33: Translating the Financial Statements of Foreign Operations52 Questions
Exam 34: Accounting for Corporate Social Responsibility73 Questions
Select questions type


IASB and FASB initiated a joint project to address some inconsistencies of recognition of revenue in contracts with customers with other accounting standards.Discuss two of these inconsistencies.
(Essay)
4.9/5  (80)
(80) If the borrower prepays interest,the inflow of future economic benefits represented by the prepayment would not constitute an item of revenue to the lender because the lender has a present obligation to the borrower to provide finance for the period to which the prepayment relates.
(True/False)
4.8/5 (76)
(76) The general rule under modified historical-cost accounting is that holding gains on non-current assets should be:
(Multiple Choice)
4.9/5 (83)
(83) Russell Ltd commenced the construction of a bridge on 1July 2013.It has a fixed-price contract for total revenues of $35 million.The expected completion date is 30 June 2016.The expected total cost to Russell Ltd at the beginning of the project is $29 million.The following information relates only to the construction of the bridge: For the year ending 30 June 2014 (\ 000) 2015 (\ 000) 2016 (\ 000) Costs for the year 12000 18000 7000 Costs incurred to date 12000 30000 37000 Estimated costs to complete 19500 6300 - Progress billings during the year 10000 12000 13000 Cash collected during the year 7000 10000 18000 Russell Ltd uses the percentage-of-completion method based on cost to account for its construction contracts.Assuming that the entries for 2014 have been made,what are the journal entries for the year ended 30 June 2015 (rounded to the nearest $000)?
(Multiple Choice)
4.9/5 (88)
(88) The percentage of completion can be measured in a number of ways,including:
(Multiple Choice)
4.9/5 (91)
(91) Bellarine Ltd is publisher of Mode magazine and its customers usually sign a three-year subscription with an advance payment of $500.Mode magazine has 12 issues in a year.What is the appropriate accounting treatment for this sale on the date of signing that is in accordance with IASB (2011)Revenue?
(Multiple Choice)
4.8/5 (68)
(68) Using the cost method to calculate the percentage of completion,the formula for the current period revenue or gross profit to be recognised is:
(Multiple Choice)
4.8/5 (82)
(82) Where the percentage-of-completion method is based on costs,costs that relate to the contract activity generally and are not normally related to specific contracts,such as finance costs,should be allocated across the projects currently in progress.
(True/False)
4.8/5 (97)
(97) Which of the following statements is not in accordance with IASB (2011)Revenue from Contracts with Customers with respect to revenue recognition when right of return exists?
(Multiple Choice)
5.0/5 (86)
(86) In the situation that a debtor becomes unable to pay and the amount has not been anticipated through a provision for doubtful debts,what is the entry to record the bad debt?
(Multiple Choice)
4.8/5 (77)
(77) The following is a diagram of the earnings cycle as presented by Coombes and Martin (1982). 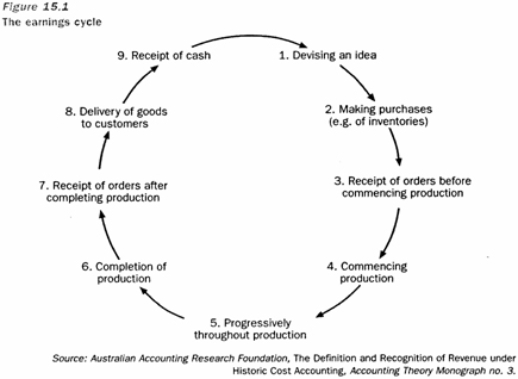 For products such as precious metals or agricultural products revenue is recognised at which point in the earnings cycle shown above?
 (Multiple Choice)
4.7/5 (70)
(70) IASB (2011)specifies the accounting treatment in the case that the outcome of a construction contract cannot be reliably assessed.The treatment specified is:
(Multiple Choice)
4.9/5 (85)
(85) In considering whether to recognise revenue when there are associated options:
(Multiple Choice)
4.9/5 (81)
(81) When goods are sold 'free on board' (f.o.b.)shipping point,the revenue should be recognised when:
(Multiple Choice)
4.9/5 (65)
(65) The percentage-of-completion method that may be used to account for construction contracts can be justified on the basis that:
(Multiple Choice)
4.7/5 (85)
(85) Undersea Construction Ltd commenced the construction of a tunnel under a major river for public transport on 1 July 2014.It has a fixed-price contract for total revenues of $36 million.The expected completion date is 30 June 2017.The expected total cost to Undersea Construction at the beginning of the project is $28 million.The following information relates only to the construction of the tunnel: For the year ending 30 June 2015 (\ 000) 2016 (\ 000) 2017 (\ 000) Costs for the year 5000 15000 10000 Costs incurred to date 5000 20000 30000 Estimated costs to complete 22000 8500 - Progress billings during the year 10000 22000 4000 Cash collected during the year 9000 19000 8000 Undersea Construction uses the percentage-of-completion method based on cost to account for its construction contracts.What is the gross profit to be recognised in each of the 3 years (rounded to the nearest $000)?
(Multiple Choice)
4.8/5 (97)
(97) The following journal entries were recorded by a vendor who sold goods and received promissory notes on 1 July 2012 in exchange. 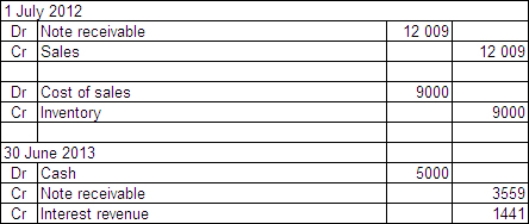 Assuming that the issuer of the promissory notes intends to make three equal payments of $5000 at the end of each of the 3 years,30 June 2013,30 June 2014 and 30 June 2015; what is the amount of interest revenue recorded by the vendor at 30 June 2015?
 (Multiple Choice)
4.9/5 (86)
(86) Explain the difference between revenue and gains as defined in the AASB (IASB)Conceptual Framework.
(Essay)
4.8/5 (81)
(81) What are the three conditions that must be met in order for revenue to be recognised when the sale of a product gives the buyer the right to return the product?
(Short Answer)
4.8/5 (76)
(76) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)