



 Chat with AI
Exam 15: Revenue Recognition Issues

Exam 1: An Overview of the Australian External Reporting Environment70 Questions
Exam 2: The Conceptual Framework of Accounting and Its Relevance to Financial Reporting72 Questions
Exam 3: Theories of Accounting76 Questions
Exam 4: An Overview of Accounting for Assets77 Questions
Exam 5: Depreciation of Property, plant and Equipment77 Questions
Exam 6: Revaluations and Impairment Testing of Non-Current Assets76 Questions
Exam 7: Inventory75 Questions
Exam 8: Accounting for Intangibles77 Questions
Exam 9: Accounting for Heritage Assets and Biological Assets76 Questions
Exam 10: An Overview of Accounting for Liabilities78 Questions
Exam 11: Accounting for Leases81 Questions
Exam 12: Accounting for Employee Benefits84 Questions
Exam 13: Share Capital and Reserves85 Questions
Exam 14: Accounting for Financial Instruments90 Questions
Exam 15: Revenue Recognition Issues79 Questions
Exam 16: The Statement of Comprehensive Income and Statement of Changes in Equity77 Questions
Exam 17: Accounting for Share-Based Payments77 Questions
Exam 18: Accounting for Income Taxes80 Questions
Exam 19: The Statement of Cash Flows77 Questions
Exam 20: Accounting for the Extractive Industries75 Questions
Exam 21: Accounting for General Insurance Contracts73 Questions
Exam 22: Accounting for Superannuation Plans77 Questions
Exam 23: Events Occurring After the End of the Reporting Period77 Questions
Exam 24: Segment Reporting77 Questions
Exam 25: Related Party Disclosures77 Questions
Exam 26: Earnings Per Share76 Questions
Exam 27: Accounting for Group Structures87 Questions
Exam 28: Further Consolidation Issues I: Accounting for Intragroup Transactions60 Questions
Exam 29: Further Consolidation Issues II: Accounting for Non-Controlling Interests44 Questions
Exam 30: Further Consolidation Issues IV: Accounting for Changes in the Degree of Ownership of a Subsidiary49 Questions
Exam 31: Accounting for Equity Investments,including Investments in Associates and Joint Arrangements70 Questions
Exam 32: Accounting for Foreign Currency Transactions78 Questions
Exam 33: Translating the Financial Statements of Foreign Operations52 Questions
Exam 34: Accounting for Corporate Social Responsibility73 Questions
Select questions type


On 1 July 2013 Bigwell Ltd sells a machine to Archer Ltd in exchange for a promissory note that requires Archer Ltd to make five payments of $8000,the first to be made on 30 June 2014.The machine cost Bigwell Ltd $20 000 to manufacture.Bigwell Ltd would normally sell this type of machine for $30 326 for cash or short-term credit.The implicit interest rate in the agreement is 10%.What are the appropriate journal entries to record the sale agreement and the first two instalments using the gross method?
(Multiple Choice)
4.8/5  (90)
(90) When making a provision for doubtful debts,debtors' subsidiary ledgers are not adjusted,as the provision is made in anticipation of likely non-recoverability of amounts owing,although the identity of who will not pay is unknown.
(True/False)
4.9/5 (83)
(83) Transactions that result in an inflow of economic benefits such as the purchase of assets can be classified as a gain.
(True/False)
4.7/5 (83)
(83) Lonsdale Ltd sells mobile phones and provides a one-year warranty.Lonsdale is able to recognise revenue at point-of-sale in accordance with IASB (2011)because:
(Multiple Choice)
5.0/5 (83)
(83) There are various appropriate accounting treatments when a sale is made subject to a right of return.These methods include:
(Multiple Choice)
4.9/5 (85)
(85) Transfer of 'control' of the asset is central to the recognition of revenue under the new accounting standard IASB (2011).
(True/False)
4.8/5 (91)
(91) Accounting standards require that the provision for doubtful debts should be shown as a deduction from the class of assets to which it relates.The net expense in relation to bad and doubtful debts must also be disclosed.
(True/False)
5.0/5 (80)
(80) Gains that result from revaluation of long-term assets are included in income.
(True/False)
4.9/5 (84)
(84) In relation to the expense associated with the creation of an allowance for doubtful debts,the Australian Taxation Office:
(Multiple Choice)
4.9/5 (79)
(79) Unearned revenues are assets treated as liabilities,as these are received by a business for services to be performed at a future date.
(True/False)
4.8/5 (79)
(79) Kringle Company has agreed to provide services to North to South Ltd in exchange for a piece of equipment and a cash payment.The equipment is currently recorded in North to South's books at $73 000 but independent assessors have set the fair value at $65 000.The cash payment of $20 000 will be received 12 months after completion of the services.Kringle should record revenue as:
(Multiple Choice)
5.0/5 (84)
(84) Describe,with examples,how the recognition of revenue,at the time of sale,is affected when products require transportation.
(Essay)
4.8/5 (77)
(77) Which of the following is not a disclosure requirement of IASB (2011)?
(Multiple Choice)
4.8/5 (83)
(83) The following is a diagram of the earnings cycle as presented by Coombes and Martin (1982). 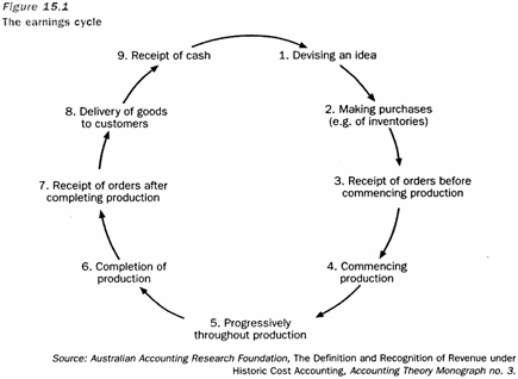 Because of uncertainty and depending on which measurement model is being applied,revenue recognition will take place at a limited number of points in the earnings cycle.In traditional historical-cost accounting,in most cases,at which point in the cycle above have revenues been recognised?
 (Multiple Choice)
4.9/5 (82)
(82) Describe the output and input measures of performance that an entity is required to use when measuring the progress to date on a construction contract.
(Essay)
4.8/5 (88)
(88) In the case of a fixed price contract,AASB 111 specifies four conditions that must all be met in order for the percentage-of-completion method to be applied.These conditions include:
(Multiple Choice)
4.9/5 (74)
(74) With the percentage-of-completion method of accounting for construction contracts,profit is recognised in proportion to the work performed in each reporting period.
(True/False)
4.9/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)