



 Chat with AI
Exam 15: Revenue Recognition Issues

Exam 1: An Overview of the Australian External Reporting Environment70 Questions
Exam 2: The Conceptual Framework of Accounting and Its Relevance to Financial Reporting72 Questions
Exam 3: Theories of Accounting76 Questions
Exam 4: An Overview of Accounting for Assets77 Questions
Exam 5: Depreciation of Property, plant and Equipment77 Questions
Exam 6: Revaluations and Impairment Testing of Non-Current Assets76 Questions
Exam 7: Inventory75 Questions
Exam 8: Accounting for Intangibles77 Questions
Exam 9: Accounting for Heritage Assets and Biological Assets76 Questions
Exam 10: An Overview of Accounting for Liabilities78 Questions
Exam 11: Accounting for Leases81 Questions
Exam 12: Accounting for Employee Benefits84 Questions
Exam 13: Share Capital and Reserves85 Questions
Exam 14: Accounting for Financial Instruments90 Questions
Exam 15: Revenue Recognition Issues79 Questions
Exam 16: The Statement of Comprehensive Income and Statement of Changes in Equity77 Questions
Exam 17: Accounting for Share-Based Payments77 Questions
Exam 18: Accounting for Income Taxes80 Questions
Exam 19: The Statement of Cash Flows77 Questions
Exam 20: Accounting for the Extractive Industries75 Questions
Exam 21: Accounting for General Insurance Contracts73 Questions
Exam 22: Accounting for Superannuation Plans77 Questions
Exam 23: Events Occurring After the End of the Reporting Period77 Questions
Exam 24: Segment Reporting77 Questions
Exam 25: Related Party Disclosures77 Questions
Exam 26: Earnings Per Share76 Questions
Exam 27: Accounting for Group Structures87 Questions
Exam 28: Further Consolidation Issues I: Accounting for Intragroup Transactions60 Questions
Exam 29: Further Consolidation Issues II: Accounting for Non-Controlling Interests44 Questions
Exam 30: Further Consolidation Issues IV: Accounting for Changes in the Degree of Ownership of a Subsidiary49 Questions
Exam 31: Accounting for Equity Investments,including Investments in Associates and Joint Arrangements70 Questions
Exam 32: Accounting for Foreign Currency Transactions78 Questions
Exam 33: Translating the Financial Statements of Foreign Operations52 Questions
Exam 34: Accounting for Corporate Social Responsibility73 Questions
Select questions type


The following journal entries were recorded by a vendor who sold goods and received promissory notes on 1 July 2012 in exchange. 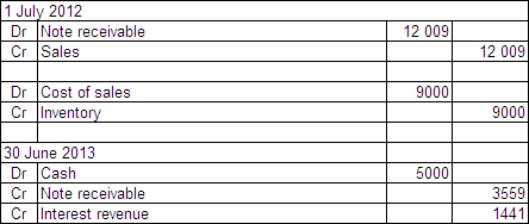 What is the interest rate implicit in the arrangement?
 (Multiple Choice)
4.8/5  (80)
(80) Hillier Construction Ltd commenced the construction of a building on 1 July 2013.It has a fixed-price contract for total revenues of $45 million.The expected completion date is 30 June 2016.The expected total cost to Hillier Construction at the beginning of the project is $35 million.The following information relates only to the construction of this building: For the year ending 30 June 2014 (\ 000) 2015 (\ 000) 2016 (\ 000) Costs for the year 12500 15000 10000 Costs incurred to date 12500 27500 37500 Estimated costs to complete 23000 8500 - Progress billings during the year 10000 12000 23000 Cash collected during the year 10000 11000 24000 Hillier Construction uses the percentage-of-completion method based on cost to account for its construction contracts.What are the journal entries for the year ended 30 June 2014 (rounded to the nearest $000)?
(Multiple Choice)
4.9/5 (69)
(69) When goods are sold on extended credit there is an implicit financing arrangement contained in the sale agreement.In order to separate the financing element from the sale,it is necessary to calculate the applicable interest rate inherent in the agreement.What advice does IASB (2011)provide about this?
(Multiple Choice)
4.8/5 (73)
(73) Interest revenue is derived from borrowing resources from another entity.
(True/False)
4.8/5 (90)
(90) When it is probable that total contract costs will exceed total contract revenue,the expected loss should not be recognised as an expense until the future economic sacrifice eventuates.
(True/False)
4.9/5 (69)
(69) In most cases dividend revenue should not be recognised until the dividend proposed has been ratified by the shareholders at the annual general meeting.
(True/False)
4.8/5 (75)
(75) Construction costs plus gross profit earned to date from a construction contract are accumulated in the construction in progress account less progress billings and these are disclosed in the liability section of the statement of financial position.
(True/False)
4.8/5 (74)
(74) When the collectability of an amount that has been recorded as revenue becomes uncertain,the appropriate accounting treatment is to:
(Multiple Choice)
4.8/5 (74)
(74) Under the AASB (IASB)Conceptual Framework income is now subdivided into:
(Multiple Choice)
4.8/5 (95)
(95) IASB (2011)requires an entity to recognise revenue for a performance obligation satisfied over time only if the entity can:
(Multiple Choice)
4.9/5 (87)
(87) When the gross method is used to record the interest inherent in a sales transaction,it is typical for the accrued interest to be offset against the note receivable.
(True/False)
4.9/5 (89)
(89) Discuss the different conditions detailed in IASB (2011)that must be satisfied before the percentage-of-completion method can be used.
(Essay)
4.9/5 (97)
(97) IASB (2011)requires revenues to be measured in terms of historical cost to improve reliability.
(True/False)
4.8/5 (77)
(77) Discuss how the use of call and put options affect revenue recognition for sales of merchandise with associated conditions.
(Essay)
4.7/5 (70)
(70) When a performance obligation is satisfied,an entity shall recognise revenue:
(Multiple Choice)
4.8/5 (63)
(63) Vettori Ltd has the following information from an aged debtors listing for the current period. Age Amount Less than 1 month old \ 80000 Between 1 month and 2 months old \ 60000 Between 3 and 5 months old \ 30000 Over 5 months old \ 5000 Based on experience in the industry,Vettori Ltd uses the following basis for estimating uncollectible amounts: Age Percentage uncollectible Less than 1 month old 0.50\% Between 1 month and 2 months old 2.00\% Between 3 and 5 months old 5.00\% Over 5 months old 20\% Assuming that the current balance in the provision for doubtful debts is zero,what is the entry to record the provision for this period?
What is the entry to record the writing off of a bad debt of $1000 when a debtor goes bankrupt?
(Multiple Choice)
4.8/5 (88)
(88) In accordance with IASB (2011)discuss the five steps to recognising revenue.
(Essay)
4.9/5 (75)
(75) When the outcome of a construction contract can be estimated reliably,contract revenue and contract costs associated with the construction contract shall be recognised as revenue and expenses respectively by reference to the stage of completion of the contract activity at the reporting date.
(True/False)
4.9/5 (88)
(88) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)