



 Chat with AI
Exam 19: The Statement of Cash Flows


Discuss the terms 'cash' and 'cash equivalents' as they apply to a statement of cash flows.

 (71)
 Answered by Examlex AI Copilot
Cash and cash equivalents are important terms in the context of a statement of cash flows.
Cash refers to physical currency, such as coins and banknotes, as well as any deposits in bank accounts that are available for immediate use. This includes funds in checking accounts, petty cash, and any other highly liquid assets that can be readily converted into cash.
Cash equivalents, on the other hand, are short-term, highly liquid investments that are easily convertible to known amounts of cash and which are subject to an insignificant risk of changes in value. Examples of cash equivalents include Treasury bills, money market funds, and short-term government bonds with maturities of three months or less.
In a statement of cash flows, both cash and cash equivalents are included in the calculation of a company's net cash flow from operating, investing, and financing activities. This provides a clear picture of the company's ability to generate cash and its liquidity position. It also helps investors and creditors assess the company's ability to meet its short-term obligations and fund its operations.
Overall, understanding the distinction between cash and cash equivalents is crucial for accurately analyzing a company's financial health and its ability to generate and manage cash.
A statement of cash flows is a forecast of net cash flows from operating,investing and financing activities.
(93)  Verified
False
The following are cash flow transactions for Greenfell Ltd:
I Depreciation and amortisation II Impairment loss III Issue of bonus shares IV Conversion of debt to equity V Purchase of property plant and equipment VI Dividend reinvestment
Which of the following combinations includes all the non-cash investing and financing transactions of Greenfell Ltd that are required to be disclosed in the notes to the accounts as per AASB 107 Statement of Cash Flows?
(73) VerifiedD
Saints Ltd is preparing a statement of cash flows for the year ended 30 June 2014.You are the accountant of the entity and have collected the following data:
Gain on sale of equipment 12000 Proceeds from sale of equipment 20000 Purchase of government bonds (dated 30 June 2014, face value of \4 00 000) 360000 Dividends declared 90000 Dividends paid 76000 Proceeds from issue of share capital 150000
What is the amount of net cash used in investing and financing activities respectively?
(72) Jaunty Ltd provides the following information for the period ended 30 June 2015:
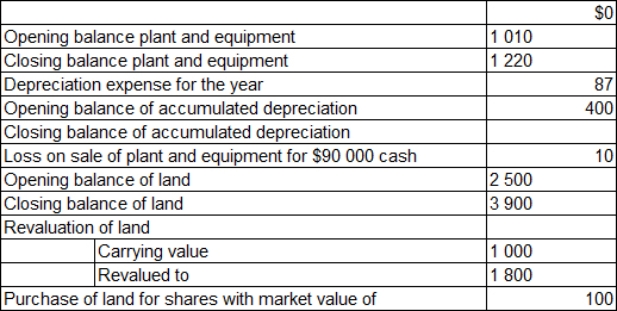 All transactions are in cash unless otherwise indicated.What is the net cash flow from investing activities?
 (85) The following information is provided for Unique Ltd for the period ended 30 June 2015:
\ 0 Cost of goods sold for the year 930 Discounts received for early payment to suppliers 60 Opening balance of trade creditors 160 Closing balance of trade creditors 250 Opening balance of inventory 85 Closing balance of inventory 110 Sales for the year 1560 Discounts provided to customers for early payment 79 Doubtful debts expense 38 Opening balance of accounts receivable 100 Closing balance of accounts receivable 130 Bad debts expense 47 Opening balance of the provision for doubtful debts 115 Closing balance of the provision for doubtful debts 90 Opening balance dividends payable 120 Closing balance dividends payable 90 Dividends proposed 80
All transactions are in cash unless otherwise indicated.What is the net cash flow from operating activities for the period?
(81) AASB 107 requires ledger accounts to be reconstructed in order to calculate cash flows from operating activities.
(79) Swans Machinery Ltd reported a net profit of $3 000 000 for the year ended 30 June 2014.The following changes occurred in the statement of financial position:
Increase (decrease) Equipment 250000 Accumulated depreciation 400000 Note payable 300000
Additional information:
During the year Swans Ltd sold equipment with a cost of $250 000 and had accumulated depreciation of $120 000 for a gain of $50 000.
On 30 June 2014 Swans Ltd purchased equipment costing $500 000 with $200 000 in cash and a note payable for $300 000.
Depreciation expense for the year was $520 000
What is the amount of net cash from operating activities and net cash used in investing activities respectively for the year ended 30 June 2014?
(79) AASB 107 requires disclosures about non-cash financing and investing activities.
(80) Lions Ltd engaged in the following activities for the year ended 30 June 2014:
Sold shares in Kangaroo Ltd for $70 000.The investment had a carrying amount of $66 000.
Purchased shares in Cats Ltd for $52 000
Purchased government bonds for $100 000
Issued Lions Ltd shares for $100 000
What is the net cash flow used in investing activities?
(76) Mistril Ltd provides the following information for the period ended 30 June 2015:
\ 0 Interest revenue 50 Opening balance interest receivable 25 Closing balance interest receivable 15 Debentures (asset) discount amortisation 6 Income tax expense 15 Opening balance income tax payable 29 Closing balance income tax payable 33 Opening balance deferred tax liability 9 Closing balance deferred tax liability 4 Dividend revenue 10 Opening balance of dividend receivable 6 Closing balance of dividend receivable 9
What are the cash flows from interest,dividends and tax for the period?
(69) In accordance with AASB 107,what is the appropriate classification for the conversion of preference shares to ordinary shares?
(72) Bulldogs Ltd had the following activities related to their financial operations:
Paid $1 125 000 for the early retirement of convertible notes (amortised cost of $1 110 000)
Paid cash dividends of $93 000.Preference shares with carrying amount of $120 000 were converted to ordinary shares.
What is net cash used in financing activities for the year ended 30 June 2014?
(74) Sharma (1996)suggests that a cash-flow based measure of retained cash flows from operations (RCFFO)may be an important indicator of financial flexibility.How is RCFFO measured?
(82) The statement of cash flows may assist in determining the ability of an entity to:
(74) Identify and discuss the three classifications of the statement of cash flows.
(95) Walter (1987)claimed that 'one of the strongest antidotes to creative accounting is a requirement for statement of cash flows to have '.
(80) Following are the cash flow transactions for Wadonga Ltd:
I Non-cash items II Cash proceeds from suppliers III Payment of debentures Proceeds from issue of a convertible note Purchase of property plant and equipment Proceeds from issue of ordinary shares
Which of the following combinations includes all of the transactions that will determine cash flows from financing activities of Wadonga Ltd that are in accordance with AASB 107 Statement of Cash Flows?
(76) Following are cash flow transactions for Cootamundra Ltd:
I Interest paid II Interest received III Dividends paid Dividends received Purchase of property plant and equipment Proceeds from issue of shares
Which of the following combinations includes all transactions that may by classified under investing activities of Cootamundra Ltd that are in accordance with AASB 107 Statement of Cash Flows?
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)