



 Chat with AI
Exam 15: Revenue Recognition Issues

Exam 1: An Overview of the Australian External Reporting Environment70 Questions
Exam 2: The Conceptual Framework of Accounting and Its Relevance to Financial Reporting72 Questions
Exam 3: Theories of Accounting76 Questions
Exam 4: An Overview of Accounting for Assets77 Questions
Exam 5: Depreciation of Property, plant and Equipment77 Questions
Exam 6: Revaluations and Impairment Testing of Non-Current Assets76 Questions
Exam 7: Inventory75 Questions
Exam 8: Accounting for Intangibles77 Questions
Exam 9: Accounting for Heritage Assets and Biological Assets76 Questions
Exam 10: An Overview of Accounting for Liabilities78 Questions
Exam 11: Accounting for Leases81 Questions
Exam 12: Accounting for Employee Benefits84 Questions
Exam 13: Share Capital and Reserves85 Questions
Exam 14: Accounting for Financial Instruments90 Questions
Exam 15: Revenue Recognition Issues79 Questions
Exam 16: The Statement of Comprehensive Income and Statement of Changes in Equity77 Questions
Exam 17: Accounting for Share-Based Payments77 Questions
Exam 18: Accounting for Income Taxes80 Questions
Exam 19: The Statement of Cash Flows77 Questions
Exam 20: Accounting for the Extractive Industries75 Questions
Exam 21: Accounting for General Insurance Contracts73 Questions
Exam 22: Accounting for Superannuation Plans77 Questions
Exam 23: Events Occurring After the End of the Reporting Period77 Questions
Exam 24: Segment Reporting77 Questions
Exam 25: Related Party Disclosures77 Questions
Exam 26: Earnings Per Share76 Questions
Exam 27: Accounting for Group Structures87 Questions
Exam 28: Further Consolidation Issues I: Accounting for Intragroup Transactions60 Questions
Exam 29: Further Consolidation Issues II: Accounting for Non-Controlling Interests44 Questions
Exam 30: Further Consolidation Issues IV: Accounting for Changes in the Degree of Ownership of a Subsidiary49 Questions
Exam 31: Accounting for Equity Investments,including Investments in Associates and Joint Arrangements70 Questions
Exam 32: Accounting for Foreign Currency Transactions78 Questions
Exam 33: Translating the Financial Statements of Foreign Operations52 Questions
Exam 34: Accounting for Corporate Social Responsibility73 Questions
Select questions type


Transactions such as the purchase of assets or the issuance of debt are not considered income because:

Free
(Multiple Choice)
4.9/5  (78)
(78) Correct Answer: Verified
C
Werribee Direct Ltd is a mail order company that allows its customers to order online and return the goods without obligations.Werribee Direct Ltd had experienced a high ratio of returned merchandise from online sales.What is the appropriate accounting treatment for this sale that is in accordance with IASB (2011)Revenue?
Free
(Multiple Choice)
4.9/5 (80)
(80) Correct Answer:Verified
VerifiedA
A group of contracts shall be treated as:
Free
(Multiple Choice)
4.8/5 (83)
(83) Correct Answer:Verified
VerifiedC
IASB and FASB initiated a joint project to clarify the principle for recognising revenue and develop a common revenue standard for IFRS and US GAAP so as to:
(Multiple Choice)
5.0/5 (83)
(83) Magazines Galore receives subscription money in advance,and has received $50 000 from customers on 1 February to cover the next ten issues of Wheels Galore.There are ten issues a year-one at the end of each month except for January and December.What are the appropriate accounting entries to record the receipt of the subscription money and (assuming no monthly entries have been made)the adjusting entry at 30 June (after June's issue has been mailed to subscribers)?
(Multiple Choice)
4.8/5 (90)
(90) Which of the following is not a step in recognising revenue according to IASB (2011)?
(Multiple Choice)
4.9/5 (76)
(76) Which of the following statements is not an indicator of the transfer of the control of an asset to a customer?
(Multiple Choice)
4.7/5 (83)
(83) Which of the following is an example of a situation in which an entity does not retain the control of the asset?
(Multiple Choice)
5.0/5 (81)
(81) If a company sells its product but gives the buyer the right to return the product,IASB (2011)requires revenue from the sales transaction to be recognised at the time of sale.
(True/False)
4.8/5 (75)
(75) The AASB (IASB)Conceptual Framework now divides revenues into 'income' and 'gains'.
(True/False)
4.8/5 (95)
(95) Russell Ltd commenced the construction of a bridge on 1July 2013.It has a fixed-price contract for total revenues of $35million.The expected completion date is 30 June 2016.The expected total cost to Russell Ltd at the beginning of the project is $29 million.The following information relates only to the construction of the bridge: For the year ending 30 June 2014 (\ 000) 2015 (\ 000) 2016 (\ 000) Costs for the year 12000 18000 7000 Costs incurred to date 12000 30000 37000 Estimated costs to complete 19500 6300 - Progress billings during the year 10000 12000 13000 Cash collected during the year 7000 10000 18000 Russell Ltd uses the percentage-of-completion method based on cost to account for its construction contracts.What is the gross profit to be recognised in each of the 3 years (rounded to the nearest $000)?
(Multiple Choice)
4.9/5 (82)
(82) Hillier Construction Ltd commenced the construction of a building on 1 July 2013.It has a fixed-price contract for total revenues of $45 million.The expected completion date is 30 June 2016.The expected total cost to Hillier Construction at the beginning of the project is $35 million.The following information relates only to the construction of this building: For the year ending 30 June 2014 (\ 000) 2015 (\ 000) 2016 (\ 000) Costs for the year 12500 15000 10000 Costs incurred to date 12500 27500 37500 Estimated costs to complete 23000 8500 - Progress billings during the year 10000 12000 23000 Cash collected during the year 10000 11000 24000 Hillier Construction uses the percentage-of-completion method based on cost to account for its construction contracts.What is the gross profit to be recognised in each of the 3 years (rounded to the nearest $000)?
(Multiple Choice)
4.7/5 (68)
(68) Under the AASB (IASB)Conceptual Framework an increase in economic benefits in the form of the reduction of a liability that is not a contribution by equity participants and results in an increase in equity during the reporting period,is income.
(True/False)
4.8/5 (78)
(78) Which of the following statements is incorrect with respect to revenue recognition of construction contracts?
(Multiple Choice)
4.8/5 (74)
(74) Daniel Ltd sells one of its properties to a financing company with an attached call option,which allows Daniel Ltd to reacquire the property at a future date for $400 000.The current market value at the time of the sale is $300 000,but the financing company pays $350 000 for it.It is expected that the market value of the property will exceed $400 000 before the option expires.What is the appropriate treatment of this sale?
(Multiple Choice)
5.0/5 (90)
(90) The following is a diagram of the earnings cycle as presented by Coombes and Martin (1982). 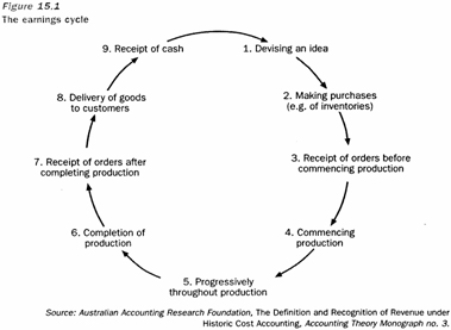 In the traditional historical-cost accounting model,at what point has revenue been recognised for long-term construction contracts in the building industry?
 (Multiple Choice)
4.8/5 (82)
(82) Explain the accounting treatment when a third party supplies the awards under a customer loyalty programme.
(Essay)
4.9/5 (80)
(80) On 1 July 2013 Bryson Ltd sells a machine to Adams Ltd in exchange for a promissory note that requires Adams Ltd to make five payments of $8000,the first to be made on 30 June 2014.The machine cost Bryson Ltd $20 000 to manufacture.Bryson Ltd would normally sell this type of machine for $30 326 for cash or short-term credit.The implicit interest rate in the agreement is 10%.What are the appropriate journal entries to record the sale agreement and the first two instalments using the net-interest method?
(Multiple Choice)
4.9/5 (75)
(75) When the cost basis is used to calculate the percentage of completion,cost items that may need adjustment include:
(Multiple Choice)
4.8/5 (84)
(84) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)