



 Chat with AI
Exam 14: Firms in Competitive Markets

Exam 1: Ten Principles of Economics281 Questions
Exam 2: Thinking Like an Economist451 Questions
Exam 3: Interdependence and the Gains From Trade353 Questions
Exam 4: The Market Forces of Supply and Demand467 Questions
Exam 5: Elasticity and Its Application409 Questions
Exam 6: Supply, Demand, and Government Policies459 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets363 Questions
Exam 8: Application: The Costs of Taxation353 Questions
Exam 9: Application: International Trade333 Questions
Exam 10: Externalities352 Questions
Exam 11: Public Goods and Common Resources270 Questions
Exam 12: The Design of the Tax System397 Questions
Exam 13: The Costs of Production434 Questions
Exam 14: Firms in Competitive Markets381 Questions
Exam 15: Monopoly427 Questions
Exam 16: Monopolistic Competition416 Questions
Exam 17: Oligopoly325 Questions
Exam 18: The Markets for the Factors of Production361 Questions
Exam 19: Earnings and Discrimination335 Questions
Exam 20: Income Inequality and Poverty312 Questions
Exam 21: The Theory of Consumer Choice354 Questions
Exam 22: Frontiers of Microeconomics262 Questions
Exam 23: Measuring a Nations Income343 Questions
Exam 24: Measuring the Cost of Living358 Questions
Exam 25: Production and Growth335 Questions
Exam 26: Saving, investment, and the Financial System381 Questions
Exam 27: The Basic Tools of Finance336 Questions
Exam 28: Unemployment533 Questions
Exam 29: The Monetary System366 Questions
Exam 30: Money Growth and Inflation312 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts346 Questions
Exam 32: A Macroeconomic Theory of the Open Economy300 Questions
Exam 33: Aggregate Demand and Aggregate Supply386 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand334 Questions
Exam 35: The Short-Run Trade-Off Between Inflation and Unemployment306 Questions
Exam 36: Five Debates Over Macroeconomic Policy179 Questions
Select questions type


A firm operating in a perfectly competitive market earns zero economic profit in the long run but remains in business because the firm's revenues cover the business owners' opportunity costs.
(True/False)
4.7/5  (71)
(71) A firm will shut down in the short run if revenue is not sufficient to cover all of its fixed costs of production.
(True/False)
4.7/5 (88)
(88) A firm in a competitive market currently produces and sells 500 doorknobs for a price of $10 per doorknob.Which of the following events would decrease the firm's average revenue?
(Multiple Choice)
4.9/5 (89)
(89) Table 14-1
 -Refer to Table 14-1.For a firm operating in a competitive market,the price is
 (Multiple Choice)
4.9/5 (85)
(85) In a perfectly competitive market,the process of entry and exit will end when firms face
(Multiple Choice)
4.8/5 (77)
(77) Table 14-6
John's Vineyard
 -Refer to Table 14-6.What is the average revenue when 4 units are sold?
 (Multiple Choice)
4.9/5 (73)
(73) Figure 14-4  -Refer to Figure 14-4.Firms would be encouraged to enter this market for all prices that exceed
 (Multiple Choice)
4.8/5 (80)
(80) A firm will shut down in the short run if,for all positive levels of output,
(Multiple Choice)
5.0/5 (71)
(71) A competitive firm would benefit from charging a price below the market price because the firm would achieve
(Multiple Choice)
4.8/5 (67)
(67) Competitive firms that earn a loss in the short run should
(Multiple Choice)
4.8/5 (87)
(87) Raiman's Shoe Repair produces custom-made shoes.When Mr.Raiman produces 12 pairs per week,the marginal cost of the twelfth pair is $84,and the marginal revenue of the twelfth pair is $70.What would you advise Mr.Raiman to do?
(Multiple Choice)
4.9/5 (95)
(95) A firm in a competitive market has the following cost structure:
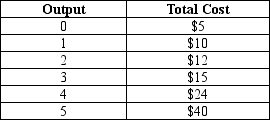 If the market price is $16,this firm will
 (Multiple Choice)
5.0/5 (66)
(66) Table 14-5
 -Refer to Table 14-5.At which quantity of output is marginal revenue equal to marginal cost?
 (Multiple Choice)
4.9/5 (71)
(71) A firm's marginal cost has a minimum value of $2,its average variable cost has a minimum value of $4,and its average total cost has a minimum value of $5.Then the firm will shut down if the price of its product falls below
(Multiple Choice)
4.9/5 (86)
(86) Table 14-4
 -Refer to Table 14-4.What is the firm's profit-maximizing strategy?
 (Multiple Choice)
4.8/5 (83)
(83) Scenario 14-3
As part of an estate settlement Mary received $1 million.She decided to use the money to purchase a small business in Anywhere,USA.Her business operates in a perfectly competitive industry.If Mary would have invested the $1 million in a risk-free bond fund she could have made $100,000 each year.She also quit her job with Lucky.Com Inc.to devote all of her time to her new business;her salary at Lucky.Com Inc.was $75,000 per year.
-Refer to Scenario 14-3.How large would Mary's accounting profits need to be to allow her to attain zero economic profit?
(Multiple Choice)
4.8/5 (85)
(85) Which of the following is not a characteristic of a competitive market?
(Multiple Choice)
4.9/5 (69)
(69) In the long run,a firm will enter a competitive industry if
(Multiple Choice)
4.8/5 (71)
(71) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)