



 Chat with AI
Exam 13: The Costs of Production

Exam 1: Ten Principles of Economics281 Questions
Exam 2: Thinking Like an Economist451 Questions
Exam 3: Interdependence and the Gains From Trade353 Questions
Exam 4: The Market Forces of Supply and Demand467 Questions
Exam 5: Elasticity and Its Application409 Questions
Exam 6: Supply, Demand, and Government Policies459 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets363 Questions
Exam 8: Application: The Costs of Taxation353 Questions
Exam 9: Application: International Trade333 Questions
Exam 10: Externalities352 Questions
Exam 11: Public Goods and Common Resources270 Questions
Exam 12: The Design of the Tax System397 Questions
Exam 13: The Costs of Production434 Questions
Exam 14: Firms in Competitive Markets381 Questions
Exam 15: Monopoly427 Questions
Exam 16: Monopolistic Competition416 Questions
Exam 17: Oligopoly325 Questions
Exam 18: The Markets for the Factors of Production361 Questions
Exam 19: Earnings and Discrimination335 Questions
Exam 20: Income Inequality and Poverty312 Questions
Exam 21: The Theory of Consumer Choice354 Questions
Exam 22: Frontiers of Microeconomics262 Questions
Exam 23: Measuring a Nations Income343 Questions
Exam 24: Measuring the Cost of Living358 Questions
Exam 25: Production and Growth335 Questions
Exam 26: Saving, investment, and the Financial System381 Questions
Exam 27: The Basic Tools of Finance336 Questions
Exam 28: Unemployment533 Questions
Exam 29: The Monetary System366 Questions
Exam 30: Money Growth and Inflation312 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts346 Questions
Exam 32: A Macroeconomic Theory of the Open Economy300 Questions
Exam 33: Aggregate Demand and Aggregate Supply386 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand334 Questions
Exam 35: The Short-Run Trade-Off Between Inflation and Unemployment306 Questions
Exam 36: Five Debates Over Macroeconomic Policy179 Questions
Select questions type


The economic field of industrial organization examines how firms' decisions about prices and quantities depend on the market conditions they face.
(True/False)
4.9/5  (80)
(80) A certain firm manufactures and sells computer chips.Last year it sold 2 million chips at a price of $10 per chip.For last year,the firm's
(Multiple Choice)
4.8/5 (88)
(88) Scenario 13-3
Tony is a wheat farmer,but he also spends part of his day teaching guitar lessons.Due to the popularity of his local country western band,Farmer Tony has more students requesting lessons than he has time for if he is to also maintain his farming business.Farmer Tony charges $25 an hour for his guitar lessons.One spring day,he spends 10 hours in his fields planting $130 worth of seeds on his farm.He expects that the seeds he planted will yield $300 worth of wheat.
-Refer to Scenario 13-3.What is the total opportunity cost of the day that Farmer Tony incurred for his spring day in the field planting wheat?
(Multiple Choice)
4.9/5 (76)
(76) If the marginal cost curve is rising,then so is the average total cost curve.
(True/False)
4.9/5 (63)
(63) 
According to the mathematical laws that govern the relationship between average total cost and marginal cost,where must these two curves intersect?
(Essay)
4.8/5 (72)
(72) Scenario 13-7
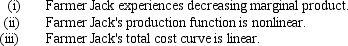
Farmer Jack is a watermelon farmer.If Jack plants no seeds on his farm,he gets no harvest.If he plants 1 bag of seeds,he gets 30 watermelons.If he plants 2 bags of seeds,he gets 50 watermelons.If he plants 3 bags of seeds he gets 60 watermelons.A bag of seeds costs $100,and the costs of seeds are his only costs.
-Refer to Scenario 13-7.Which of the following statements is (are)true?
(Multiple Choice)
4.9/5 (70)
(70) Tom's Tent Company has total fixed costs of $300,000 per year.The firm's average variable cost is $80 for 10,000 tents.At that level of output,the firm's average total costs equal
(Multiple Choice)
4.8/5 (79)
(79) An example of an opportunity cost that is also an implicit cost is
(Multiple Choice)
4.7/5 (96)
(96) Larry's Lunchcart is a small street vendor business.If Larry makes 15 pretzels in his first hour of business and incurs a total cost of $16.50,his average total cost per pretzel is
(Multiple Choice)
4.8/5 (72)
(72) Some costs do not vary with the quantity of output produced.Those costs are called
(Multiple Choice)
5.0/5 (69)
(69) Which of these assumptions is often realistic for a firm in the short run?
(Multiple Choice)
4.8/5 (76)
(76) What are opportunity costs? How do explicit and implicit costs relate to opportunity costs?
(Essay)
4.7/5 (78)
(78) Figure 13-9
The figure below depicts average total cost functions for a firm that produces automobiles.  -Refer to Figure 13-9.At levels of output between M and N,the firm experiences
 (Multiple Choice)
4.9/5 (85)
(85) Kirsten sells 300 glasses of lemonade at $0.50 each.Her total costs are $125.Her profits are
(Multiple Choice)
4.9/5 (75)
(75) David's firm experiences diminishing marginal product for all ranges of inputs.The total cost curve associated with David's firm
(Multiple Choice)
4.8/5 (71)
(71) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)