



 Chat with AI
Exam 12: Perfect Competition

Exam 1: What Is Economics479 Questions
Exam 2: The Economic Problem440 Questions
Exam 3: Demand and Supply515 Questions
Exam 4: Elasticity533 Questions
Exam 5: Efficiency and Equity450 Questions
Exam 6: Government Actions in Markets412 Questions
Exam 7: Global Markets in Action200 Questions
Exam 8: Utility and Demand364 Questions
Exam 9: Possibilities, Preferences, and Choices459 Questions
Exam 10: Organizing Production385 Questions
Exam 11: Output and Costs493 Questions
Exam 12: Perfect Competition487 Questions
Exam 13: Monopoly599 Questions
Exam 14: Monopolistic Competition319 Questions
Exam 15: Oligopoly276 Questions
Exam 16: Public Choices, Public Goods, and Healthcare205 Questions
Exam 17: Externalities437 Questions
Exam 18: Markets for Factors of Production382 Questions
Exam 19: Economic Inequality353 Questions
Exam 20: Uncertainty and Information233 Questions
Select questions type


In the long-run equilibrium, perfectly competitive firms produce where
(Multiple Choice)
4.9/5  (87)
(87) 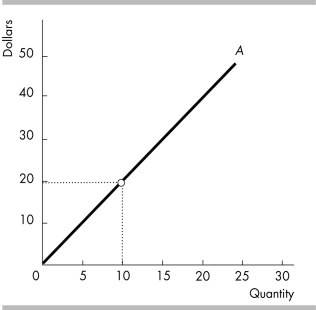 -For a perfectly competitive firm, curve A in the above figure is the firm's
 (Multiple Choice)
4.8/5 (90)
(90) An individual perfectly competitive firm has a supply curve
(Multiple Choice)
4.9/5 (79)
(79)  -In the long run, perfectly competitive firms earn just enough revenue to
 (Multiple Choice)
4.8/5 (78)
(78) "Higher ethanol production definitely and directly raises the price of corn," said USDA economist Ephraim Leibtag. In the short run, what is TRUE if the production of ethanol increases?
(Multiple Choice)
4.8/5 (73)
(73) If the price exceeds the average variable cost, by producing the level of output such that marginal revenue equals marginal cost, the firm ensures that it will
(Multiple Choice)
4.8/5 (84)
(84) Suppose a perfectly competitive market is in a long-run equilibrium when a permanent decrease in the market demand occurs. In the long run, which of the following definitely occurs?
(Multiple Choice)
4.9/5 (92)
(92) Which of the following is NOT an assumption of perfectly competitive markets?
(Multiple Choice)
4.8/5 (73)
(73)
-The figure above portrays a total revenue curve for a perfectly competitive firm. Curve A is straight because the firm
-The figure above portrays a total revenue curve for a perfectly competitive firm. Curve A is straight because the firm (Multiple Choice)
5.0/5 (86)
(86) Today, firms in a perfectly competitive market are making an economic profit. In the long run, firms will ________ the market until all firms in the market are ________.
(Multiple Choice)
4.9/5 (78)
(78) Ellen's Painting Services is a perfectly competitive firm that currently paints 10 houses a month and charges $100 per house, which is the going market price. Ellen's marginal cost is positively related with the quantity of service she provides and is currently $120. What should Ellen do to increase her economic profit? Paint more houses? Raise her price? Explain your answer.
(Essay)
4.8/5 (79)
(79) 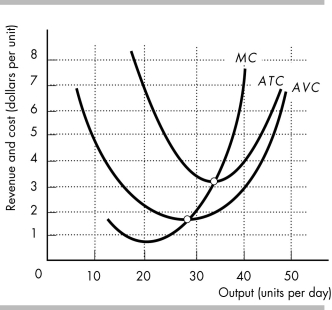 -The above figure shows the cost curves of a profit-maximizing perfectly competitive firm. If the price equals $7,
a) how much will the firm produce?
b) how much is the firm's average total, average variable, and marginal costs?
c) how much is the firm's total, total variable, and total fixed costs?
d) how much is the firm's total revenue and economic profit?
e) what will happen in this market in the long run?
-The above figure shows the cost curves of a profit-maximizing perfectly competitive firm. If the price equals $7,
a) how much will the firm produce?
b) how much is the firm's average total, average variable, and marginal costs?
c) how much is the firm's total, total variable, and total fixed costs?
d) how much is the firm's total revenue and economic profit?
e) what will happen in this market in the long run? (Essay)
4.8/5 (74)
(74) A perfectly competitive firm is definitely making an economic profit when
(Multiple Choice)
4.8/5 (73)
(73) For a firm in perfect competition, a diagram shows quantity on the horizontal axis and both the firm's marginal cost (MC) and its marginal revenue (MR) on the vertical axis. The firm's profit-maximizing quantity occurs at the point where the
(Multiple Choice)
4.9/5 (71)
(71)  -Sue's Sea Shells by the Sea Shore is a perfectly competitive firm selling sea shells at the market price of $2 per dozen. Sue's Sea Shells by the Sea Shore has fixed costs of $40 per day and a variable cost schedule in the table above. Based on this information, we can expect the number of firms in the sea shell market to
 (Multiple Choice)
4.8/5 (71)
(71) In the long-run equilibrium in a perfectly competitive market, the firms produce at the ________ possible average total cost and the price equals the ________ possible average total cost.
(Multiple Choice)
4.8/5 (75)
(75)  -Based on the table above which shows Chip's costs, if rice sells for $600 a ton, Chip's profit-maximizing output is
 (Multiple Choice)
4.9/5 (85)
(85) The demand for wheat from farm A is perfectly elastic because wheat from farm A is
(Multiple Choice)
4.8/5 (77)
(77) The demand for a product produced in a perfectly competitive market permanently increases. In the short run, the price
(Multiple Choice)
4.8/5 (84)
(84) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)