



 Chat with AI
Exam 12: Perfect Competition

Exam 1: What Is Economics479 Questions
Exam 2: The Economic Problem440 Questions
Exam 3: Demand and Supply515 Questions
Exam 4: Elasticity533 Questions
Exam 5: Efficiency and Equity450 Questions
Exam 6: Government Actions in Markets412 Questions
Exam 7: Global Markets in Action200 Questions
Exam 8: Utility and Demand364 Questions
Exam 9: Possibilities, Preferences, and Choices459 Questions
Exam 10: Organizing Production385 Questions
Exam 11: Output and Costs493 Questions
Exam 12: Perfect Competition487 Questions
Exam 13: Monopoly599 Questions
Exam 14: Monopolistic Competition319 Questions
Exam 15: Oligopoly276 Questions
Exam 16: Public Choices, Public Goods, and Healthcare205 Questions
Exam 17: Externalities437 Questions
Exam 18: Markets for Factors of Production382 Questions
Exam 19: Economic Inequality353 Questions
Exam 20: Uncertainty and Information233 Questions
Select questions type


 -The figure above shows the costs for a grower in the perfectly competitive turnip market. If the price is $1,200 for a ton of turnips, the firm is
 (Multiple Choice)
4.9/5  (87)
(87)  -The apple market is perfectly competitive and is in long-run equilibrium. Now a disease kills 50 percent of the apple orchards. In the short run, the price of a bag of apples ________ and the remaining apple growers make ________ economic profit. In the long run, the ________.
 (Multiple Choice)
4.9/5 (79)
(79) "For a perfectly competitive market, an economic profit attracts new firms. But when these firms enter the market, the price falls and the economic profit is eliminated." Are the previous statements correct or incorrect? What is the long-run profit or loss outcome for firms in a perfectly competitive market?
(Essay)
4.8/5 (85)
(85) 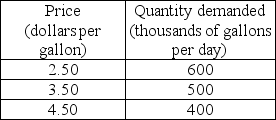 -The market for milk is perfectly competitive. There are 1,000 farms in the industry and the relationship between a typical farm's output and total costs is the same as in Problem 2. The market demand schedule for milk is shown in the table above.
a) What is a typical farm's supply schedule and what is the market supply schedule?
b) What is the market price? What quantity of milk is sold?
c) What is the output produced by each farm? What type of profit or loss is made by each farm?
d) Do farms enter or exit the market?
-The market for milk is perfectly competitive. There are 1,000 farms in the industry and the relationship between a typical farm's output and total costs is the same as in Problem 2. The market demand schedule for milk is shown in the table above.
a) What is a typical farm's supply schedule and what is the market supply schedule?
b) What is the market price? What quantity of milk is sold?
c) What is the output produced by each farm? What type of profit or loss is made by each farm?
d) Do farms enter or exit the market? (Essay)
4.9/5 (81)
(81) 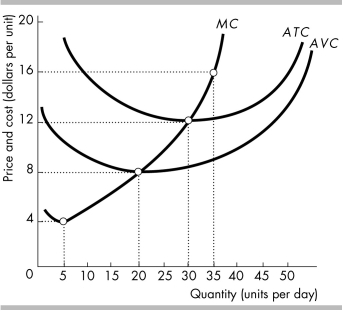 -In the above figure, at what price does a perfectly competitive firm make zero economic profit?
 (Multiple Choice)
4.8/5 (81)
(81)  -In the short run, a perfectly competitive firm
When Sidney's Sweaters, Inc. makes exactly zero economic profit, Sidney, the owner
(Multiple Choice)
4.9/5 (90)
(90) 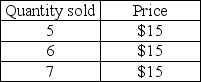 -In the above table, if the firm sells 5 units of output, its total revenue is
 (Multiple Choice)
4.9/5 (82)
(82)  -The figure above shows the marginal revenue and long-run cost curves for a perfectly competitive firm. All other firms in the industry have identical curves. Which of the following statements is TRUE?
 (Multiple Choice)
4.8/5 (86)
(86)  -In the above figure, by increasing its output from Q2 to Q3, the firm
 (Multiple Choice)
4.9/5 (84)
(84)  -Given the total cost and total revenue curves in the above figure, what are the output levels at which the perfect competitor will incur economic losses?
 (Multiple Choice)
4.9/5 (82)
(82)  -In the above table, the firm
Suppose a perfectly competitive market is in long-run equilibrium. If there is a permanent increase in demand,
(Multiple Choice)
4.9/5 (78)
(78)  -The figure above shows a typical perfectly competitive corn farm, whose marginal cost curve is MC and average total cost curve is ATC. The market is initially in a long-run equilibrium, where the price is $3.00 per bushel. Then, the market demand for corn decreases and, in the short run, the price falls to $2.50 per bushel. In the long run, the price of corn is ________ and a typical farm produces ________ bushels of corn.
 (Multiple Choice)
4.8/5 (79)
(79) In a perfectly competitive market, many firms sell an identical product.
(True/False)
4.7/5 (87)
(87) Suppose that newspaper companies are now required to use recycled paper, which is more expensive than new paper. Which of the following is most likely to result if the newspaper industry is highly competitive?
(Multiple Choice)
5.0/5 (80)
(80) A perfectly competitive firm is making an economic profit when
(Multiple Choice)
4.9/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)