



 Chat with AI
Exam 12: Perfect Competition

Exam 1: What Is Economics479 Questions
Exam 2: The Economic Problem440 Questions
Exam 3: Demand and Supply515 Questions
Exam 4: Elasticity533 Questions
Exam 5: Efficiency and Equity450 Questions
Exam 6: Government Actions in Markets412 Questions
Exam 7: Global Markets in Action200 Questions
Exam 8: Utility and Demand364 Questions
Exam 9: Possibilities, Preferences, and Choices459 Questions
Exam 10: Organizing Production385 Questions
Exam 11: Output and Costs493 Questions
Exam 12: Perfect Competition487 Questions
Exam 13: Monopoly599 Questions
Exam 14: Monopolistic Competition319 Questions
Exam 15: Oligopoly276 Questions
Exam 16: Public Choices, Public Goods, and Healthcare205 Questions
Exam 17: Externalities437 Questions
Exam 18: Markets for Factors of Production382 Questions
Exam 19: Economic Inequality353 Questions
Exam 20: Uncertainty and Information233 Questions
Select questions type


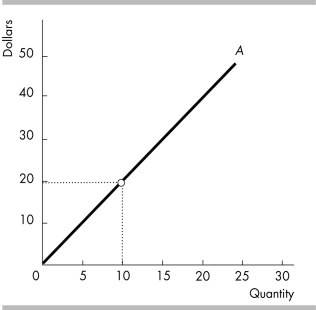 -In the above figure showing a perfectly competitive firm's total revenue line, the firm's marginal revenue
 (Multiple Choice)
4.8/5  (96)
(96) Individual firms in perfectly competitive industries are price takers because
(Multiple Choice)
4.9/5 (75)
(75) 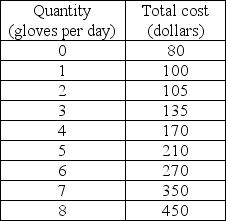 -The above table shows the per day total cost for Kiley's Baseball Glove Company. Each glove is priced at $50 and Kiley's Baseball Glove Company is a perfectly competitive firm. Between which two amounts of output does Kiley's Baseball Glove Company make an economic profit?
 (Multiple Choice)
4.9/5 (68)
(68) Which of the following statements regarding the long-term equilibrium is TRUE?
(Multiple Choice)
4.9/5 (85)
(85) If the price of its product falls below the minimum point on the AVC curve, the best a perfectly competitive firm can do is to
(Multiple Choice)
4.9/5 (95)
(95) In the long run, if firms in a perfectly competitive market are incurring economic losses, then
(Multiple Choice)
4.8/5 (89)
(89) If the market price in a perfectly competitive market is less than a firm's minimum average variable cost, then the firm's total revenue will always ________.
(Multiple Choice)
4.9/5 (81)
(81) Entry of new firms into a perfectly competitive market raises the product's price.
(True/False)
4.9/5 (67)
(67) At its shutdown point, a perfectly competitive firm earns total revenue that
(Multiple Choice)
4.9/5 (69)
(69) In perfect competition, the marginal revenue of an individual firm
(Multiple Choice)
4.8/5 (79)
(79)  -Giuseppe's Pizza is a perfectly competitive firm. The firm's costs are shown in the table above. If the market price is $15, how much economic profit does the firm make?
 (Multiple Choice)
4.8/5 (75)
(75)  -Fast Copy is a perfectly competitive firm. The figure above shows Fast Copy's cost curves. If the market price is 4 cents per page, what is Fast Copy's economic profit?
 (Multiple Choice)
4.7/5 (68)
(68)  -Based on the table above which shows Chip's costs, if rice sells for $600 a ton, Chip will
 (Multiple Choice)
4.9/5 (74)
(74) In the short run, a perfectly competitive firm will shut down if at the profit maximizing quantity the
(Multiple Choice)
5.0/5 (82)
(82)  -The table above shows output and costs of Evan's Subs, a typical perfectly competitive firm in a local market for sandwiches. Evan's fixed cost is $9 per hour. The current market price of a sandwich is $6. What is Evan's shut-down price?
 (Multiple Choice)
4.9/5 (90)
(90)  -In the above figure, the line represented by the "1" is the
 (Multiple Choice)
4.9/5 (76)
(76) A perfectly competitive firm shuts down if the price of its product is
(Multiple Choice)
4.9/5 (73)
(73)  -Given the total cost and total revenue curves in the figure above, what is the profit-maximizing output level?
 (Multiple Choice)
4.8/5 (77)
(77) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)