



 Chat with AI
Exam 12: Perfect Competition

Exam 1: What Is Economics479 Questions
Exam 2: The Economic Problem440 Questions
Exam 3: Demand and Supply515 Questions
Exam 4: Elasticity533 Questions
Exam 5: Efficiency and Equity450 Questions
Exam 6: Government Actions in Markets412 Questions
Exam 7: Global Markets in Action200 Questions
Exam 8: Utility and Demand364 Questions
Exam 9: Possibilities, Preferences, and Choices459 Questions
Exam 10: Organizing Production385 Questions
Exam 11: Output and Costs493 Questions
Exam 12: Perfect Competition487 Questions
Exam 13: Monopoly599 Questions
Exam 14: Monopolistic Competition319 Questions
Exam 15: Oligopoly276 Questions
Exam 16: Public Choices, Public Goods, and Healthcare205 Questions
Exam 17: Externalities437 Questions
Exam 18: Markets for Factors of Production382 Questions
Exam 19: Economic Inequality353 Questions
Exam 20: Uncertainty and Information233 Questions
Select questions type


In perfect competition, the elasticity of demand for the product of a single firm is
(Multiple Choice)
5.0/5  (87)
(87) 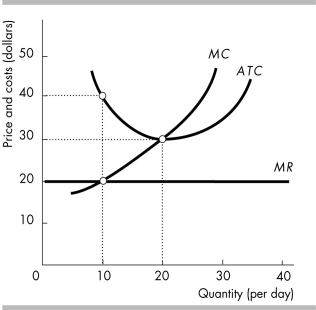 -The figure above shows a perfectly competitive firm. The firm will shut down in the short run if total fixed costs
 (Multiple Choice)
4.7/5 (87)
(87) Why is the demand for a perfectly competitive firm's good perfectly elastic even though the market demand is not?
(Essay)
4.9/5 (80)
(80) The market for maple syrup is perfectly competitive. Suppose that the market is in long-run equilibrium when the market demand for maple syrup increases. In the long run, firms will ________ the market and the market ________ will ________.
(Multiple Choice)
4.8/5 (76)
(76)  -In the short run, perfectly competitive firms ________ but in the long run, perfectly competitive firms ________.
 (Multiple Choice)
4.7/5 (80)
(80)  -The figure above shows a typical perfectly competitive corn farm, whose marginal cost curve is MC and average total cost curve is ATC. The market is initially in a long-run equilibrium, where the price is $3.00 per bushel. Then, the market demand for corn decreases and, in the short run, the price falls to $2.50 per bushel. In the new short-run equilibrium, the farm produces ________ bushels of corn and sells corn at ________ per bushel.
 (Multiple Choice)
4.8/5 (77)
(77) 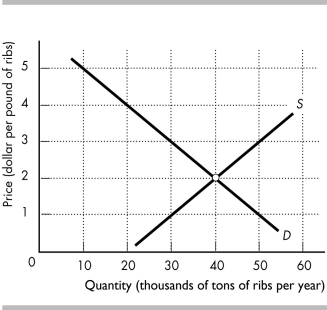
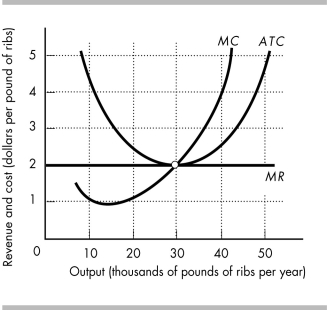 -American restaurants receive their supply of baby back-ribs from American farms and from farms in Denmark. In the figures above, the first diagram shows the perfectly competitive market for baby back ribs in the United States. The second figure shows the situation at Premium Standard Farm in Kansas, one of the many U.S. farms supplying these ribs.
Now assume that the United States imposes a ban on European meat in response to the foot-and-mouth disease that has infected livestock in Europe. (Which the United States did several years ago.) In particular, suppose that the U.S. ban decreases the supply by 40 tons a year. Using the first figure, show the impact of this ban on the baby back rib market. Using the second figure, show the impact on Premium Standard Farm in Kansas.
-American restaurants receive their supply of baby back-ribs from American farms and from farms in Denmark. In the figures above, the first diagram shows the perfectly competitive market for baby back ribs in the United States. The second figure shows the situation at Premium Standard Farm in Kansas, one of the many U.S. farms supplying these ribs.
Now assume that the United States imposes a ban on European meat in response to the foot-and-mouth disease that has infected livestock in Europe. (Which the United States did several years ago.) In particular, suppose that the U.S. ban decreases the supply by 40 tons a year. Using the first figure, show the impact of this ban on the baby back rib market. Using the second figure, show the impact on Premium Standard Farm in Kansas. (Essay)
4.8/5 (86)
(86)  -In the above figure, if the price is P1 and the firm produced Q1, the firm's economic profit is ________ than if it produced Q2 and ________ than if it produced Q3.
 (Multiple Choice)
4.9/5 (72)
(72) A perfectly competitive firm maximizes its profits by producing the amount of output such that
(Multiple Choice)
4.9/5 (81)
(81) Suppose firms in a perfectly competitive market are earning an economic profit. As new firms enter, the price ________ and the economic profit of each existing firm ________.
(Multiple Choice)
4.7/5 (75)
(75) 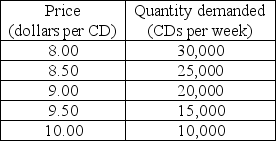
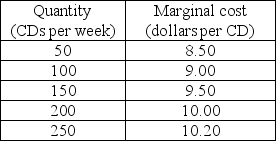 -The first table shows the market demand schedule for CDs, and the second table shows the cost structure of each firm. The CD market is perfectly competitive and there are 100 identical firms. The market price of a CD is ________, and ________ CDs are produced and sold.
 (Multiple Choice)
4.8/5 (77)
(77) A perfectly competitive firm maximizes its profit by producing the level of output so that its average total cost equals the market price.
(True/False)
4.8/5 (67)
(67)  -Fast Copy is a perfectly competitive firm. The figure above shows Fast Copy's cost curves. The current market price is 2 cents per page. With no change in demand and technology, in the long run, the price will
 (Multiple Choice)
4.8/5 (76)
(76) Suppose firms in a perfectly competitive market are incurring an economic loss. Over time
(Multiple Choice)
4.8/5 (69)
(69) Jane's Copy Services is in perfect competition. Jane currently charges 10 cents per page, which is the going market price. Jane thinks that she can increase her profit if she lowers her price to 8 cents per page to increase the demand for her service. Is Jane right? Why or why not?
(Essay)
4.8/5 (79)
(79) If the price of its product just equals the average variable cost of production for a competitive firm,
(Multiple Choice)
4.7/5 (80)
(80) In perfect competition, each individual firm faces ________ demand curve.
(Multiple Choice)
4.9/5 (79)
(79)
-The figure above shows a typical perfectly competitive corn farm, whose marginal cost curve is MC and average total cost curve is ATC. The market is initially in a long-run equilibrium, where the price is $3.00 per bushel. Then, the market demand for corn decreases and, in the short run, the price falls to $2.50 per bushel. In the new short-run equilibrium, the farm
-The figure above shows a typical perfectly competitive corn farm, whose marginal cost curve is MC and average total cost curve is ATC. The market is initially in a long-run equilibrium, where the price is $3.00 per bushel. Then, the market demand for corn decreases and, in the short run, the price falls to $2.50 per bushel. In the new short-run equilibrium, the farm (Multiple Choice)
4.9/5 (80)
(80)  -In the above figure, the firm's total economic profit is equal to
 (Multiple Choice)
5.0/5 (63)
(63)  -In the above figure, below what minimum price will a perfectly competitive firm shut down rather than produce?
 (Multiple Choice)
4.9/5 (69)
(69) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)