



 Chat with AI
Exam 12: Perfect Competition

Exam 1: What Is Economics479 Questions
Exam 2: The Economic Problem440 Questions
Exam 3: Demand and Supply515 Questions
Exam 4: Elasticity533 Questions
Exam 5: Efficiency and Equity450 Questions
Exam 6: Government Actions in Markets412 Questions
Exam 7: Global Markets in Action200 Questions
Exam 8: Utility and Demand364 Questions
Exam 9: Possibilities, Preferences, and Choices459 Questions
Exam 10: Organizing Production385 Questions
Exam 11: Output and Costs493 Questions
Exam 12: Perfect Competition487 Questions
Exam 13: Monopoly599 Questions
Exam 14: Monopolistic Competition319 Questions
Exam 15: Oligopoly276 Questions
Exam 16: Public Choices, Public Goods, and Healthcare205 Questions
Exam 17: Externalities437 Questions
Exam 18: Markets for Factors of Production382 Questions
Exam 19: Economic Inequality353 Questions
Exam 20: Uncertainty and Information233 Questions
Select questions type


Because the demand for a perfectly competitive firm's product is perfectly elastic, marginal revenue is equal to
(Multiple Choice)
4.7/5  (80)
(80) In a perfectly competitive market that is in long-run equilibrium, a permanent leftward shift in the market demand curve
(Multiple Choice)
4.8/5 (81)
(81)  -The figure above shows the marginal revenue and costs of a perfectly competitive firm. The firm's profit is maximized when the firm produces
 (Multiple Choice)
4.8/5 (68)
(68) 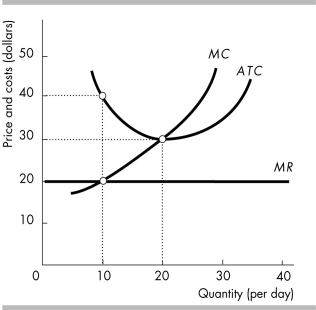 -The figure above shows a perfectly competitive firm. In the short run, the firm will shut down
 (Multiple Choice)
4.8/5 (84)
(84) Which of the following is NOT an assumption of perfect competition?
(Multiple Choice)
4.8/5 (78)
(78) The market for maple syrup is perfectly competitive. Suppose that the market is in long-run equilibrium when the market demand for maple syrup increases. After the demand increases, a typical firm will
(Multiple Choice)
4.9/5 (93)
(93) 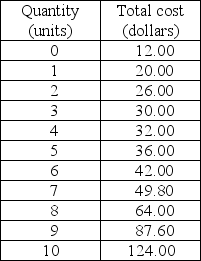 -Acme is a perfectly competitive firm. It has the total cost schedule given in the above table. Acme's product sells for $8.00 per unit. What amount of output is the most profitable and what is Acme's economic profit or economic loss?
 (Essay)
4.8/5 (82)
(82)  -The figure above shows the costs for the typical grower in the perfectly competitive turnip market. Currently, the price of a ton of turnips is $1,200. The demand for turnips increases permanently. The turnip industry experiences neither external economies nor external diseconomies. In the long run, the price of a ton of turnips ________.
 (Multiple Choice)
4.9/5 (73)
(73) If a perfectly competitive firm finds that it is producing an amount of output such that MR > MC and P > AVC, it will
(Multiple Choice)
4.8/5 (81)
(81) 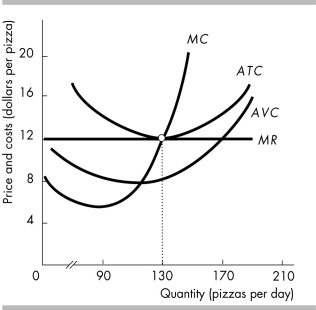 -If the price is $12 per pizza, the perfectly competitive firm in the above figure is
 (Multiple Choice)
4.9/5 (75)
(75) All along the beach in San Diego, California are shops which rent boogie boards by the hour. Tourists perceive that all rental boogie boards are identical, all prices are clearly listed on signs in front of the shops, and there are no restrictions on entry and exit in the boogie board market. What type of market is the boogie board market?
(Multiple Choice)
4.8/5 (56)
(56) The market for maple syrup is perfectly competitive. Suppose that the market is in long-run equilibrium when the market demand for maple syrup increases. What happens in the short run?
(Multiple Choice)
4.8/5 (76)
(76) In a perfectly competitive market, if a firm finds it is producing an amount of output such that its marginal cost exceeds its price, it will
(Multiple Choice)
4.8/5 (69)
(69)  -In the above figure, the line represented by the "4" is the
 (Multiple Choice)
4.8/5 (86)
(86) All along the beach in San Diego, California are shops which rent boogie boards by the hour. Tourists perceive that all rental boogie boards are identical, all prices are clearly listed on signs in front of the shops, and there are no restrictions on entry and exit in the boogie board market. Suppose Surf's Up is a boogie board rental shop. What is the shape of Surf's Up's demand curve as compared to the market demand curve?
(Multiple Choice)
4.9/5 (96)
(96) When do new firms enter a perfectly competitive market? When does entry stop?
(Essay)
4.9/5 (73)
(73) In the long-run equilibrium for a perfectly competitive market
(Multiple Choice)
4.9/5 (73)
(73) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)