



 Chat with AI
Exam 12: Perfect Competition

Exam 1: What Is Economics479 Questions
Exam 2: The Economic Problem440 Questions
Exam 3: Demand and Supply515 Questions
Exam 4: Elasticity533 Questions
Exam 5: Efficiency and Equity450 Questions
Exam 6: Government Actions in Markets412 Questions
Exam 7: Global Markets in Action200 Questions
Exam 8: Utility and Demand364 Questions
Exam 9: Possibilities, Preferences, and Choices459 Questions
Exam 10: Organizing Production385 Questions
Exam 11: Output and Costs493 Questions
Exam 12: Perfect Competition487 Questions
Exam 13: Monopoly599 Questions
Exam 14: Monopolistic Competition319 Questions
Exam 15: Oligopoly276 Questions
Exam 16: Public Choices, Public Goods, and Healthcare205 Questions
Exam 17: Externalities437 Questions
Exam 18: Markets for Factors of Production382 Questions
Exam 19: Economic Inequality353 Questions
Exam 20: Uncertainty and Information233 Questions
Select questions type


 -Based on the table above which shows Chip's costs, if Chip shuts down in the short run, his economic loss will be
 (Multiple Choice)
4.8/5  (84)
(84) 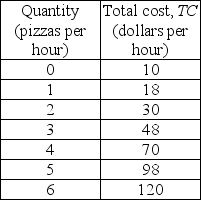 -Giuseppe's Pizza is a perfectly competitive firm. The firm's costs are shown in the table above. If the market price is $15, the firm will
 (Multiple Choice)
4.8/5 (85)
(85) New reports indicate that eating turnips helps people remain healthy. The news shifts the demand curve for turnips rightward. In response, new farms enter the turnip industry. During the period in which the new farms are entering, the price of a turnip ________ and the economic profit of each existing firm ________.
(Multiple Choice)
4.8/5 (80)
(80) Pumpkin growing is a perfectly competitive industry. Suppose that pumpkin growers are all incurring an economic loss. What happens as time passes? What is the long-run equilibrium outcome?
(Essay)
4.8/5 (69)
(69) A firm's shutdown point is the output and price at which the firm just covers its
(Multiple Choice)
4.9/5 (75)
(75) 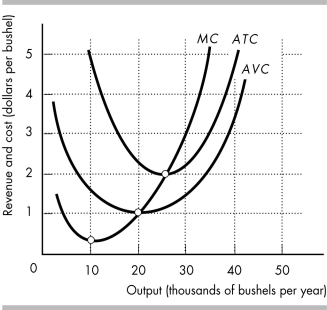 -The above diagram shows the cost curves for a perfectly competitive wheat farmer. At what price(s) does the wheat farmer make an economic profit? Make zero economic profit? Incur an economic loss? How many bushels of wheat does the farmer produce if the price is $3 per bushel? If the price is $0.50 per bushel?
 (Essay)
4.9/5 (83)
(83)  -If the market for maple syrup is perfectly competitive, then in the long-run equilibrium, firms are
 (Multiple Choice)
4.8/5 (81)
(81)  -John keeps beehives and sells 100 quarts of honey per month. The honey market is perfectly competitive, and the price of a quart of honey is $10. John has an average variable cost of $5 and an average fixed cost of $3. At 100 quarts per month, John's marginal cost is $10.
a) Is John maximizing his profit? If not, what should John do?
b) Calculate John's total revenue, total cost, and total economic profit or economic loss when he produces 100 quarts of honey.
-John keeps beehives and sells 100 quarts of honey per month. The honey market is perfectly competitive, and the price of a quart of honey is $10. John has an average variable cost of $5 and an average fixed cost of $3. At 100 quarts per month, John's marginal cost is $10.
a) Is John maximizing his profit? If not, what should John do?
b) Calculate John's total revenue, total cost, and total economic profit or economic loss when he produces 100 quarts of honey. (Essay)
5.0/5 (75)
(75)  -The feature of the above figure that indicates that the firm is a perfectly competitive firm is the
 (Multiple Choice)
4.8/5 (76)
(76) Does a perfectly competitive producer have any incentive to undercut the current market price? Explain your answer
(Essay)
4.9/5 (74)
(74) In the long run, a perfectly competitive firm can make an economic profit because its marginal cost equals its average total cost.
(True/False)
4.9/5 (85)
(85) If the market price is less than a perfectly competitive firm's average total cost, what sort of profit or loss is the firm making?
(Essay)
4.8/5 (91)
(91) A perfectly competitive firm maximizes its profit by producing the output at which its marginal cost equals its
(Multiple Choice)
4.9/5 (82)
(82) "Higher ethanol production definitely and directly raises the price of corn," said USDA economist Ephraim Leibtag. In the long run in the corn market, what is TRUE if the production of ethanol increases?
(Multiple Choice)
4.9/5 (87)
(87) The market for fish is perfectly competitive. So, the price elasticity of demand for fish from a single fishing boat
(Multiple Choice)
4.9/5 (78)
(78) "A perfectly competitive firm will shut down if the price falls below its average total cost." Do you agree? Explain.
(Essay)
4.9/5 (83)
(83) A perfectly competitive firm's short-run supply curve is the same as its
(Multiple Choice)
4.7/5 (88)
(88) Suppose firms in a perfectly competitive industry are making economic profits. As a result I. new firms enter the industry.
II) the market price falls.
III) the economic profits of the existing firms decrease.
(Multiple Choice)
4.9/5 (83)
(83) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)