



 Chat with AI
Exam 9: Application: International Trade

Exam 1: Ten Principles of Economics220 Questions
Exam 2: Thinking Like an Economist284 Questions
Exam 3: Interdependence and the Gains From Trade192 Questions
Exam 4: The Market Forces of Supply and Demand277 Questions
Exam 5: Elasticity and Its Application222 Questions
Exam 6: Supply, Demand, and Government Policies321 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets218 Questions
Exam 8: Applications: The Costs of Taxation203 Questions
Exam 9: Application: International Trade214 Questions
Exam 10: Externalities204 Questions
Exam 11: Public Goods and Common Resources182 Questions
Exam 12: The Design of the Tax System225 Questions
Exam 13: The Costs of Production261 Questions
Exam 14: Firms in Competitive Markets243 Questions
Exam 15: Monopoly231 Questions
Exam 16: Monopolistic Competition246 Questions
Exam 17: Oligopoly204 Questions
Exam 18: The Markets for the Factors of Production232 Questions
Exam 19: Earnings and Discrimination230 Questions
Exam 20: Income Inequality and Poverty194 Questions
Exam 21: The Theory of Consumer Choice209 Questions
Exam 22: Frontiers in Microeconomics185 Questions
Exam 23: Measuring a Nations Income231 Questions
Exam 24: Measuring the Cost of Living214 Questions
Exam 25: Production and Growth187 Questions
Exam 26: Saving, Investment, and the Financial System225 Questions
Exam 27: Tools of Finance198 Questions
Exam 28: Unemployment and Its Natural Rate361 Questions
Exam 29: The Monetary System210 Questions
Exam 30: Money Growth and Inflation201 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts194 Questions
Exam 32: A Macroeconomic Theory of the Open Economy188 Questions
Exam 33: Aggregate Demand and Aggregate Supply189 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand207 Questions
Exam 35: The Short-Run Tradeoff Between Inflation and Unemployment223 Questions
Exam 36: Six Debates Over Macroeconomic Policy154 Questions
Select questions type


There are only increases in total surplus when a country exports a good, since more units of the country's output of that good are produced.
(True/False)
4.8/5  (81)
(81) The results of a 2008 Los Angeles Times poll suggest that the percentage of Americans who believe trade is harmful to the economy exceeds the percentage of Americans who believe trade is beneficial to the economy.
(True/False)
4.7/5 (96)
(96) Figure 9-4 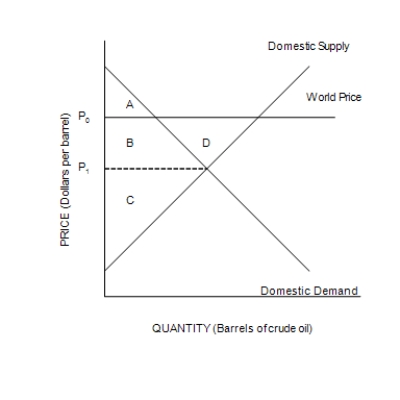 -Refer to Figure 9-4. Total surplus in this market after trade is
 (Multiple Choice)
4.8/5 (86)
(86) Figure 9-7
The following diagram shows the domestic demand and domestic supply curves in a market. 
-Refer to Figure 9-7. With no trade allowed, how much are consumer surplus, producer surplus, and total surplus in this market?
-Refer to Figure 9-7. With no trade allowed, how much are consumer surplus, producer surplus, and total surplus in this market? (Essay)
4.9/5 (74)
(74) The results of a 2008 Los Angeles Times poll suggest that a significant majority of Americans believe that free international trade helps the American economy.
(True/False)
5.0/5 (79)
(79) The world price of cotton is the highest price of cotton observed anywhere in the world.
(True/False)
4.9/5 (81)
(81) Suppose that Australia imposes a tariff on imported beef. If the increase in producer surplus is $100 million, the increase in tariff revenue is $200 million, and the reduction in consumer surplus is $500 million, the deadweight loss of the tariff is $300 million.
(True/False)
4.9/5 (68)
(68) Figure 9-10
The following diagram shows the domestic demand and domestic supply curves in a market. Assume that the world price in this market is $1 per unit. 
-Refer to Figure 9-10. Suppose the country imposes a $1 per unit tariff. If the country allows trade with a tariff, how much is the deadweight loss caused by the tariff?
-Refer to Figure 9-10. Suppose the country imposes a $1 per unit tariff. If the country allows trade with a tariff, how much is the deadweight loss caused by the tariff? (Short Answer)
4.8/5 (89)
(89) Figure 9-3  -Refer to Figure 9-3. The size of the tariff on roses is
 (Multiple Choice)
4.7/5 (83)
(83) Imposing a quota on the import of a good is preferable to a tariff because a tariff creates a deadweight loss while a quota does not.
(True/False)
4.9/5 (74)
(74) The small-economy assumption is necessary to analyze the gains and losses from international trade.
(True/False)
4.9/5 (82)
(82) Import quotas and tariffs make domestic sellers better off and domestic buyers worse off.
(True/False)
4.8/5 (77)
(77) Figure 9-5  -Refer to Figure 9-5. Consumer surplus in this market after trade is
 (Multiple Choice)
4.9/5 (73)
(73) Scenario 9-2
Suppose domestic demand and domestic supply in a market are given by the following equations: =20-P =P
-Refer to Scenario 9-2. Suppose the world price in this market is $8 per unit, and suppose the country imposes a $1 per unit tariff. If the country allows trade with a tariff, how much is the deadweight loss caused by the tariff?
(Essay)
4.9/5 (78)
(78) For Country A, the world price of textiles exceeds the domestic equilibrium price of textiles. As a result, international trade allows sellers of textiles in Country A to experience greater producer surplus than they otherwise would experience.
(True/False)
4.8/5 (79)
(79) William and Jamal live in the country of Dumexia. When Dumexia legalized international trade in bananas, the price of bananas in Dumexia increased. As a result, William became better off and Jamal became worse off. It follows that William is a seller, and Jamal is a buyer, of bananas.
(True/False)
4.8/5 (75)
(75) Figure 9-3
-Refer to Figure 9-3. The imposition of a tariff on roses
-Refer to Figure 9-3. The imposition of a tariff on roses (Multiple Choice)
4.8/5 (86)
(86) Figure 9-6  -When a country that imported a particular good abandons a free-trade policy and adopts a no-trade policy,
 (Multiple Choice)
4.8/5 (80)
(80) Figure 9-10
The following diagram shows the domestic demand and domestic supply curves in a market. Assume that the world price in this market is $1 per unit.
-Refer to Figure 9-10. Suppose the country imposes a $1 per unit tariff. If the country allows trade with a tariff, how much are consumer surplus and producer surplus?
-Refer to Figure 9-10. Suppose the country imposes a $1 per unit tariff. If the country allows trade with a tariff, how much are consumer surplus and producer surplus? (Essay)
4.8/5 (82)
(82) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)