



 Chat with AI
Exam 21: Production and Costs

Exam 1: What Economics Is About174 Questions
Exam 2: Production Possibilities Frontier Framework156 Questions
Exam 3: Supply and Demand Theory224 Questions
Exam 4: Prices Free Controlled and Relative122 Questions
Exam 5: Supply Demand and Price Applications76 Questions
Exam 6: Macroeconomic Measurements Part I Prices and Unemployment151 Questions
Exam 7: Macroeconomic Measurements Part II Gdp and Real Gdp150 Questions
Exam 8: Aggregate Demand and Aggregate Supply204 Questions
Exam 9: Classical Macroeconomics and the Self Regulating Economy172 Questions
Exam 10: Keynesian Macroeconomics and Economic Instability a Critique of the Self Regulating Economy200 Questions
Exam 11: Fiscal Policy and the Federal Budget167 Questions
Exam 12: Money Banking and the Financial System150 Questions
Exam 13: The Federal Reserve System180 Questions
Exam 14: Money and the Economy150 Questions
Exam 15: Monetary Policy185 Questions
Exam 16: Expectations Theory and the Economy150 Questions
Exam 17: Economic Growth Resources Technology Ideas and Institutions103 Questions
Exam 18: Debates in Macroeconomics Over the Role and Effects of Government100 Questions
Exam 19: Elasticity204 Questions
Exam 20: Consumer Choice and Behavioral Economics179 Questions
Exam 21: Production and Costs245 Questions
Exam 22: Perfect Competition187 Questions
Exam 23: Monopoly195 Questions
Exam 24: Monopolistic Competition Oligopoly and Game Theory172 Questions
Exam 25: Government and Product Markets Antitrust and Regulation158 Questions
Exam 26: Factor Markets With Emphasis on the Labor Market184 Questions
Exam 27: Wages Unions and Labor138 Questions
Exam 28: The Distribution of Income and Poverty99 Questions
Exam 29: Interest Rent and Profit198 Questions
Exam 30: Market Failure Externalities Public Goods and Asymmetric Information187 Questions
Exam 31: Public Choice and Special Interest Group Politics135 Questions
Exam 32: Building Theories to Explain Everyday Life From Observations to Questions to Theories to Predictions62 Questions
Exam 33: International Trade152 Questions
Exam 34: International Finance122 Questions
Exam 35: The Economic Case for and Against Government Five Topics Considered87 Questions
Exam 36: Stocks Bonds Futures and Options110 Questions
Select questions type


At 1,000 units of output, total cost is $42,000 and total variable cost is $34,000. At 1,000 units of output, what is the value of average total cost, average variable cost, and average fixed cost, respectively?
(Multiple Choice)
4.8/5  (86)
(86) If the quantity of output rises as more of a variable input is added to a fixed input,
(Multiple Choice)
4.9/5 (77)
(77) The marginal physical product (MPP) of a variable input is
(Multiple Choice)
4.8/5 (85)
(85) Exhibit 21-8
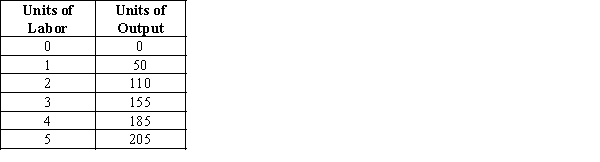 -Exhibit 21-8 shows how output varies with the only variable input used in its production. If the cost of a unit of labor is $500, what is the approximate marginal cost of the 185th unit of output?
 (Multiple Choice)
4.8/5 (87)
(87) Exhibit 21-14
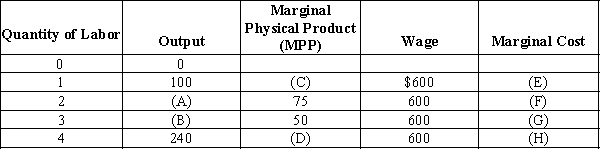 Assume that labor is the only variable input and that each additional laborer is paid $600.
-Refer to Exhibit 21-14. What is the level of output with 2 and 3 laborers working [blanks (A) and (B)], respectively?
Assume that labor is the only variable input and that each additional laborer is paid $600.
-Refer to Exhibit 21-14. What is the level of output with 2 and 3 laborers working [blanks (A) and (B)], respectively? (Multiple Choice)
4.8/5 (81)
(81) The law of diminishing marginal returns holds for a situation in which
(Multiple Choice)
4.8/5 (66)
(66) Exhibit 21-3
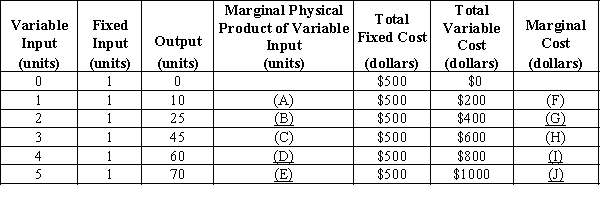 -Refer to Exhibit 21-3. The average variable cost of producing 45 units of output is
 (Multiple Choice)
4.8/5 (92)
(92) "As additional units of a variable input are added to a fixed input, eventually the marginal physical product of the variable input will decline." This is a statement of the
(Multiple Choice)
4.9/5 (80)
(80) Five months ago Wilson opened up a health club. Which of the following is an implicit cost related to the health club?
(Multiple Choice)
4.9/5 (84)
(84) Describe the difference between market coordination and managerial coordination. Give an example of each to support your answer.
(Essay)
4.9/5 (66)
(66) An economist might say, "The market guides and coordinates individuals' actions." Which of the following is an example of this happening?
(Multiple Choice)
4.8/5 (78)
(78) As the marginal physical product of a variable input __________, the marginal cost __________.
(Multiple Choice)
4.7/5 (87)
(87) As long as there are __________ costs, __________ profit will be greater than __________ profit.
(Multiple Choice)
4.9/5 (76)
(76) If marginal cost is rising, average total cost must also be rising.
(True/False)
4.8/5 (99)
(99) Exhibit 21-13
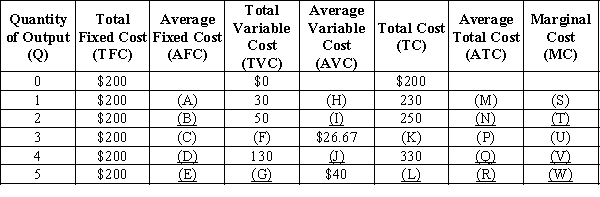 -Refer to Exhibit 21-13. What dollar amounts go in blanks (G) and (H), respectively?
 (Multiple Choice)
4.9/5 (71)
(71) Economies of scale, constant returns to scale and diseconomies of scale account for the shape of the __________ cost curve.
(Multiple Choice)
4.9/5 (84)
(84) Economists Alchian and Demsetz suggest that firms are formed when
(Multiple Choice)
4.7/5 (75)
(75) 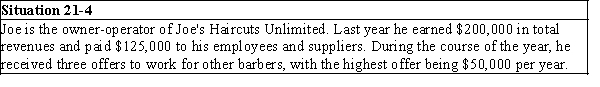 -Refer to Situation 21-4. What are Joe's accounting profits?
 (Multiple Choice)
4.8/5 (74)
(74) Exhibit 21-4
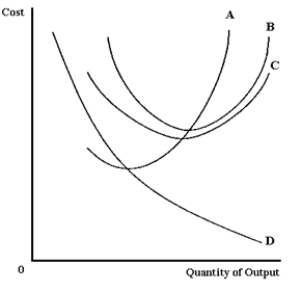 -Refer to Exhibit 21-4. Curve B is a(n) __________ cost curve.
 (Multiple Choice)
4.8/5 (73)
(73) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)