



 Chat with AI
Exam 15: Long-Term Liabilities

Exam 1: Accounting in Action220 Questions
Exam 2: The Recording Process192 Questions
Exam 3: Adjusting the Accounts216 Questions
Exam 4: Completing the Accounting Cycle203 Questions
Exam 5: Accounting for Merchandising Operations221 Questions
Exam 6: Inventories204 Questions
Exam 7: Accounting Information Systems139 Questions
Exam 8: Fraud, Internal Control, and Cash212 Questions
Exam 9: Accounting for Receivables220 Questions
Exam 10: Plant Assets, Natural Resources, and Intangible Assets293 Questions
Exam 11: Current Liabilities and Payroll Accounting207 Questions
Exam 12: Accounting for Partnerships210 Questions
Exam 13: Corporations: Organization and Capital Stock Transactions195 Questions
Exam 14: Corporations: Dividends, Retained Earnings, and Income Reporting176 Questions
Exam 15: Long-Term Liabilities215 Questions
Exam 16: Investments178 Questions
Exam 17: Statement of Cash Flows203 Questions
Exam 18: Financial Analysis: the Big Picture225 Questions
Exam 19: Managerial Accounting197 Questions
Exam 20: Job Order Costing199 Questions
Exam 21: Process Costing198 Questions
Exam 22: Cost-Volume-Profit217 Questions
Exam 23: Incremental Analysis208 Questions
Exam 24: Budgetary Planning207 Questions
Exam 25: Budgetary Control and Responsibility Accounting207 Questions
Exam 26: Standard Costs and Balanced Scorecard221 Questions
Select questions type


When authorizing bonds to be issued, the board of directors does not specify the
(Multiple Choice)
4.8/5  (80)
(80) On January 1, Cleopatra Corporation issued $3,000,000, 14%, 5-year bonds with interest payable on December 31. The bonds sold for $3,216,288. The market rate of interest for these bonds was 12%. On the first interest date, using the effective-interest method, the debit entry to Bond Interest Expense is for
(Multiple Choice)
4.8/5 (75)
(75) On January 1, 2010, Beltway Enterprises issued 9%, 5-year bonds with a face amount of $700,000 at par. Interest is payable semiannually on June 30 and December 31.
Instructions
Prepare the entries to record the issuance of the bonds and the first semiannual interest payment.
(Essay)
4.9/5 (90)
(90) Stover Corporation reports the following amounts in their 2010 financial statements: 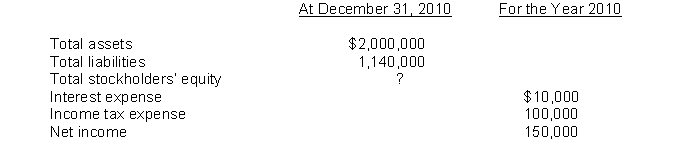 Instructions
(a) Compute the December 31, 2010, balance in stockholders' equity.
(b) Compute the debt to total assets ratio at December 31, 2010.
(c) Compute times interest earned for 2010.
Instructions
(a) Compute the December 31, 2010, balance in stockholders' equity.
(b) Compute the debt to total assets ratio at December 31, 2010.
(c) Compute times interest earned for 2010. (Essay)
4.7/5 (80)
(80) Presented below are three independent situations:
(a) Howell Corporation purchased $350,000 of its bonds on June 30, 2010, at 102 and immediately retired them. The carrying value of the bonds on the retirement date was $339,500. The bonds pay semiannual interest and the interest payment due on June 30, 2010, has been made and recorded.
(b) Justice, Inc. purchased $400,000 of its bonds at 97 on June 30, 2010, and immediately retired them. The carrying value of the bonds on the retirement date was $393,000. The bonds pay semiannual interest and the interest payment due on June 30, 2010, has been made and recorded.
(c) Riser Company has $80,000, 10%, 12-year convertible bonds outstanding. These bonds were sold at face value and pay semiannual interest on June 30 and December 31 of each year. The bonds are convertible into 40 shares of Riser $5 par value common stock for each $1,000 par value bond. On December 31, 2010, after the bond interest has been paid, $20,000 par value of bonds were converted. The market value of Riser's common stock was $38 per share on December 31, 2010.
Instructions
For each of the independent situations, prepare the journal entry to record the retirement or conversion of the bonds.
(Essay)
4.8/5 (78)
(78) A lease where the intent is temporary use of the property by the lessee with continued ownership of the property by the lessor is called
(Multiple Choice)
4.7/5 (71)
(71) $2 million, 8%, 10-year bonds are issued at face value. Interest will be paid semi-annually. When calculating the market price of the bond, the present value of
(Multiple Choice)
4.8/5 (83)
(83) The board of directors of Gibson Corporation is considering two plans for financing the purchase of new plant equipment. Plan #1 would require the issuance of $4,000,000, 6%, 20-year bonds at face value. Plan #2 would require the issuance of 100,000 shares of $5 par value common stock which is selling for $40 per share on the open market. Gibson Corporation currently has 100,000 shares of common stock outstanding and the income tax rate is expected to be 30%. Assume that income before interest and income taxes is expected to be $500,000 if the new factory equipment is purchased.
Instructions
Prepare a schedule which shows the expected net income after taxes and the earnings per share on common stock under each of the plans that the board of directors is considering.
(Essay)
5.0/5 (72)
(72) A $1,000 face value bond with a quoted price of 97 is selling for
(Multiple Choice)
5.0/5 (92)
(92) If sixty $1,000 convertible bonds with a carrying value of $69,000 are converted into 9,000 shares of $5 par value common stock, the journal entry to record the conversion is 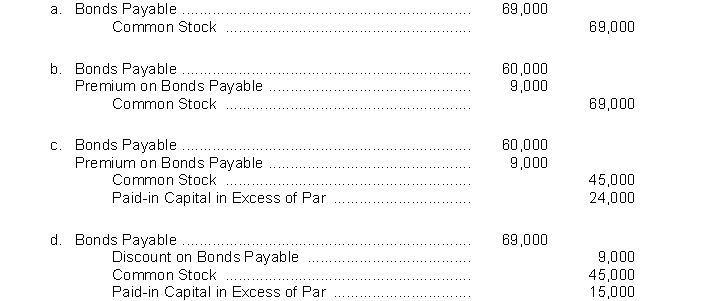
(Short Answer)
4.8/5 (77)
(77) S-A E 217
Bonds may be redeemed (retired) before maturity by the issuing corporation. Explain why a company would decide to retire bonds before maturity and the necessary steps to record the redemption.
(Essay)
4.9/5 (88)
(88) When there is a ________________ difference between the straight-line and effective-interest methods of amortization, the ________________ method is required under GAAP.
(Short Answer)
5.0/5 (96)
(96) Hoffman Corporation retires its bonds at 106 on January 1, following the payment of semi-annual interest. The face value of the bonds is $600,000. The carrying value of the bonds at the redemption date is $629,700. The entry to record the redemption will include a
(Multiple Choice)
4.8/5 (82)
(82) Gains and losses are not recognized when convertible bonds are converted into common stock.
(True/False)
4.8/5 (86)
(86) The holder of a convertible bond can convert an interest payment received into a cash dividend paid on common stock if the dividend is greater than the interest payment.
(True/False)
5.0/5 (76)
(76) Investors who receive checks in their names for interest paid on bonds must hold
(Multiple Choice)
5.0/5 (75)
(75) Discount on bonds is an additional cost of borrowing and should be recorded as interest expense over the life of the bonds.
(True/False)
4.9/5 (89)
(89) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)