



 Chat with AI
Exam 14: Long-Term Liabilities

Exam 1: Financial Accounting and Accounting Standards103 Questions
Exam 2: Conceptual Framework for Financial Reporting155 Questions
Exam 3: The Accounting Information System144 Questions
Exam 4: Income Statement and Related Information139 Questions
Exam 5: Balance Sheet and Statement of Cash Flows127 Questions
Exam 6: Accounting and the Time Value of Money152 Questions
Exam 7: Cash and Receivables173 Questions
Exam 8: Valuation of Inventories: a Cost-Basis Approach173 Questions
Exam 9: Inventories: Additional Valuation Issues168 Questions
Exam 10: Acquisition and Disposition of Property, Plant, and Equipment170 Questions
Exam 11: Depreciation, Impairments, and Depletion156 Questions
Exam 12: Intangible Assets171 Questions
Exam 13: Current Liabilities and Contingencies170 Questions
Exam 14: Long-Term Liabilities140 Questions
Exam 15: Stockholders Equity155 Questions
Exam 16: Dilutive Securities and Earnings Per Share160 Questions
Exam 17: Investments141 Questions
Exam 18: Revenue Recognition145 Questions
Exam 19: Accounting for Income Taxes127 Questions
Exam 20: Accounting for Pensions and Postretirement Benefits137 Questions
Exam 21: Accounting for Leases128 Questions
Exam 22: Accounting Changes and Error Analysis103 Questions
Exam 23: Statement of Cash Flows143 Questions
Exam 24: Full Disclosure in Financial Reporting108 Questions
Exam 25: Appendix89 Questions
Select questions type


Cortez Company issues $4,000,000 face value of bonds at 96 on January 1, 2013. The bonds are dated January 1, 2013, pay interest semiannually at 8% on June 30 and December 31, and mature in 10 years. Straight-line amortization is used for discounts and premiums. On September 1, 2016, $2,400,000 of the bonds are called at 102 plus accrued interest. What gain or loss would be recognized on the called bonds on September 1, 2016?
(Multiple Choice)
4.7/5  (75)
(75) Which of the following must be disclosed relative to long-term debt maturities and sinking fund requirements?
(Multiple Choice)
4.8/5 (75)
(75) The replacement of an existing bond issue with a new one is called refunding.
(True/False)
4.8/5 (86)
(86) A company issues $20,000,000, 7.8%, 20-year bonds to yield 8% on January 1, 2014. Interest is paid on June 30 and December 31. The proceeds from the bonds are $19,604,144. What is interest expense for 2015, using straight-line amortization?
(Multiple Choice)
4.7/5 (82)
(82) Which of the following is not a difference between IFRS and U.S. GAAP in accounting for non-current liabilities?
(Multiple Choice)
4.9/5 (87)
(87) Use the following information for questions 60 through 62:
On January 1, 2014, Ellison Co. issued eight-year bonds with a face value of $4,000,000 and a stated interest rate of 6%, payable semiannually on June 30 and December 31. The bonds were sold to yield 8%. Table values are: 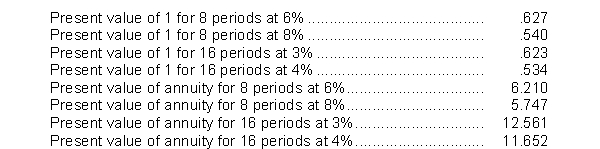 -The present value of the interest is
 (Multiple Choice)
4.9/5 (97)
(97) A debt instrument with no ready market is exchanged for property whose fair value is currently indeterminable. When such a transaction takes place
(Multiple Choice)
4.8/5 (89)
(89) The term used for bonds that are unsecured as to principal is
(Multiple Choice)
4.9/5 (79)
(79) Use the following information for questions *103 through *105:
On December 31, 2012, Nolte Co. is in financial difficulty and cannot pay a note due that day. It is a $1,800,000 note with $180,000 accrued interest payable to Piper, Inc. Piper agrees to accept from Nolte equipment that has a fair value of $870,000, an original cost of $1,440,000, and accumulated depreciation of $690,000. Piper also forgives the accrued interest, extends the maturity date to December 31, 2015, reduces the face amount of the note to $750,000, and reduces the interest rate to 6%, with interest payable at the end of each year.
-Nolte should recognize a gain on the partial settlement and restructure of the debt of
(Multiple Choice)
4.8/5 (87)
(87) On January 1, 2014, Ann Price loaned $112,695 to Joe Kiger. A zero-interest-bearing note (face amount, $150,000) was exchanged solely for cash; no other rights or privileges were exchanged. The note is to be repaid on December 31, 2016. The prevailing rate of interest for a loan of this type is 10%. The present value of $150,000 at 10% for three years is $112,695. What amount of interest income should Ms. Price recognize in 2014?
(Multiple Choice)
5.0/5 (88)
(88) All of the following are differences between IFRS and U.S. GAAP in accounting for liabilities except:
(Multiple Choice)
5.0/5 (84)
(84) At the beginning of 2014, Wallace Corporation issued 10% bonds with a face value of $3,000,000. These bonds mature in the five years, and interest is paid semiannually on June 30 and December 31. The bonds were sold for $2,779,200 to yield 12%. Wallace uses a calendar-year reporting period. Using the effective-interest method of amortization, what amount of interest expense should be reported for 2014? (Round your answer to the nearest dollar.)
(Multiple Choice)
4.7/5 (76)
(76) A company issues $20,000,000, 7.8%, 20-year bonds to yield 8% on January 1, 2014. Interest is paid on June 30 and December 31. The proceeds from the bonds are $19,604,144. Using effective-interest amortization, how much interest expense will be recognized in 2014?
(Multiple Choice)
4.9/5 (70)
(70) Bond issue costs are capitalized as a deferred charge and amortized to expense over the life of the bond issue.
(True/False)
4.9/5 (74)
(74) Bond discount amortization.On June 1, 2013, Everly Bottle Company sold $2,000,000 in long-term bonds for $1,754,200. The bonds will mature in 10 years and have a stated interest rate of 8% and a yield rate of 10%. The bonds pay interest annually on May 31 of each year. The bonds are to be accounted for under the effective-interest method.
Instructions
(a) Construct a bond amortization table for this problem to indicate the amount of interest expense and discount amortization at each May 31. Include only the first four years. Make sure all columns and rows are properly labeled. (Round to the nearest dollar.)(b) The sales price of $1,754,200 was determined from present value tables. Specifically explain how one would determine the price using present value tables.
(c) Assuming that interest and discount amortization are recorded each May 31, prepare the adjusting entry to be made on December 31, 2015. (Round to the nearest dollar.)
(Essay)
4.8/5 (73)
(73) If a company chooses the fair value option, a decrease in the fair value of the liability is recorded by crediting
(Multiple Choice)
4.7/5 (74)
(74) On January 1, 2010, Goll Corp. issued 2,000 of its 10%, $1,000 bonds for $2,080,000. These bonds were to mature on January 1, 2020 but were callable at 101 any time after December 31, 2013. Interest was payable semiannually on July 1 and January 1. OnJuly 1, 2015, Goll called all of the bonds and retired them. Bond premium was amortized on a straight-line basis. Before income taxes, Goll's gain or loss in 2015 on this early extinguishment of debt was
(Multiple Choice)
4.9/5 (78)
(78) Use the following information for questions 29 and 30:
Fox Co. issued $100,000 of ten-year, 10% bonds that pay interest semiannually. The bonds are sold to yield 8%.
-One step in calculating the issue price of the bonds is to multiply the principal by the table value for
(Multiple Choice)
4.9/5 (89)
(89) Everhart Company issues $20,000,000, 6%, 5-year bonds dated January 1, 2014 on January 1, 2014. The bonds pay interest semiannually on June 30 and December 31. The bonds are issued to yield 5%. What are the proceeds from the bond issue? 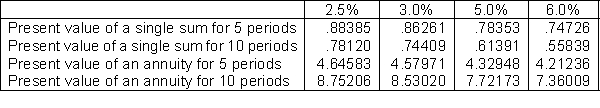
(Multiple Choice)
4.9/5 (83)
(83) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)