



 Chat with AI
Exam 14: Long-Term Liabilities

Exam 1: Financial Accounting and Accounting Standards103 Questions
Exam 2: Conceptual Framework for Financial Reporting155 Questions
Exam 3: The Accounting Information System144 Questions
Exam 4: Income Statement and Related Information139 Questions
Exam 5: Balance Sheet and Statement of Cash Flows127 Questions
Exam 6: Accounting and the Time Value of Money152 Questions
Exam 7: Cash and Receivables173 Questions
Exam 8: Valuation of Inventories: a Cost-Basis Approach173 Questions
Exam 9: Inventories: Additional Valuation Issues168 Questions
Exam 10: Acquisition and Disposition of Property, Plant, and Equipment170 Questions
Exam 11: Depreciation, Impairments, and Depletion156 Questions
Exam 12: Intangible Assets171 Questions
Exam 13: Current Liabilities and Contingencies170 Questions
Exam 14: Long-Term Liabilities140 Questions
Exam 15: Stockholders Equity155 Questions
Exam 16: Dilutive Securities and Earnings Per Share160 Questions
Exam 17: Investments141 Questions
Exam 18: Revenue Recognition145 Questions
Exam 19: Accounting for Income Taxes127 Questions
Exam 20: Accounting for Pensions and Postretirement Benefits137 Questions
Exam 21: Accounting for Leases128 Questions
Exam 22: Accounting Changes and Error Analysis103 Questions
Exam 23: Statement of Cash Flows143 Questions
Exam 24: Full Disclosure in Financial Reporting108 Questions
Exam 25: Appendix89 Questions
Select questions type


Another step in calculating the issue price of the bonds is to
(Multiple Choice)
4.9/5  (78)
(78) IFRS generally assumes that all restructurings be accounted for as:
(Multiple Choice)
4.9/5 (77)
(77) Under IFRS the required procedure for amortization of a discount or premium is the effective-interest method.
(True/False)
5.0/5 (84)
(84) On January 1, Martinez Inc. issued $5,000,000, 11% bonds for $5,325,000. The market rate of interest for these bonds is 10%. Interest is payable annually on December 31. Martinez uses the effective-interest method of amortizing bond premium. At the end of the first year, Martinez should report unamortized bond premium of:
(Multiple Choice)
5.0/5 (80)
(80) Didde Company issues $20,000,000 face value of bonds at 96 on January 1, 2013. The bonds are dated January 1, 2013, pay interest semiannually at 8% on June 30 and December 31, and mature in 10 years. Straight-line amortization is used for discounts and premiums. On September 1, 2016, $12,000,000 of the bonds are called at 102 plus accrued interest. What gain or loss would be recognized on the called bonds on September 1, 2016?
(Multiple Choice)
5.0/5 (83)
(83) If bonds are issued between interest dates, the entry on the books of the issuing corporation could include a
(Multiple Choice)
4.9/5 (90)
(90) Paige Co. took advantage of market conditions to refund debt. This was the fourth refunding operation carried out by Paige within the last three years. The excess of the carrying amount of the old debt over the amount paid to extinguish it should be reported as a
(Multiple Choice)
4.8/5 (73)
(73) On January 1, 2015, Doty Co. redeemed its 15-year bonds of $5,000,000 par value for 102. They were originally issued on January 1, 2003 at 98 with a maturity date ofJanuary 1, 2018. The bond issue costs relating to this transaction were $300,000. Doty amortizes discounts, premiums, and bond issue costs using the straight-line method. What amount of loss should Doty recognize on the redemption of these bonds (ignore taxes)?
(Multiple Choice)
4.9/5 (91)
(91) When a business enterprise enters into what is referred to as off-balance-sheet financing, the company
(Multiple Choice)
4.8/5 (96)
(96) If a company plans to retire long-term debt from a bond retirement fund, it should report the debt as current.
(True/False)
4.9/5 (81)
(81) IFRS requires the use of straight-line method for amortization of a discount or premium.
(True/False)
4.8/5 (76)
(76) If bonds are initially sold at a discount and the straight-line method of amortization is used, interest expense in the earlier years will
(Multiple Choice)
4.9/5 (85)
(85) On January 1, 2015, Piper Co. issued ten-year bonds with a face value of $3,000,000 and a stated interest rate of 10%, payable semiannually on June 30 and December 31. The bonds were sold to yield 12%. Table values are: 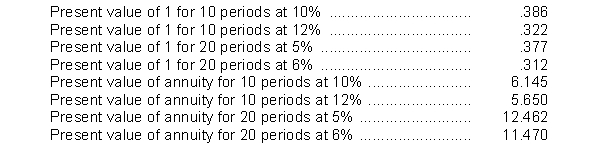 Instructions
(a) Calculate the issue price of the bonds.
(b) Without prejudice to your solution in part
(a), assume that the issue price was $2,652,000. Prepare the amortization table for 2015, assuming that amortization is recorded on interest payment dates using the effective-interest method.
Instructions
(a) Calculate the issue price of the bonds.
(b) Without prejudice to your solution in part
(a), assume that the issue price was $2,652,000. Prepare the amortization table for 2015, assuming that amortization is recorded on interest payment dates using the effective-interest method. (Essay)
4.8/5 (72)
(72) A corporation borrowed money from a bank to build a building. The long-term note signed by the corporation is secured by a mortgage that pledges title to the building as security for the loan. The corporation is to pay the bank $80,000 each year for 10 years to repay the loan. Which of the following relationships can you expect to apply to the situation?
(Multiple Choice)
4.9/5 (86)
(86) Prepare journal entries to record the following transactions relating to long-term bonds of Kirby, Inc. (Show computations.)(a) On June 1, 2013, Kirby, Inc. issued $5,000,000, 6% bonds for $4,897,000, which includes accrued interest. Interest is payable semiannually on February 1 and August 1 with the bonds maturing on February 1, 2023. The bonds are callable at 102.(b) On August 1, 2013, Kirby paid interest on the bonds and recorded amortization. Kirby uses straight-line amortization.(c) On February 1, 2015, Kirby paid interest and recorded amortization on all of the bonds, and purchased $3,000,000 of the bonds at the call price. Assume that a reversing entry was made on January 1, 2015.
(Essay)
4.9/5 (74)
(74) In a troubled debt restructuring in which the debt is continued with modified terms and the carrying amount of the debt is less than the total future cash flows,
(Multiple Choice)
4.9/5 (79)
(79) On January 1, 2014, Jacobs Company sold property to Dains Company which originally cost Jacobs $1,330,000. There was no established exchange price for this property. Danis gave Jacobs a $2,100,000 zero-interest-bearing note payable in three equal annual installments of $700,000 with the first payment due December 31, 2014. The note has no ready market. The prevailing rate of interest for a note of this type is 10%. The present value of a $2,100,000 note payable in three equal annual installments of $700,000 at a 10% rate of interest is $1,740,900. What is the amount of interest income that should be recognized by Jacobs in 2014, using the effective-interest method?
(Multiple Choice)
4.9/5 (82)
(82) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)