



 Chat with AI
Exam 14: Long-Term Liabilities

Exam 1: Financial Accounting and Accounting Standards103 Questions
Exam 2: Conceptual Framework for Financial Reporting155 Questions
Exam 3: The Accounting Information System144 Questions
Exam 4: Income Statement and Related Information139 Questions
Exam 5: Balance Sheet and Statement of Cash Flows127 Questions
Exam 6: Accounting and the Time Value of Money152 Questions
Exam 7: Cash and Receivables173 Questions
Exam 8: Valuation of Inventories: a Cost-Basis Approach173 Questions
Exam 9: Inventories: Additional Valuation Issues168 Questions
Exam 10: Acquisition and Disposition of Property, Plant, and Equipment170 Questions
Exam 11: Depreciation, Impairments, and Depletion156 Questions
Exam 12: Intangible Assets171 Questions
Exam 13: Current Liabilities and Contingencies170 Questions
Exam 14: Long-Term Liabilities140 Questions
Exam 15: Stockholders Equity155 Questions
Exam 16: Dilutive Securities and Earnings Per Share160 Questions
Exam 17: Investments141 Questions
Exam 18: Revenue Recognition145 Questions
Exam 19: Accounting for Income Taxes127 Questions
Exam 20: Accounting for Pensions and Postretirement Benefits137 Questions
Exam 21: Accounting for Leases128 Questions
Exam 22: Accounting Changes and Error Analysis103 Questions
Exam 23: Statement of Cash Flows143 Questions
Exam 24: Full Disclosure in Financial Reporting108 Questions
Exam 25: Appendix89 Questions
Select questions type


The cash paid for interest will always be greater than interest expense when using effective-interest amortization for a bond.
(True/False)
5.0/5  (82)
(82) Use the following information for questions *103 through *105:
On December 31, 2012, Nolte Co. is in financial difficulty and cannot pay a note due that day. It is a $1,800,000 note with $180,000 accrued interest payable to Piper, Inc. Piper agrees to accept from Nolte equipment that has a fair value of $870,000, an original cost of $1,440,000, and accumulated depreciation of $690,000. Piper also forgives the accrued interest, extends the maturity date to December 31, 2015, reduces the face amount of the note to $750,000, and reduces the interest rate to 6%, with interest payable at the end of each year.
-Nolte should recognize a gain or loss on the transfer of the equipment of
(Multiple Choice)
4.8/5 (64)
(64) The printing costs and legal fees associated with the issuance of bonds should
(Multiple Choice)
4.8/5 (82)
(82) Under IFRS, all troubled-debt restructurings are accounted for as extinguishments.
(True/False)
4.8/5 (81)
(81) Reich, Inc. issued bonds with a maturity amount of $200,000 and a maturity ten years from date of issue. If the bonds were issued at a premium, this indicates that
(Multiple Choice)
4.9/5 (65)
(65) On its December 31, 2014 balance sheet, Emig Corp. reported bonds payable of $3,000,000 and related unamortized bond issue costs of $160,000. The bonds had been issued at par. On January 2, 2015, Emig retired $1,500,000 of the outstanding bonds at par plus a call premium of $35,000. What amount should Emig report in its 2015 income statement as loss on extinguishment of debt (ignore taxes)?
(Multiple Choice)
4.8/5 (71)
(71) Use the following information for questions 60 through 62:
On January 1, 2014, Ellison Co. issued eight-year bonds with a face value of $4,000,000 and a stated interest rate of 6%, payable semiannually on June 30 and December 31. The bonds were sold to yield 8%. Table values are: 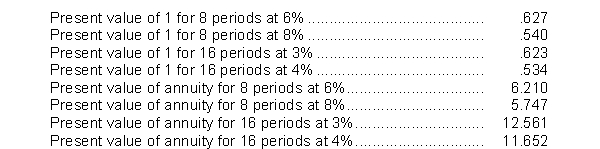 -The present value of the principal is
 (Multiple Choice)
4.8/5 (76)
(76) Long-term debt that matures within one year and is to be converted into stock should be reported
(Multiple Choice)
4.8/5 (85)
(85) "In-substance defeasance" is a term used to refer to an arrangement whereby
(Multiple Choice)
4.9/5 (82)
(82) In a troubled debt restructuring in which the debt is continued with modified terms and the carrying amount of the debt is less than the total future cash flows, the creditor should
(Multiple Choice)
4.8/5 (83)
(83) A company issues $10,000,000, 7.8%, 20-year bonds to yield 8% on January 1, 2014. Interest is paid on June 30 and December 31. The proceeds from the bonds are $9,802,072. What is interest expense for 2015, using straight-line amortization?
(Multiple Choice)
4.9/5 (83)
(83) U.S. GAAP and IFRS have the same accounting guideline for bond issue cost.
(True/False)
4.8/5 (82)
(82) If bonds are issued initially at a premium and the effective-interest method of amortization is used, interest expense in the earlier years will be
(Multiple Choice)
4.7/5 (78)
(78) Prepare the necessary journal entries to record the following transactions relating to the long-term issuance of bonds of Pitts Co.:March 1Issued $3,000,000 face value Pitts Co. second mortgage, 8% bonds for $3,270,600, including accrued interest. Interest is payable semiannually on December 1 and June 1 with the bonds maturing 10 years from this past December 1. The bonds are callable at 102.June 1Paid semiannual interest on Pitts Co. bonds. (Use straight-line amortization of any premium or discount.)December 1Paid semiannual interest on Pitts Co. bonds and purchased $1,500,000 face value bonds at the call price in accordance with the provisions of the bond indenture.
(Essay)
4.8/5 (82)
(82) The interest rate written in the terms of the bond indenture is called the effective yield or market rate.
(True/False)
4.8/5 (83)
(83) Bond interest expense reported on the December 31, 2014 income statement of Bartley Corporation would be
(Multiple Choice)
4.7/5 (65)
(65) Kant Corporation retires its $300,000 face value bonds at 102 on January 1, following the payment of interest. The carrying value of the bonds at the redemption date is $288,750. The entry to record the redemption will include a
(Multiple Choice)
4.9/5 (89)
(89) Which of the following arguments is presented by FASB to explain why a gain is recorded by a company when its creditworthiness is becoming worse?
(Multiple Choice)
4.8/5 (73)
(73) An early extinguishment of bonds payable, which were originally issued at a premium, is made by purchase of the bonds between interest dates. At the time of reacquisition
(Multiple Choice)
4.7/5 (90)
(90) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)