



 Chat with AI
Exam 12: S Corporations

Exam 1: Understanding and Working With the Federal Tax Law71 Questions
Exam 2: Corporations: Introduction and Operating Rules94 Questions
Exam 3: Corporations: Special Situations99 Questions
Exam 4: Corporations: Organization and Capital Structure84 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions114 Questions
Exam 6: Corporations: Redemptions and Liquidations88 Questions
Exam 7: Corporations: Reorganizations86 Questions
Exam 8: Consolidated Tax Returns138 Questions
Exam 9: Taxation of International Transactions163 Questions
Exam 10: Partnerships: Formation, Operation, and Basis122 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations128 Questions
Exam 12: S Corporations135 Questions
Exam 13: Comparative Forms of Doing Business108 Questions
Exam 14: Taxes on the Financial Statements55 Questions
Exam 15: Exempt Entities100 Questions
Exam 16: Multistate Corporate Taxation123 Questions
Exam 17: Tax Practice and Ethics129 Questions
Exam 18: The Federal Gift and Estate Taxes188 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates136 Questions
Select questions type


Advise your client how income, expenses, gain, and losses are allocated to shareholders of an S corporation.
(Essay)
4.8/5  (74)
(74) A calendar year C corporation reports a $41,000 NOL in 2014, but it elects S status for 2015 and generates an NOL of $30,000 in that year. At all times during 2015, the stock of the corporation was owned by the same 10 shareholders, each of whom owned 10% of the stock. Kris, one of the 10 shareholders, holds an S stock basis of $2,300 at the beginning of 2015. How much of the 2015 loss, if any, is deductible by Kris?
(Multiple Choice)
4.7/5 (85)
(85) Chris, the sole shareholder of Taylor, Inc., elects during 2015 to terminate the S election, effective January 1, 2016. As of the end of 2015, Taylor, Inc., holds AAA of $120,000 and OAA of $13,000. Chris receives a cash distribution of $130,000 on January 15, 2016. If his stock basis is $220,000 before the distribution, calculate Chris's taxable amount and his ending stock basis.
(Essay)
4.7/5 (81)
(81) Claude Bergeron sold 1,000 shares of Ditta, Inc., an S corporation, for $12,000. He had owned the stock for three years and had a stock basis of $111,000 in the shares. Claude is single, and he is the original owner of the § 1244 stock shares. Calculate the appropriate tax treatment.
(Multiple Choice)
4.9/5 (81)
(81) An S shareholder's basis is decreased by distributions treated as being paid from AAA.
(True/False)
4.7/5 (75)
(75) A newly formed S corporation does not receive any tax benefit from an NOL incurred in its first tax year.
(True/False)
4.8/5 (86)
(86) The amount of any distribution to an S corporation shareholder is equal to the ____________________ plus the fair market value of any other property distributed.
(Short Answer)
4.9/5 (70)
(70) Gene Grams is a 45% owner of a calendar year S corporation during 2015. His beginning stock basis is $230,000, and the S corporation reports the following items. 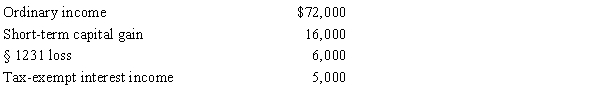
Calculate Grams's stock basis at year-end.
Calculate Grams's stock basis at year-end. (Essay)
4.9/5 (72)
(72) Several individuals acquire assets on behalf of Skip Corporation on May 28, 2015, purchased assets on June 3, 2015, and began business on June 11, 2015. They subscribe to shares of stock, file articles of incorporation for Skip, and become shareholders on June 21, 2015. The S election must be filed no later than 2 1/2 months after:
(Multiple Choice)
4.9/5 (72)
(72) Pepper, Inc., an S corporation, holds a $1 million balance in accumulated E&P. It reports sales revenues of $400,000, taxable interest of $380,000, operating expenses of $250,000, and deductions attributable to the interest income of $140,000. What is Pepper's passive income penalty tax payable, if any?
(Multiple Choice)
4.8/5 (75)
(75) The passive investment income of an S corporation includes gains from the sale of securities.
(True/False)
4.8/5 (81)
(81) What statement is correct with respect to an S corporation?
(Multiple Choice)
4.8/5 (83)
(83) Most limited liability partnerships can own stock in an S corporation.
(True/False)
4.9/5 (70)
(70) Distribution of loss property by an S corporation to a shareholder generally should be _________________.
(Short Answer)
4.9/5 (78)
(78) An S corporation cannot incur a tax liability at the corporation level.
(True/False)
4.7/5 (73)
(73) Any losses that are suspended under the at-risk rules are carried forward and are available during an S corporation's post-termination period.
(True/False)
4.9/5 (79)
(79) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)