



 Chat with AI
Exam 12: S Corporations

Exam 1: Understanding and Working With the Federal Tax Law71 Questions
Exam 2: Corporations: Introduction and Operating Rules94 Questions
Exam 3: Corporations: Special Situations99 Questions
Exam 4: Corporations: Organization and Capital Structure84 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions114 Questions
Exam 6: Corporations: Redemptions and Liquidations88 Questions
Exam 7: Corporations: Reorganizations86 Questions
Exam 8: Consolidated Tax Returns138 Questions
Exam 9: Taxation of International Transactions163 Questions
Exam 10: Partnerships: Formation, Operation, and Basis122 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations128 Questions
Exam 12: S Corporations135 Questions
Exam 13: Comparative Forms of Doing Business108 Questions
Exam 14: Taxes on the Financial Statements55 Questions
Exam 15: Exempt Entities100 Questions
Exam 16: Multistate Corporate Taxation123 Questions
Exam 17: Tax Practice and Ethics129 Questions
Exam 18: The Federal Gift and Estate Taxes188 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates136 Questions
Select questions type


Stock basis first is increased by income items, then ____________________ by distributions, and finally decreased by ____________________.
(Short Answer)
4.9/5  (72)
(72) An S shareholder's stock basis does not include a ratable share of S corporation liabilities.
(True/False)
4.8/5 (70)
(70) Where the S corporation rules are silent, C corporation provisions apply.
(True/False)
4.9/5 (87)
(87) Any excess of S corporation losses or deductions over the shareholder's combined stock and debt basis is suspended until there is a subsequent stock or debt basis.
(True/False)
4.8/5 (82)
(82) It is not beneficial for an S corporation to issue § 1244 stock.
(True/False)
4.9/5 (89)
(89) Tax-exempt income is not separately stated on Schedule K of Form 1120S.
(True/False)
4.9/5 (74)
(74) Tax-exempt income at the S corporation level flows through as taxable to the shareholder.
(True/False)
4.9/5 (55)
(55) An S shareholder's stock basis is reduced by flow-through losses before accounting for distributions.
(True/False)
4.8/5 (75)
(75) An S corporation does not recognize a loss when distributing assets that are worth less than their basis.
(True/False)
4.8/5 (79)
(79) The carryover period for the NOLs of a C corporation does not continue to run during S corporation years.
(True/False)
4.7/5 (84)
(84) Which, if any, of the following items has no effect on the stock basis of an S corporation shareholder?
(Multiple Choice)
4.8/5 (84)
(84) With respect to passive losses, there are three classes of income, losses, and credits: ____________________, ____________________, and passive.
(Essay)
4.9/5 (74)
(74) Any distribution of cash or property by a corporation that does not exceed the balance of AAA with respect to S stock during a post-termination transition period of approximately one year is applied against and reduces the basis of the S stock.
(True/False)
4.9/5 (72)
(72) Compensation for services rendered to an S corporation is subject to FICA taxes.
(True/False)
4.9/5 (58)
(58) The termination of an S election occurs on the day after a corporation ceases to be a qualifying S corporation.
(True/False)
4.8/5 (86)
(86) Which transaction affects the Other Adjustments Account on an S corporation's Schedule M-2?
(Multiple Choice)
4.9/5 (97)
(97) The Schedule M-3 is the same for a C corporation and an S corporation.
(True/False)
4.8/5 (88)
(88) Realized gain is recognized by an S corporation on its distribution of ____________________ property.
(Short Answer)
4.9/5 (85)
(85) Bidden, Inc., a calendar year S corporation, incurred the following items. 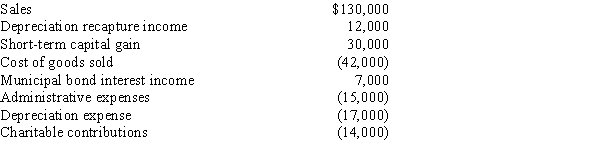
Calculate Bidden's nonseparately computed income.
Calculate Bidden's nonseparately computed income. (Essay)
4.8/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)