



 Chat with AI
Exam 12: S Corporations

Exam 1: Understanding and Working With the Federal Tax Law71 Questions
Exam 2: Corporations: Introduction and Operating Rules94 Questions
Exam 3: Corporations: Special Situations99 Questions
Exam 4: Corporations: Organization and Capital Structure84 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions114 Questions
Exam 6: Corporations: Redemptions and Liquidations88 Questions
Exam 7: Corporations: Reorganizations86 Questions
Exam 8: Consolidated Tax Returns138 Questions
Exam 9: Taxation of International Transactions163 Questions
Exam 10: Partnerships: Formation, Operation, and Basis122 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations128 Questions
Exam 12: S Corporations135 Questions
Exam 13: Comparative Forms of Doing Business108 Questions
Exam 14: Taxes on the Financial Statements55 Questions
Exam 15: Exempt Entities100 Questions
Exam 16: Multistate Corporate Taxation123 Questions
Exam 17: Tax Practice and Ethics129 Questions
Exam 18: The Federal Gift and Estate Taxes188 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates136 Questions
Select questions type


An S corporation shareholder's stock basis includes his or her direct investments plus a ratable share of any corporate liabilities.
(True/False)
4.9/5  (83)
(83) Fred is the sole shareholder of an S corporation in Fort Deposit, Alabama. At a time when his stock basis is $20,000, the corporation distributes appreciated property worth $100,000 (basis of $20,000). Fred's taxable gain is:
(Multiple Choice)
5.0/5 (60)
(60) Four unrelated individuals acquire assets on behalf of Jump Corporation on May 21, 2015, purchased assets on June 5, 2015, and begin doing business on June 15, 2015. They subscribe to shares of stock, file articles of incorporation for Jump, and become shareholders on July 23, 2015. The S election must be filed no later than 2 1/2 months after:
(Multiple Choice)
4.8/5 (81)
(81) A capital loss allocated to a shareholder always reduces the Other Adjustments Account.
(True/False)
4.9/5 (91)
(91) Grams, Inc., a calendar year S corporation is a manufacturer of widgets. Grams reports $20,000 DPGR and $15,000 of wages; its S corporation's QPAI is $5,000. Janet owns a 40% interest in the S corporation. All expenses that reduce DPGR are from wages, and all wages paid relate to DPGR. How much QPAI and wages are allocated to Janet?
(Multiple Choice)
4.9/5 (59)
(59) If an S corporation shareholder's basis in a loan to the entity has been _________________, the shareholder recognizes gross income when the S corporation repays the shareholder.
(Short Answer)
4.7/5 (86)
(86) Any distribution made by an S corporation during a tax year is taken into account before accounting for the year's losses.
(True/False)
4.9/5 (66)
(66) An S shareholder's basis is increased by stock purchases and capital contributions.
(True/False)
4.7/5 (88)
(88) Form 1120S provides an S shareholder's computation of his or her stock basis.
(True/False)
5.0/5 (86)
(86) Mock Corporation converts to S corporation status in 2015. Mock used the LIFO inventory method in 2014 and had a LIFO inventory of $435,000 (FIFO value of $550,000) on the date of the S election. How much tax must be added to Mock's 2014 corporate tax liability, assuming that Mock is subject to a 35% tax rate.
(Multiple Choice)
4.9/5 (83)
(83) The Section 179 expense deduction is a Schedule K item on the Form 1120S.
(True/False)
4.9/5 (82)
(82) You are given the following facts about a solely owned S corporation. What is the shareholder's ending stock basis? 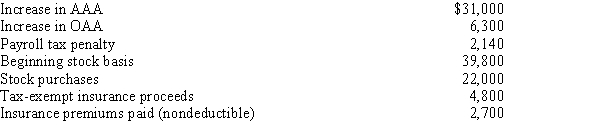
(Multiple Choice)
4.9/5 (85)
(85) A new S corporation shareholder can revoke the S election unilaterally, if he/she owns how much of the existing S corporation's stock?
(Multiple Choice)
4.8/5 (93)
(93) On January 2, 2014, David loans his S corporation $10,000. By the end of 2014 David's stock basis is zero and the basis in his note has been reduced to $8,000. During 2015, the company's operating income is $10,000. The company makes 2015 distributions to David of $11,000. David reports a(n):
(Multiple Choice)
5.0/5 (79)
(79) What method is used to allocate S corporation income or losses (unless an election to the contrary is made)?
(Multiple Choice)
4.8/5 (69)
(69) Non-separately computed loss ____________________ a S shareholder's stock basis.
(Short Answer)
4.9/5 (87)
(87) The LIFO recapture tax is a variation of the passive investment income penalty tax.
(True/False)
4.7/5 (80)
(80) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)