



 Chat with AI
Exam 3: Corporations: Special Situations

Exam 1: Understanding and Working With the Federal Tax Law71 Questions
Exam 2: Corporations: Introduction and Operating Rules94 Questions
Exam 3: Corporations: Special Situations99 Questions
Exam 4: Corporations: Organization and Capital Structure84 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions114 Questions
Exam 6: Corporations: Redemptions and Liquidations88 Questions
Exam 7: Corporations: Reorganizations86 Questions
Exam 8: Consolidated Tax Returns138 Questions
Exam 9: Taxation of International Transactions163 Questions
Exam 10: Partnerships: Formation, Operation, and Basis122 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations128 Questions
Exam 12: S Corporations135 Questions
Exam 13: Comparative Forms of Doing Business108 Questions
Exam 14: Taxes on the Financial Statements55 Questions
Exam 15: Exempt Entities100 Questions
Exam 16: Multistate Corporate Taxation123 Questions
Exam 17: Tax Practice and Ethics129 Questions
Exam 18: The Federal Gift and Estate Taxes188 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates136 Questions
Select questions type


A taxpayer who prepares and sells Mexican food at several of its restaurant locations can qualify for DPAD as to the receipts only from take-out orders and home-delivery sales.

Free
(True/False)
4.9/5  (84)
(84) Correct Answer: Verified
False
Sweet Corporation, a new corporation, has gross receipts of $4.9 million, $6.9 million, and $8.6 million in
2013, 2014, and 2015, respectively. Is this corporation a small corporation with respect to the AMT in years 2013, 2014, 2015, and 2016?
Free
(Essay)
4.8/5 (80)
(80) Correct Answer:Verified
VerifiedYes, Sweet is a small corporation in 2013, the first year, irrespectively of the gross receipts. Yes, for year 2014, because the average gross receipts for the first year do not exceed $5 million. Yes, for year 2015, because the average gross receipts for the first and second years do not exceed $7.5 million [($4.9 million + $6.9 million) = $11.8/2 = $5.9] Yes, for year 2016, because the average gross receipts for the three prior years [($8.6 million + $6.9 million + $4.9 million) = $20.4/3 = $6.8] are less than $ 7.5 million.
One of the components of DPGR is qualified production property (QPP). The QPP must be manufactured, produced, grown, or extracted entirely within the U.S.
Free
(True/False)
4.8/5 (84)
(84) Correct Answer:Verified
VerifiedFalse
The domestic production activities deduction is limited to corporations.
(True/False)
4.9/5 (70)
(70) Which of the following items will be an addition to AMTI in arriving at ACE?
(Multiple Choice)
4.9/5 (77)
(77) Which of the following would not be a positive tax preference item in 2015?
(Multiple Choice)
4.8/5 (94)
(94) Harvey, a real estate developer, pays Abe, a general contractor, to construct an office building. Abe has no DPGR since he does not own the property.
(True/False)
4.7/5 (66)
(66) Ace Corporation incurred the following taxes for the current year: 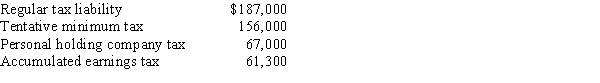 Ace Corporation's total tax liability is:
 (Multiple Choice)
4.7/5 (83)
(83) Mayberry, Inc. engages in production activities that generate QPAI of $460,000 and taxable income (without taking into account the DPAD and NOL) of $600,000 in 2015. The company also has an NOL carryover to 2015 of $500,000 and qualified W-2 wages of $300,000. Calculate any DPAD.
(Short Answer)
4.8/5 (85)
(85) The AMT exemption amount of $40,000 phases out entirely once a corporation's average gross receipts exceeds $310,000.
(True/False)
4.9/5 (78)
(78) A small corporation with unused minimum tax credits may use what percentage of regular tax as a minimum credit in 2015?
(Multiple Choice)
4.9/5 (70)
(70) If QPAI cannot be used in any one year due to the TI limitation, it can be carried over for 3 years.
(True/False)
4.9/5 (75)
(75) Gerbil Corporation was formed in 2005. If in 2015, it has average gross receipts of under $7.5 million, the company cannot be subject to the AMT.
(True/False)
4.9/5 (86)
(86) Once a small corporation for AMT purposes, always a small corporation.
(True/False)
4.9/5 (80)
(80) What amount of accumulated earnings of a service type corporation is considered within the reasonable needs of a business without the corporation having to show a bona fide business reason for the accumulation?
(Multiple Choice)
4.8/5 (82)
(82) In 2015, May Corporation (a calendar year taxpayer) had the following transactions: 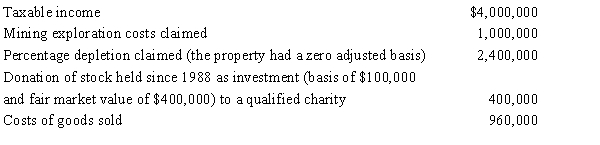 For 2015, May Corporation's AMTI is:
 (Multiple Choice)
4.9/5 (85)
(85) Reasonable needs for purposes of the accumulated earnings tax do not include loans to shareholders.
(True/False)
4.8/5 (80)
(80) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)