



 Chat with AI
Exam 35: Agriculture

Exam 1: Accounting Regulation and the Conceptual Framework21 Questions
Exam 2: Application of Accounting Theory30 Questions
Exam 3: Fair Value Measurement29 Questions
Exam 4: Inventories30 Questions
Exam 5: Property, Plant and Equipment27 Questions
Exam 6: Intangible Assets24 Questions
Exam 7: Impairment of Assets23 Questions
Exam 8: Provisions, Contingent Liabilities and Contingent Assets27 Questions
Exam 9: Employee Benefits28 Questions
Exam 10: Leases24 Questions
Exam 11: Financial Instruments21 Questions
Exam 12: Income Taxes22 Questions
Exam 13: Share Capital and Reserves29 Questions
Exam 14: Share-Based Payment24 Questions
Exam 15: Revenue23 Questions
Exam 16: Presentation of Financial Statements25 Questions
Exam 17: Statement of Cash Flows29 Questions
Exam 18: Accounting Policies and Other Disclosures14 Questions
Exam 19: Earnings Per Share19 Questions
Exam 20: Operating Segments20 Questions
Exam 21: Related Party Disclosures27 Questions
Exam 22: Sustainability and Corporate Social Responsibility Reporting17 Questions
Exam 23: Foreign Currency Transactions and Forward Exchange Contracts20 Questions
Exam 24: Translation of Foreign Currency Financial Statements18 Questions
Exam 25: Business Combinations23 Questions
Exam 26: Consolidation: Controlled Entities40 Questions
Exam 27: Consolidation: Wholly Owned Entities48 Questions
Exam 28: Consolidation: Intragroup Transactions40 Questions
Exam 29: Consolidation: Non-Controlling Interest51 Questions
Exam 30: Consolidation: Other Issues28 Questions
Exam 31: Associates and Joint Ventures26 Questions
Exam 32: Joint Arrangements26 Questions
Exam 33: Insolvency and Liquidation40 Questions
Exam 34: Accounting for Mineral Resources24 Questions
Exam 35: Agriculture27 Questions
Select questions type


Rural Co received a $100 000 grant from the government on 1 July 2013. One of the conditions attached to the grant was the Rural Co had to continue farming in the same location for the next 2 years, otherwise the grant would have to be retuned in full.
The entry to record the receipt of the grant is:
(Multiple Choice)
4.9/5  (89)
(89) Increases in fair value over cost in relation to land used for agricultural purposes is recognised in equity when the land is:
(Multiple Choice)
4.9/5 (70)
(70) AASB 141/IAS 41 requires that biological assets be measured:
(Multiple Choice)
4.8/5 (82)
(82) Which of the following is NOT considered to be agricultural produce?
(Multiple Choice)
4.8/5 (83)
(83) Cow Co is a company that farms dairy cattle. Cow Co owns the farmland on which the cattle are located, having purchased it for $1.5 million in 2011. The land is measured at cost under AASB 116/IAS 16.
Details of cattle at 30 June 2013 were as follows:
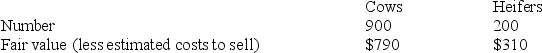 During the year ended 30 June 2014 the following occurred:
200 new cows were purchased at $810 each
50 heifers matured into cows
5 heifers died
100 cows were sold for $830 each
The price change between a heifer and a cow at the time of maturity during the year was estimated to be $500
The following is relevant at 30 June 2014:
The land has been valued at $5.6 million
Fair value less estimated costs to sell are as follows (Cow Co has determined that these are the appropriate fair values to use for the purposes of transfers and deaths of heifers):
Cows - $860 /head
Heifers - $340/head
The fair value of cows as at 30 June 2014 is:
During the year ended 30 June 2014 the following occurred:
200 new cows were purchased at $810 each
50 heifers matured into cows
5 heifers died
100 cows were sold for $830 each
The price change between a heifer and a cow at the time of maturity during the year was estimated to be $500
The following is relevant at 30 June 2014:
The land has been valued at $5.6 million
Fair value less estimated costs to sell are as follows (Cow Co has determined that these are the appropriate fair values to use for the purposes of transfers and deaths of heifers):
Cows - $860 /head
Heifers - $340/head
The fair value of cows as at 30 June 2014 is: (Multiple Choice)
4.9/5 (65)
(65) Fishy Co operates a fish farm. AASB 141/IAS 41 requires live immature fish to be valued at:
(Multiple Choice)
4.8/5 (76)
(76) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)