



 Chat with AI
Exam 15: Revenue

Exam 1: Accounting Regulation and the Conceptual Framework21 Questions
Exam 2: Application of Accounting Theory30 Questions
Exam 3: Fair Value Measurement29 Questions
Exam 4: Inventories30 Questions
Exam 5: Property, Plant and Equipment27 Questions
Exam 6: Intangible Assets24 Questions
Exam 7: Impairment of Assets23 Questions
Exam 8: Provisions, Contingent Liabilities and Contingent Assets27 Questions
Exam 9: Employee Benefits28 Questions
Exam 10: Leases24 Questions
Exam 11: Financial Instruments21 Questions
Exam 12: Income Taxes22 Questions
Exam 13: Share Capital and Reserves29 Questions
Exam 14: Share-Based Payment24 Questions
Exam 15: Revenue23 Questions
Exam 16: Presentation of Financial Statements25 Questions
Exam 17: Statement of Cash Flows29 Questions
Exam 18: Accounting Policies and Other Disclosures14 Questions
Exam 19: Earnings Per Share19 Questions
Exam 20: Operating Segments20 Questions
Exam 21: Related Party Disclosures27 Questions
Exam 22: Sustainability and Corporate Social Responsibility Reporting17 Questions
Exam 23: Foreign Currency Transactions and Forward Exchange Contracts20 Questions
Exam 24: Translation of Foreign Currency Financial Statements18 Questions
Exam 25: Business Combinations23 Questions
Exam 26: Consolidation: Controlled Entities40 Questions
Exam 27: Consolidation: Wholly Owned Entities48 Questions
Exam 28: Consolidation: Intragroup Transactions40 Questions
Exam 29: Consolidation: Non-Controlling Interest51 Questions
Exam 30: Consolidation: Other Issues28 Questions
Exam 31: Associates and Joint Ventures26 Questions
Exam 32: Joint Arrangements26 Questions
Exam 33: Insolvency and Liquidation40 Questions
Exam 34: Accounting for Mineral Resources24 Questions
Exam 35: Agriculture27 Questions
Select questions type


Which of the following items are defined in AASB 118?

Free
(Multiple Choice)
4.8/5  (78)
(78) Correct Answer: Verified
B
TelCo provides a bundled service offering to a customer for $3000 upfront. The services provided are as follows:
Upfront advice
'on-call' advice
Database access for a 2-year period
If TelCo were to charge a separate fee for each service if sold separately the fee would be:
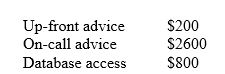 Using the relative fair value approach the amount of revenue recognised in relation to the on-call advice is:
Free
(Multiple Choice)
4.8/5 (75)
(75) Correct Answer:Verified
VerifiedC
The two elements of performance referred to in the conceptual framework are:
Free
(Multiple Choice)
4.8/5 (83)
(83) Correct Answer:Verified
VerifiedD
Easter Pty Ltd operates a facility making chocolate Easter eggs. Easter has a policy that all unsold chocolate eggs can be returned for a full refund within 1 week of Easter Sunday. On 1 March 2014, Easter sold 500 pallets of packaged eggs at $100 per pallet. Historical data indicates that 20% of the stock will be returned for a refund. Within one month of Easter Sunday (by the end of April 2014) 10% of the eggs were retuned for refund. Using the expected sales approach, how much revenue would be recognised by Easter at the end of April 2014?
(Multiple Choice)
4.8/5 (69)
(69) The effect that IFRIC Interpretation titled Agreements for the Construction of Real Estate will have the following effect for entities that undertake off-the-plan real estate sales is that:
(Multiple Choice)
4.8/5 (64)
(64) The introduction of IFRIC 13 Customer Loyalty Programmes had the following impact on revenue recognition policies for entities in the airline industry:
(Multiple Choice)
5.0/5 (84)
(84) Which of the following disclosures are required under AASB 118?
I - Total income, allocated between revenue and other gains.
II - The accounting policies adopted for revenue recognition.
III - The amount of each significant category of revenue recognised during the period.
IV - The amount of revenue arising from exchanges of goods and services.
(Multiple Choice)
4.9/5 (73)
(73) Which of the following are excluded from the scope of AASB 118?
I The initial recognition of agricultural produce.
II Insurance contracts within the scope of AASB 4.
III The extraction of mineral ores.
IV Lease agreements.
(Multiple Choice)
4.8/5 (90)
(90) The following information relates to SellIT:
5000 units of stock were sold for $10 per unit
The cost of that stock to SellIT was $4.50 per unit
Other costs incurred during the period totalled $10 000
Proceeds on sale of an item of plant during the period was $2000
The carrying amount of the plant at the date of disposal was $500.
SellIT would recognise the following amount as revenue for the period:
(Multiple Choice)
4.8/5 (73)
(73) Which of the following is NOT excluded from the scope of AASB 118 Revenue?
(Multiple Choice)
4.9/5 (69)
(69) Which of the following is NOT an example of an entity retaining significant risks and rewards of ownership?
(Multiple Choice)
4.8/5 (77)
(77) When consideration is deferred and there is a below-market rate of interest charged the fair value of the consideration should be determined:
(Multiple Choice)
4.8/5 (75)
(75) Which of the following is NOT an example of an agency arrangement where the selling entity would recognise revenue on a net basis?
(Multiple Choice)
4.9/5 (80)
(80) Orange Pty Ltd develops and sells off-the-shelf accounting software packages. The retail price of each package is $399 (GST inclusive). Included with each purchase are 'free' upgrades for a period of 12 months after the date of purchase. These upgrades can be purchased separately for $80 (GST inclusive).
At the date of purchase of the software package by a customer, Orange should record revenue of:
(Multiple Choice)
5.0/5 (85)
(85) TelCo provides a bundled service offering to a customer for $3000 upfront. The services provided are as follows:
Upfront advice
'on-call' advice
Database access for a 2-year period
If TelCo were to charge a separate fee for each service if sold separately the fee would be:
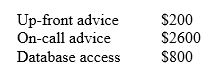 The revenue that would be recorded by TelCo at the inception of the agreement is:
 (Multiple Choice)
4.9/5 (84)
(84) Which of the following is NOT a condition that needs to be satisfied prior to recognising revenue from the rendering of services using the 'percentage of completion' method?
(Multiple Choice)
4.8/5 (86)
(86) In terms of revenue related disclosures on the face of the statement of profit or loss and other comprehensive income:
(Multiple Choice)
5.0/5 (90)
(90) The IFRS 15 Revenue from Contracts with Customers is inconsistent with the principles within which of the following?
(Multiple Choice)
4.9/5 (86)
(86) On 1 July 2010 ABC Ltd purchased a 5-year $1000 5% debenture for $957.88. The current market rate of interest is 6%. The maturity date is 30 June 2015. Interest is payable annually on 30 June.
The interest income that ABC would recognise for the year ended 30 June 2011 is:
(Multiple Choice)
4.8/5 (68)
(68) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)