



 Chat with AI
Exam 11: Financial Instruments

Exam 1: Accounting Regulation and the Conceptual Framework21 Questions
Exam 2: Application of Accounting Theory30 Questions
Exam 3: Fair Value Measurement29 Questions
Exam 4: Inventories30 Questions
Exam 5: Property, Plant and Equipment27 Questions
Exam 6: Intangible Assets24 Questions
Exam 7: Impairment of Assets23 Questions
Exam 8: Provisions, Contingent Liabilities and Contingent Assets27 Questions
Exam 9: Employee Benefits28 Questions
Exam 10: Leases24 Questions
Exam 11: Financial Instruments21 Questions
Exam 12: Income Taxes22 Questions
Exam 13: Share Capital and Reserves29 Questions
Exam 14: Share-Based Payment24 Questions
Exam 15: Revenue23 Questions
Exam 16: Presentation of Financial Statements25 Questions
Exam 17: Statement of Cash Flows29 Questions
Exam 18: Accounting Policies and Other Disclosures14 Questions
Exam 19: Earnings Per Share19 Questions
Exam 20: Operating Segments20 Questions
Exam 21: Related Party Disclosures27 Questions
Exam 22: Sustainability and Corporate Social Responsibility Reporting17 Questions
Exam 23: Foreign Currency Transactions and Forward Exchange Contracts20 Questions
Exam 24: Translation of Foreign Currency Financial Statements18 Questions
Exam 25: Business Combinations23 Questions
Exam 26: Consolidation: Controlled Entities40 Questions
Exam 27: Consolidation: Wholly Owned Entities48 Questions
Exam 28: Consolidation: Intragroup Transactions40 Questions
Exam 29: Consolidation: Non-Controlling Interest51 Questions
Exam 30: Consolidation: Other Issues28 Questions
Exam 31: Associates and Joint Ventures26 Questions
Exam 32: Joint Arrangements26 Questions
Exam 33: Insolvency and Liquidation40 Questions
Exam 34: Accounting for Mineral Resources24 Questions
Exam 35: Agriculture27 Questions
Select questions type


All of the following would be regarded as financial instruments except:

Free
(Multiple Choice)
4.7/5  (89)
(89) Correct Answer: Verified
D
Company A issued convertible notes 3 years ago and accounted for them as a compound financial instrument. Complete the following:
At the end of the three year period the portion of the XXX component that relates to the notes which have been converted XXX.
Free
(Multiple Choice)
4.8/5 (81)
(81) Correct Answer:Verified
VerifiedC
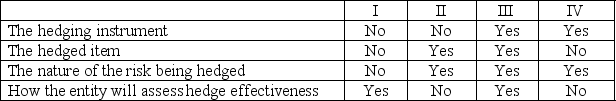
The formal documentation of a hedging relationship must include identification of:
Free
(Multiple Choice)
4.9/5 (70)
(70) Correct Answer:Verified
VerifiedC
The appropriate accounting treatment for incremental costs directly attributable to an equity transaction that would otherwise have been avoided is to:
(Multiple Choice)
4.7/5 (83)
(83) Company A has convertible notes on issue. These notes are convertible to ordinary shares of the Company after 3 years. The distributions made to the note holders by Company A are classified by Company A as follows:
(Multiple Choice)
4.7/5 (97)
(97) A financial asset classified as fair value through profit or loss (FVTPL) must be:
I - A derivative that is a financial guarantee contract or a hedging instrument.
II - Acquired principally for the purpose of selling it in the near term.
III - Part of a portfolio of identified instrument that are managed together and for which there is evidence of a recent actual pattern of short-term profit-taking.
IV - Designated as such upon initial recognition.
(Multiple Choice)
4.7/5 (89)
(89) When an entity has a legally enforceable right to set off the recognised amounts of a financial asset and financial liability and it intends to settle on a net basis, it:
(Multiple Choice)
4.8/5 (88)
(88) Which of the following are regarded as financial instruments:
I - Deposits held by a financial institution.
II - Ordinary shares.
III - Raw materials inventories.
IV - Property, plant and equipment.
V - Accounts receivable and accounts payable.
(Multiple Choice)
4.9/5 (84)
(84) The classification of a financial instrument on the statement of financial position of an entity is governed by the principle of:
(Multiple Choice)
4.8/5 (72)
(72) Which of the following categories of financial instruments is NOT subsequently measured at amortised cost?
(Multiple Choice)
4.8/5 (86)
(86) A financial liability classified as fair value through profit or loss must be:
I - A derivative (except for a derivative that is a financial guarantee contract or a hedging instrument).
II - Acquired principally for the purpose of selling it in the near term.
III - Part of a portfolio of identified financial instruments that are managed together and for which there is evidence of a recent actual pattern of short-term profit-taking.
IV - Designated as such upon initial recognition.
(Multiple Choice)
4.8/5 (83)
(83) AASB 139 Financial Instruments: Recognition and Measurement, requires that 'held-to-maturity' investments be initially measured at:
(Multiple Choice)
4.9/5 (81)
(81) Which of the following is excluded from the scope of AASB 139?
(Multiple Choice)
4.8/5 (86)
(86) Which of the following is NOT an example of a derivative financial instrument?
(Multiple Choice)
4.8/5 (88)
(88) Which of the following events provide objective evidence that a financial asset has been
Impaired:
I - A default in interest payments.
II - The borrower enters into bankruptcy.
III - Significant financial difficulty of the issuer.
IV - The downgrade of an entity's credit rating.
(Multiple Choice)
4.9/5 (75)
(75) The definition of a derivative requires which of the following characteristics to be met?
I - Its value must change in response to a change in an underlying variable such as a specified interest rate, price or foreign exchange rate.
II - It must be settled on a net basis.
III - It must require no initial net investment or an additional net investment that is smaller than would be required for other types of contracts with similar responses to changes in market factors.
IV - It is to be settled at a future date.
(Multiple Choice)
4.9/5 (78)
(78) Callas Corporation Limited buys an option that entitles it to purchase 2000 shares in Maria Limited at $5 per share at any time in the next 3 months. The derivative financial instrument in this transaction is the:
(Multiple Choice)
4.8/5 (78)
(78) Company A issues preference shares to Company B, the terms of which entitle party B to redeem the preference shares for cash if Company A's revenues fall below a specified level. From Company A's perspective the preference shares are:
(Multiple Choice)
4.7/5 (89)
(89) The risk that one party to a financial instrument will fail to discharge an obligation and cause the other party to incur a financial loss is referred to as:
(Multiple Choice)
4.8/5 (85)
(85) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)