



 Chat with AI
Exam 9: Employee Benefits

Exam 1: Accounting Regulation and the Conceptual Framework21 Questions
Exam 2: Application of Accounting Theory30 Questions
Exam 3: Fair Value Measurement29 Questions
Exam 4: Inventories30 Questions
Exam 5: Property, Plant and Equipment27 Questions
Exam 6: Intangible Assets24 Questions
Exam 7: Impairment of Assets23 Questions
Exam 8: Provisions, Contingent Liabilities and Contingent Assets27 Questions
Exam 9: Employee Benefits28 Questions
Exam 10: Leases24 Questions
Exam 11: Financial Instruments21 Questions
Exam 12: Income Taxes22 Questions
Exam 13: Share Capital and Reserves29 Questions
Exam 14: Share-Based Payment24 Questions
Exam 15: Revenue23 Questions
Exam 16: Presentation of Financial Statements25 Questions
Exam 17: Statement of Cash Flows29 Questions
Exam 18: Accounting Policies and Other Disclosures14 Questions
Exam 19: Earnings Per Share19 Questions
Exam 20: Operating Segments20 Questions
Exam 21: Related Party Disclosures27 Questions
Exam 22: Sustainability and Corporate Social Responsibility Reporting17 Questions
Exam 23: Foreign Currency Transactions and Forward Exchange Contracts20 Questions
Exam 24: Translation of Foreign Currency Financial Statements18 Questions
Exam 25: Business Combinations23 Questions
Exam 26: Consolidation: Controlled Entities40 Questions
Exam 27: Consolidation: Wholly Owned Entities48 Questions
Exam 28: Consolidation: Intragroup Transactions40 Questions
Exam 29: Consolidation: Non-Controlling Interest51 Questions
Exam 30: Consolidation: Other Issues28 Questions
Exam 31: Associates and Joint Ventures26 Questions
Exam 32: Joint Arrangements26 Questions
Exam 33: Insolvency and Liquidation40 Questions
Exam 34: Accounting for Mineral Resources24 Questions
Exam 35: Agriculture27 Questions
Select questions type


Carpenter Ltd has 6 employees, who are each paid $750 per week for a 5 day working week. Each employee is entitled to 8 days accumulating non-vesting sick leave per year.
At 1 July 2013 the accumulated untaken leave was 14 days in total. During the year ended 30 June 2014 a total of 50 days sick leave was taken, of which 12 days were unpaid leave.
Of the accumulated untaken leave at 30 June 2014 it is estimated that 75% of it will be taken during the following year.
The balance of the provision for sick leave at 30 June 2014 is:

Free
(Multiple Choice)
4.8/5  (92)
(92) Correct Answer: Verified
C
Determining an entity's liability for long service leave requires estimation of:
Free
(Multiple Choice)
4.9/5 (76)
(76) Correct Answer:Verified
VerifiedD
AASB 119 requires an entity to record a liability for long service leave:
Free
(Multiple Choice)
4.8/5 (84)
(84) Correct Answer:Verified
VerifiedB
AASB 119 adopts which method to determining long service leave obligations?
(Multiple Choice)
4.9/5 (77)
(77) The nominal value of an accumulated benefit for long service leave is calculated as (Years of employment/Years required for LSL) x (weeks of paid leave/52) x _______.
(Multiple Choice)
4.8/5 (86)
(86) Pirate Ltd employs 5 staff. Each staff member is entitled to 20 days annual leave per annum. Leave loading of 17.5% is paid when the leave is taken. At 1 July 2013 the balance in the provision for annual leave account was $20 303.
Details of each employee's leave entitlement at 30 June 2014 are as follows:
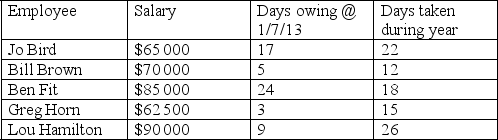 There are 260 work days in a year. On 1 July each year all employees receive a 5% wage rise. There are no other wage rises given during the year.
The closing balance in the provision for annual leave account at 30 June 2014 is:
There are 260 work days in a year. On 1 July each year all employees receive a 5% wage rise. There are no other wage rises given during the year.
The closing balance in the provision for annual leave account at 30 June 2014 is: (Multiple Choice)
4.8/5 (78)
(78) Pirate Ltd employs 5 staff. Each staff member is entitled to 20 days annual leave per annum. Leave loading of 17.5% is paid when the leave is taken. At 1 July 2013 the balance in the provision for annual leave account was $20 303.
Details of each employee's leave entitlement at 30 June 2014 are as follows:
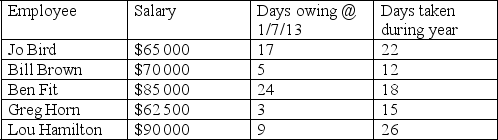 There are 260 work days in a year. On 1 July each year all employees receive a 5% wage rise. There are no other wage rises given during the year.
Annual leave payments made during the year were debited against the provision account. The total debit against the annual leave account during the year in relation to leave taken was:
There are 260 work days in a year. On 1 July each year all employees receive a 5% wage rise. There are no other wage rises given during the year.
Annual leave payments made during the year were debited against the provision account. The total debit against the annual leave account during the year in relation to leave taken was: (Multiple Choice)
4.8/5 (75)
(75) Which of the following obligations do NOT arise from past services provided by an employee?
(Multiple Choice)
5.0/5 (68)
(68) Which of the following types of employee benefits are required to be measured at the present value of expected future cash flows?
(Multiple Choice)
4.8/5 (69)
(69) An entity is required to recognise a liability for short-term compensated absences that are:
(Multiple Choice)
4.8/5 (67)
(67) Which of the following types of employee benefits are required to be measured at their
Nominal value?
(Multiple Choice)
4.8/5 (78)
(78) AASB 119 requires short-term employee benefits to be measured at:
(Multiple Choice)
4.8/5 (71)
(71) Which if the following is NOT an example of a short-term employee benefit?
(Multiple Choice)
5.0/5 (85)
(85) The key difference between defined benefit and defined contributions post-employment plans is that:
(Multiple Choice)
4.8/5 (68)
(68) ABC Ltd employs 5 staff. Each staff member is entitled to 20 days annual leave per annum. Leave loading of 17.5% is paid when the leave is taken.
On 31 December 2013 Joan Rivers left the company and was paid out her untaken leave entitlements. Joan had 12 days leave owing at 1 July 2013 and took 4 days leave between 1 July and 31 December 2013. Her salary at the time of her departure was $140 000.
There are 260 work days in a year. On 1 July each year all employees receive a 3% wage rise. There are no other wage rises given during the year.
The gross entitlement owing to Joan Rivers on 31 December 2013 was:
(Multiple Choice)
4.9/5 (93)
(93) If the amount paid to the defined contribution fund by an entity during the year is less than the amount payable in relation to service provided by employees, the entity must recognise:
(Multiple Choice)
4.8/5 (77)
(77) An increase in the present value of a defined benefit obligation resulting from employee service in the current period is referred to as:
(Multiple Choice)
4.9/5 (87)
(87) Which of the following do NOT fall within the definition of a termination benefit?
(Multiple Choice)
5.0/5 (86)
(86) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)