



 Chat with AI
Exam 18: Evaluating Investment Performance

Exam 1: Investments: Background and Issues79 Questions
Exam 2: Asset Classes and Financial Instruments85 Questions
Exam 3: Securities Markets94 Questions
Exam 4: Mutual Funds and Other Investment Companies90 Questions
Exam 5: Risk, Return, and the Historical Record89 Questions
Exam 6: Efficient Diversification89 Questions
Exam 7: Capital Asset Pricing and Arbitrage Pricing Theory89 Questions
Exam 8: The Efficient Market Hypothesis92 Questions
Exam 9: Behavioral Finance and Technical Analysis89 Questions
Exam 10: Bond Prices and Yields96 Questions
Exam 11: Managing Bond Portfolios90 Questions
Exam 12: Macroeconomic and Industry Analysis93 Questions
Exam 13: Equity Valuation94 Questions
Exam 14: Financial Statement Analysis88 Questions
Exam 15: Options Markets91 Questions
Exam 16: Option Valuation90 Questions
Exam 17: Futures Markets and Risk Management92 Questions
Exam 18: Evaluating Investment Performance78 Questions
Exam 19: International Diversification50 Questions
Exam 20: Hedge Funds65 Questions
Exam 21: Taxes, Inflation, and Investment Strategy74 Questions
Exam 22: Investors and the Investment Process86 Questions
Select questions type


Suppose you own two stocks, A and B. In year 1, stock A earns a 2% return and stock B earns a 9% return. In year 2, stock A earns an 18% return and stock B earns an 11% return. Which stock has the higher geometric average return?
(Multiple Choice)
4.7/5  (88)
(88) Suppose two portfolios have the same average return and the same standard deviation of returns, but Buckeye Fund has a lower beta than Husker Fund. According to the Treynor measure, the performance of Buckeye Fund
(Multiple Choice)
4.9/5 (70)
(70) The following data are available relating to the performance of Long Horn Stock Fund and the market portfolio:
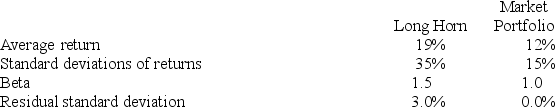 The risk-free return during the sample period was 6%.
Calculate the information ratio for Long Horn Stock Fund.
The risk-free return during the sample period was 6%.
Calculate the information ratio for Long Horn Stock Fund. (Multiple Choice)
4.9/5 (80)
(80) The following data are available relating to the performance of Sooner Stock Fund and the market portfolio:
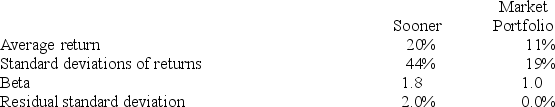 The risk-free return during the sample period was 3%.
What is the Sharpe measure of performance evaluation for Sooner Stock Fund?
The risk-free return during the sample period was 3%.
What is the Sharpe measure of performance evaluation for Sooner Stock Fund? (Multiple Choice)
4.8/5 (73)
(73) The following data are available relating to the performance of Long Horn Stock Fund and the market portfolio:
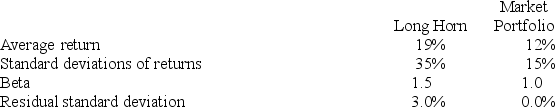 The risk-free return during the sample period was 6%.
Calculate the Jensen measure of performance evaluation for Long Horn Stock Fund.
The risk-free return during the sample period was 6%.
Calculate the Jensen measure of performance evaluation for Long Horn Stock Fund. (Multiple Choice)
4.9/5 (74)
(74) The following data are available relating to the performance of Sooner Stock Fund and the market portfolio:
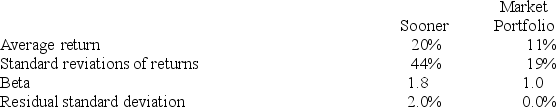 The risk-free return during the sample period was 3%.
Calculate the Jensen measure of performance evaluation for Sooner Stock Fund.
The risk-free return during the sample period was 3%.
Calculate the Jensen measure of performance evaluation for Sooner Stock Fund. (Multiple Choice)
5.0/5 (87)
(87) In a particular year, Aggie Mutual Fund earned a return of 15% by making the following investments in the following asset classes:
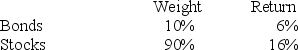 The return on a bogey portfolio was 10%, calculated as follows:
 The total excess return on the Aggie managed portfolio was
The return on a bogey portfolio was 10%, calculated as follows:
The total excess return on the Aggie managed portfolio was (Multiple Choice)
4.8/5 (78)
(78) Suppose you purchase one share of the stock of Volatile Engineering Corporation at the beginning of year 1 for $36. At the end of year 1, you receive a $2 dividend and buy one more share for $30. At the end of year 2, you receive total dividends of $4 (i.e., $2 for each share) and sell the shares for $36.45 each. The dollar-weighted return on your investment is
(Multiple Choice)
4.9/5 (76)
(76) Suppose you purchase one share of the stock of Cereal Correlation Company at the beginning of year 1 for $50. At the end of year 1, you receive a $1 dividend and buy one more share for $72. At the end of year 2, you receive total dividends of $2 (i.e., $1 for each share) and sell the shares for $67.20 each. The dollar-weighted return on your investment is
(Multiple Choice)
4.8/5 (89)
(89) The following data are available relating to the performance of Sooner Stock Fund and the market portfolio:
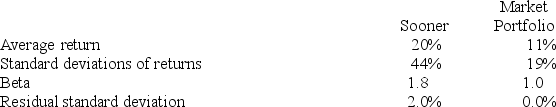 The risk-free return during the sample period was 3%.
What is the Treynor measure of performance evaluation for Sooner Stock Fund?
The risk-free return during the sample period was 3%.
What is the Treynor measure of performance evaluation for Sooner Stock Fund? (Multiple Choice)
5.0/5 (87)
(87) The following data are available relating to the performance of Wildcat Fund and the market portfolio:
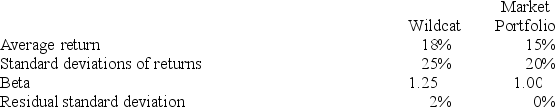 The risk-free return during the sample period was 7%.
Calculate Treynor's measure of performance for Wildcat Fund.
The risk-free return during the sample period was 7%.
Calculate Treynor's measure of performance for Wildcat Fund. (Multiple Choice)
4.8/5 (69)
(69) The following data are available relating to the performance of Monarch Stock Fund and the market portfolio:
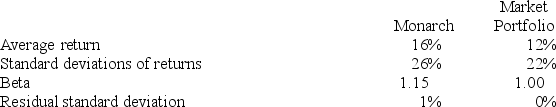 The risk-free return during the sample period was 4%.
Calculate Sharpe's measure of performance for Monarch Stock Fund.
The risk-free return during the sample period was 4%.
Calculate Sharpe's measure of performance for Monarch Stock Fund. (Multiple Choice)
4.7/5 (71)
(71) Suppose you buy 100 shares of Abolishing Dividend Corporation at the beginning of year 1 for $80. Abolishing Dividend Corporation pays no dividends. The stock price at the end of year 1 is $100, $120 at the end of year 2, and $150 at the end of year 3. The stock price declines to $100 at the end of year 4, and you sell your 100 shares. For the four years, your geometric average return is
(Multiple Choice)
4.8/5 (81)
(81) Suppose two portfolios have the same average return and the same standard deviation of returns, but Buckeye Fund has a lower beta than Husker Fund. According to the Sharpe measure, the performance of Buckeye Fund
(Multiple Choice)
4.9/5 (89)
(89) Suppose you purchase one share of the stock of Volatile Engineering Corporation at the beginning of year 1 for $36. At the end of year 1, you receive a $2 dividend and buy one more share for $30. At the end of year 2, you receive total dividends of $4 (i.e., $2 for each share) and sell the shares for $36.45 each. The time-weighted return on your investment is
(Multiple Choice)
4.8/5 (80)
(80) Suppose two portfolios have the same average return and the same standard deviation of returns, but Buckeye Fund has a higher beta than Husker Fund. According to the Treynor measure, the performance of Buckeye Fund
(Multiple Choice)
5.0/5 (84)
(84) The following data are available relating to the performance of Sooner Stock Fund and the market portfolio:
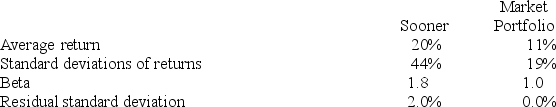 The risk-free return during the sample period was 3%.
Calculate the information ratio for Sooner Stock Fund.
The risk-free return during the sample period was 3%.
Calculate the information ratio for Sooner Stock Fund. (Multiple Choice)
4.9/5 (79)
(79) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)