



 Chat with AI
Exam 18: Accounting for Income Taxes

Exam 1: The Demand for and Supply of Financial Accounting Information89 Questions
Exam 2: Financial Reporting: Its Conceptual Framework87 Questions
Exam 3: Review of a Companys Accounting System146 Questions
Exam 4: The Balance Sheet and the Statement of Shareholders Equity112 Questions
Exam 5: The Income Statement and the Statement of Cash Flows151 Questions
Exam 6: Cash and Receivables149 Questions
Exam 7: Inventories: Cost Measurement and Flow Assumptions123 Questions
Exam 8: Inventories: Special Valuation Issues148 Questions
Exam 9: Current Liabilities and Contingencies128 Questions
Exam 10: Property, Plant, and Equipment: Acquisition and Subsequent Investments105 Questions
Exam 11: Depreciation, Depletion, Impairment, and Disposal143 Questions
Exam 12: Intangibles105 Questions
Exam 13: Investments and Long-Term Receivables140 Questions
Exam 14: Financing Liabilities: Bonds and Notes Payable171 Questions
Exam 15: Contributed Capital154 Questions
Exam 16: Retained Earnings and Earnings Per Share111 Questions
Exam 17: Advanced Issues in Revenue Recognition113 Questions
Exam 18: Accounting for Income Taxes108 Questions
Exam 19: Accounting for Postretirement Benefits98 Questions
Exam 20: Accounting for Leases149 Questions
Exam 21: The Statement of Cash Flows107 Questions
Exam 22: Accounting for Changes and Errors130 Questions
Exam 23: Time Value of Money Module121 Questions
Select questions type


The presentation of the combination or "offsetting" of noncurrent deferred tax assets and liabilities is
(Multiple Choice)
4.9/5  (87)
(87) As of December 31, 2014, the Williamsburg Company reported a deferred tax asset of $60,000 related to accrued, unpaid warranty costs. However, since profits have been declining, Williamsburg decides that it is more likely than not that $24,000 of the deferred tax asset will not be realized. The entry to record the valuation allowance would include a
(Multiple Choice)
4.9/5 (78)
(78) Interperiod tax allocation is required for all of the following situations except
(Multiple Choice)
4.8/5 (86)
(86) The recognition of gross profit on installment sales at point of sale for financial reporting purposes but reporting the profit when the cash is received for income tax purposes results in deferred taxes reported in which section of the balance sheet?
(Multiple Choice)
4.9/5 (86)
(86) Temporary differences arise when expenses or losses are deducted to compute taxable income 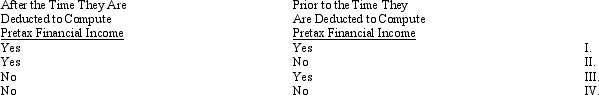
(Multiple Choice)
4.9/5 (67)
(67) Rehobeth Company's taxable income and other financial data for 2014 are presented below:
 Required: a.Calculate Rehobeth Company's 2014 pretax financial income.
b.For each item, explain why there is a difference, if any exists, between how it is treated for taxable income purposes and pretax financial income.
Required: a.Calculate Rehobeth Company's 2014 pretax financial income.
b.For each item, explain why there is a difference, if any exists, between how it is treated for taxable income purposes and pretax financial income. (Essay)
4.9/5 (78)
(78) On December 31, 2014, the Town Hall Company had a deferred tax liability balance of $12,570, arising from an excess of MACRS depreciation for tax purposes over straight-line depreciation for accounting purposes. The tax effects of that timing difference are expected to reverse in the following years: 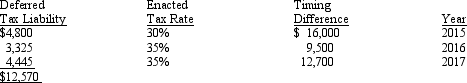 On January 27, 2015, Congress raised the effective income tax rate to 38% for all future years, including the current year, 2015.
Required:
Prepare the entry to record any adjustments necessary due to the income tax rate increase on January 27, 2015.
On January 27, 2015, Congress raised the effective income tax rate to 38% for all future years, including the current year, 2015.
Required:
Prepare the entry to record any adjustments necessary due to the income tax rate increase on January 27, 2015. (Essay)
4.8/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)